Markets & Finance
PSX & KSE Forecast 2026: Navigating the Latest IMF Reports & World Bank Metrics

Key Takeaways
- The KSE-100 index closed FY2025-26 at 180,301 points, a 44% rupee-terms gain for the fiscal year, and has posted a 335% three-year cumulative return across FY24–FY26.
- As of mid-September 2026, the index trades around 170,500, down roughly 5.4% over the past month but still +10.4% year-over-year, after touching an all-time intraday high above 189,500.
- Pakistan’s rally is anchored in a disbursing IMF Extended Fund Facility (EFF) program, improving FX reserves, and record remittance inflows — but the market remains highly sensitive to Middle East escalation risk.
- A key IMF mission review is expected around September 23, 2026, alongside ongoing monitoring of the Strait of Hormuz situation, both of which could swing the index materially in either direction.
- The IMF’s July 2026 World Economic Outlook projects global growth of 3.0% in 2026 and 3.4% in 2027, with emerging markets like Pakistan navigating this backdrop unevenly depending on their energy exposure.
Pakistan’s stock market has quietly delivered one of the best multi-year runs of any major frontier or emerging market, even as the country’s headlines remain dominated by floods, fiscal deficits, and geopolitical tension. For investors trying to separate durable reform momentum from short-term noise, this PSX and KSE forecast walks through the fiscal-year numbers, the IMF and World Bank data underpinning the rally, and the risks that could still derail it heading into Q4 2026.
The FY26 Scorecard: A Record-Breaking Year
The Pakistan Stock Exchange’s benchmark KSE-100 Index closed fiscal year 2025-26 (ending June 30, 2026) at 180,301 points, up 44% from 125,627 at the close of FY25. Extend the window further and the picture gets even more striking: across FY24, FY25, and FY26 combined, the index delivered a cumulative gain of 335% in rupee terms (347% in USD terms) — a run that ranks among the best-performing major equity markets globally over that stretch, according to analysis from Business Recorder.
The fiscal year itself was a story of two distinct halves. In the first half of FY26, the market returned 39%, driven by improving economic indicators despite the July–August 2025 floods. The second half was far choppier, returning just 4% overall and including a sharp pullback to an intraday low of 146,480 on March 9, 2026 amid escalating Middle East geopolitical tension — a reminder that Pakistan’s domestic reform story cannot fully insulate the market from external shocks.
Where the Index Stands Today
As of September 11, 2026, the KSE-100 traded at roughly 170,512 points, up 0.98% on the session but down 5.43% over the trailing month. Even after that pullback, the index remains 10.41% higher year-over-year. Trading Economics data shows the index has touched an all-time high above 189,556 points during 2026, underscoring just how volatile the second half of the fiscal year has been relative to the steady climb of the first half.
The IMF Anchor: Why It Matters More Than Ever
Pakistan’s macro stability story in 2026 is inseparable from its IMF-supported program — a $7 billion Extended Fund Facility (EFF) combined with a Resilience and Sustainability Facility (RSF) arrangement. Analysts at economy-focused outlets have described the continuation of this program as “another major pillar supporting macroeconomic stability,” since it facilitates external financing and reinforces investor confidence at a time when Pakistan’s own reserve buffers remain thin relative to import needs.
A closely watched IMF mission review around September 23, 2026 stands out as a near-term catalyst. Historically, PSX rallies have coincided tightly with positive IMF review outcomes — the market’s sharpest single-day gain in 26 years, a 9.45% surge, followed confirmation of IMF loan approval alongside a Pakistan-India ceasefire earlier in the current multi-year rally. A disappointing review outcome, by contrast, has historically triggered rapid, double-digit-percentage pullbacks.
How Pakistan Fits the IMF’s Global Growth Picture
The IMF’s July 2026 World Economic Outlook Update — among the most important IMF Reports for emerging-market investors this year — projects global growth of 3.0% for 2026 and 3.4% for 2027, broadly unchanged cumulatively from April. The Fund frames the global picture as a tug-of-war between two forces: a negative supply shock from the Middle East war weighing on energy importers, and a positive technology investment cycle lifting countries integrated into AI-driven global supply chains.
Pakistan sits closer to the vulnerable side of that divide as a net energy importer, which is precisely why the KSE-100’s resilience through 2026 — despite the war, despite a global inflation forecast revised up to 4.7% for 2026 — has impressed regional analysts. The World Bank’s parallel commentary on frontier and emerging Asian markets has similarly flagged energy-import exposure as the key swing factor for growth and currency stability across the region through year-end.
KSE-100 Performance Snapshot
| Period | KSE-100 Level | Change |
|---|---|---|
| End of FY25 (June 30, 2025) | 125,627 | — |
| End of FY26 (June 30, 2026) | 180,301 | +44% (FY26) |
| Intraday low (March 9, 2026) | 146,480 | Middle East tension selloff |
| All-time intraday high (2026) | 189,556 | — |
| Current level (Sept 11, 2026) | ~170,512 | -5.43% trailing month, +10.41% YoY |
Why This Matters for Investors: The Bull and Bear Case
The bull case rests on three durable pillars: a disbursing, credible IMF program extending into FY27; strengthening FX reserves; and record remittance inflows that continue to support the rupee independent of equity flows. Trailing valuations remain in the single-digit P/E range by several analyst estimates — cheap by both historical and regional emerging-market standards, even after the multi-year rally.
The bear case is just as concrete: the index’s near-term direction is now, in the words of one PSX-focused analysis, “a leveraged bet on Middle East de-escalation as much as on domestic policy execution.” Any material escalation around the Strait of Hormuz, or a disappointing outcome from the September 23 IMF mission, could swing the index by double-digit percentages within weeks — as the March 2026 pullback already demonstrated.
Frequently Asked Questions
Is the KSE-100 still a good investment after its 44% FY26 gain?
Analysts remain constructively positioned given single-digit trailing P/E multiples and continued IMF program support into FY27, though the market’s sensitivity to Middle East escalation means near-term volatility should be expected regardless of the longer-term reform trajectory.
What is driving the KSE-100’s volatility in 2026?
The index’s first-half FY26 gains were driven by improving domestic macroeconomic indicators, while second-half volatility — including a sharp March 2026 pullback — has been driven primarily by escalating Middle East geopolitical tension and its impact on oil-import costs.
How does the IMF’s global economy outlook affect Pakistan specifically?
The IMF’s July 2026 forecast of 3.0% global growth and 4.7% global inflation for 2026 reflects a world split between energy-importer headwinds and AI-driven technology tailwinds. As a net energy importer, Pakistan faces more of the former, making its IMF program and FX reserve trajectory especially important to watch.


Key Takeaways
- Japan is considering nearly doubling its midterm defense spending target to 3.5% of GDP — up from current levels of roughly 1.9% — under pressure from the Trump administration to match commitments made by NATO members and South Korea.
- A 3.5% target would amount to roughly ¥24 trillion annually, based on current GDP forecasts, more than double today’s spending level; a lower 3.0% target is also reportedly under consideration.
- Japanese 10-year government bond yields have already climbed to their highest levels since 1996, reflecting investor concern about how Japan — which carries the world’s highest debt-to-GDP ratio among advanced economies at nearly 240% — would finance the increase.
- Defense contractor stocks on the Tokyo Stock Exchange have risen in anticipation of the spending shift, even as broader market strategists warn the announcement could “send a shockwave through financial markets” concerned about PM Sanae Takaichi’s overall fiscal trajectory.
- A new five-year defense spending plan is expected by the end of 2026, meaning markets will be watching for confirmation of the final target — 3.0% or 3.5% — in the coming months.
Japan’s defense budget has broken its own record for 14 consecutive years, but the shift now under consideration in Tokyo represents something categorically different: a near-doubling of the country’s spending target, driven not by regional threat assessments alone but by direct pressure from Washington. For global economy watchers, the implications reach well beyond defense contractors into Japanese government bond markets, the yen, and the Bank of Japan’s already delicate policy path.
The New Target Under Consideration
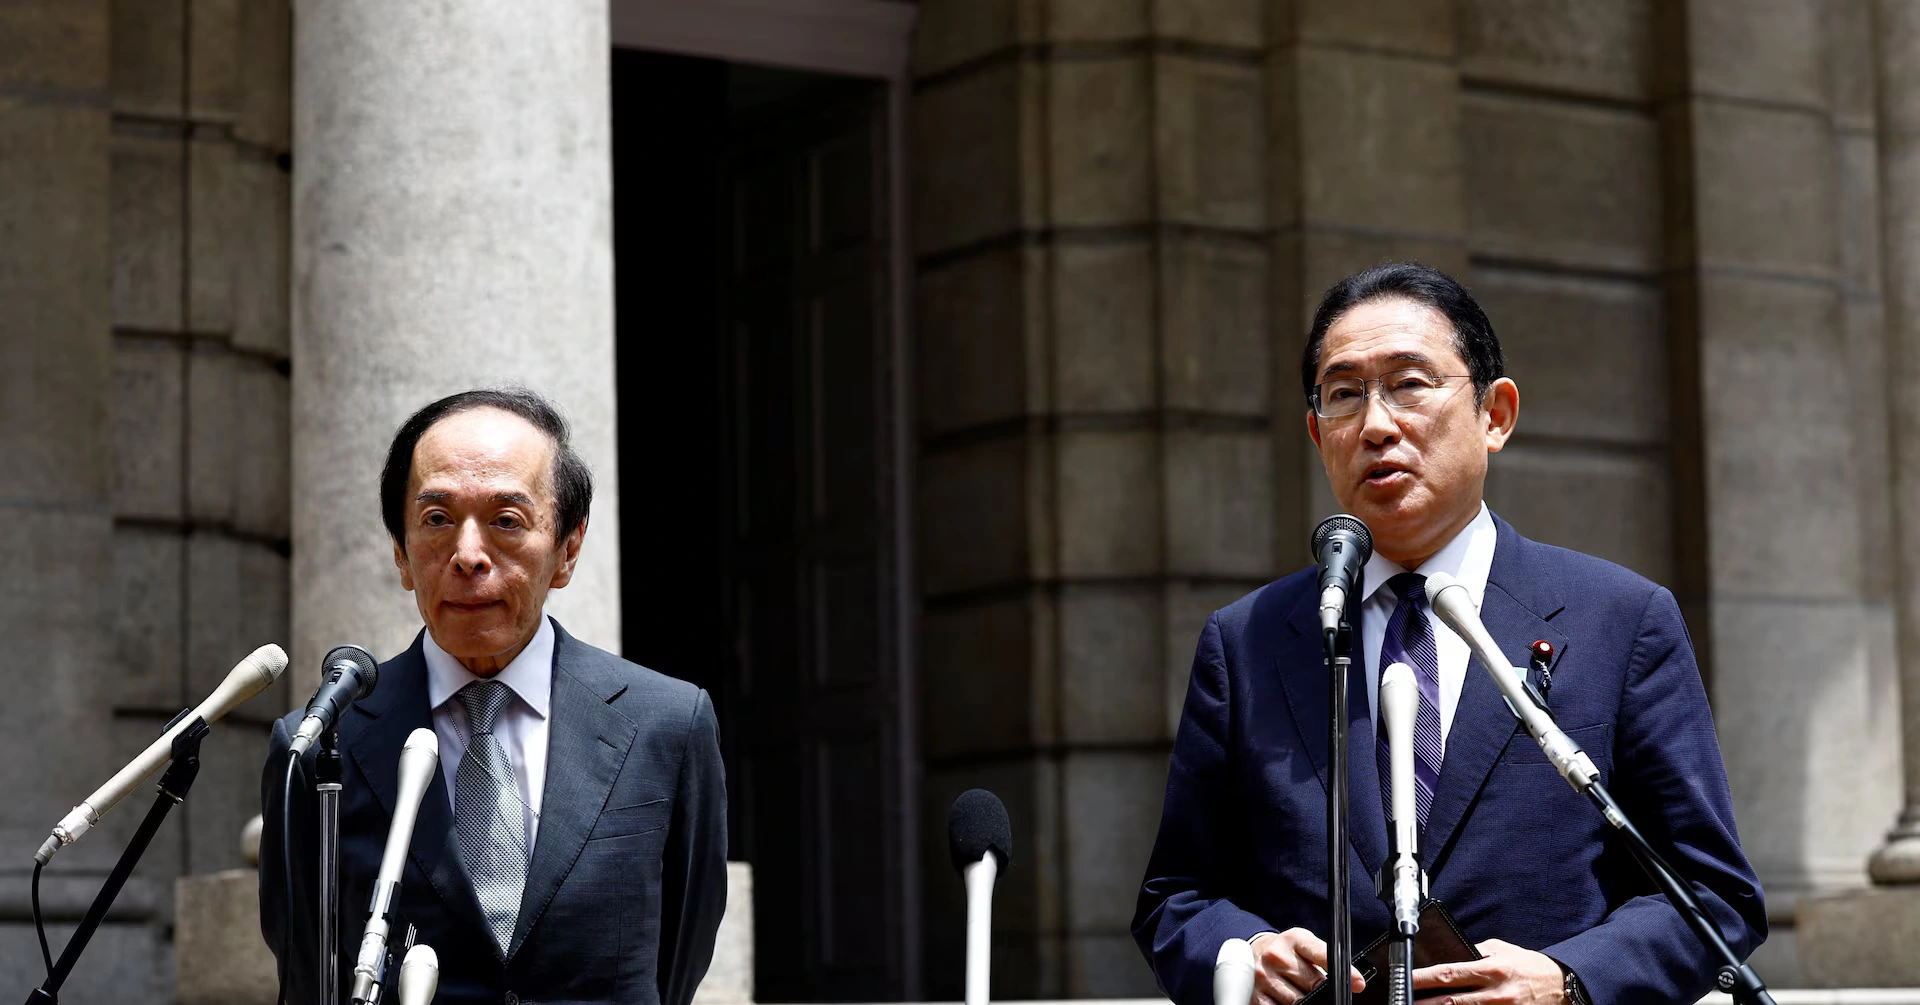
According to people familiar with the matter, Japan’s government — under Prime Minister Sanae Takaichi — is weighing a new midterm defense spending target of 3.5% of GDP, aligning with commitments already made by NATO members and, more strikingly, by South Korea, which has pledged to reach that level over 10 years. Japanese defense officials have reportedly already signaled willingness to sharply increase spending in meetings with their US counterparts, though a lower 3.0% target remains an alternative under discussion.
To put the scale of this shift in context: until 2022, Japan maintained an informal spending ceiling around just 1% of GDP — a figure rooted in the country’s post-war pacifist constitutional framework. Takaichi has already accelerated Japan toward the more modest 2% target two years ahead of schedule, reaching nearly that level in the fiscal year ended March 2026. A jump to 3.5% would represent roughly ¥24 trillion in annual spending based on current GDP projections — more than double the current outlay, and a figure that dwarfs the roughly ¥9-10 trillion currently being requested for the next fiscal year’s defense budget alone.
Why Now: US Pressure and the NATO Benchmark
The push traces directly to the Trump administration’s broader effort to have allies shoulder more of their own defense costs and reduce reliance on the American military umbrella. The 3.5%-of-GDP figure has effectively become a global benchmark for US allies since NATO members adopted it, with Japan’s neighbors South Korea and Taiwan reportedly making similar pledges. For Tokyo specifically, the pressure carries added urgency given ongoing regional security concerns and the broader reassessment of US alliance commitments happening globally in 2026.
Notably, even Takaichi’s more modest current-year progress — nearing 2% of GDP two years ahead of schedule — already drew praise in Washington, but analysts at the Center for Strategic and International Studies have noted this success is likely to raise expectations for even further increases in Japan’s next defense buildup program, expected to be finalized by the end of 2026.
The Fiscal Math Problem
Japan’s fiscal starting position makes this proposal considerably more fraught than a simple budget-line adjustment. The country already carries the world’s highest debt-to-GDP ratio among advanced economies, at nearly 240% — meaning any large new spending commitment raises immediate questions about financing, whether through new bond issuance, tax increases, or some combination. Takaichi has publicly pledged to pursue a “responsible, proactive fiscal policy,” but bond markets are already signaling skepticism: Japanese 10-year government bond yields have climbed to their highest levels since 1996, reflecting growing investor concern about debt sustainability even before any formal 3.5% commitment is finalized.
Bond Market and Equity Reaction
The market response so far has bifurcated in a telling way. On one hand, major Japanese defense companies have risen on the Tokyo Stock Exchange as investors price in the prospect of substantially higher government contracts. On the other, the broader bond market reaction has been notably more cautious — rising JGB yields reflect concern that large new debt issuance to fund the buildup could strain Japan’s already stretched fiscal position, with potential knock-on effects for borrowing costs across the economy.
Spending Target Comparison
| Scenario | Target (% of GDP) | Est. Annual Spending | Status |
|---|---|---|---|
| Pre-2022 informal ceiling | ~1.0% | N/A | Historical baseline |
| Current target (achieved early) | ~2.0% | ~¥9-10 trillion | Reached FY2026, 2 years ahead of schedule |
| Under consideration (lower option) | 3.0% | N/A | Reportedly discussed |
| Under consideration (NATO-aligned option) | 3.5% | ~¥24 trillion | Reportedly discussed; matches South Korea’s 10-year pledge |
Why This Matters for the BOJ and Global Markets
A defense-spending shift of this magnitude complicates an already difficult picture for the Bank of Japan, which has been gradually moving away from decades of ultra-loose monetary policy even as it monitors the same Middle East-driven inflation pressures affecting central banks globally. Rising JGB yields tied to defense-spending concerns could interact with — and potentially amplify — the BOJ’s separate rate-hike considerations tied to domestic inflation, creating a more complex policy balancing act than either factor would present alone.
There’s also a broader global bond-market angle: some strategists have pointed to Japan’s rising rates as a factor behind a potential unwinding of the long-popular yen carry trade, in which investors borrow cheaply in Japan to invest in higher-yielding assets elsewhere. As Japanese yields climb — whether from defense spending, BOJ policy, or both — that trade becomes progressively less attractive, a dynamic some analysts have linked to recent volatility in global government bond markets more broadly, including the US Treasury market’s own yield surge this same week.
Frequently Asked Questions
Why is Japan considering raising defense spending to 3.5% of GDP?
The shift is driven primarily by pressure from the Trump administration for US allies to spend more on their own defense, aligning with commitments already made by NATO members and Japan’s neighbor South Korea, which pledged to reach 3.5% of GDP over 10 years.
How would Japan pay for a defense spending increase to 3.5% of GDP?
This remains unresolved and is a major market concern — Japan already carries the world’s highest debt-to-GDP ratio among advanced economies at nearly 240%, and rising Japanese government bond yields suggest investors are pricing in financing concerns ahead of any formal commitment.
When will Japan finalize its new defense spending target?
A new five-year defense spending plan is expected to be released by the end of 2026, which should clarify whether Japan settles on the 3.0% or 3.5% of GDP target currently under consideration.

Every fourth quarter forces the same question onto the desk of every wealth management advisory: which stores of value earn a place in the model portfolio when the macro backdrop is this unstable? Heading into Q4 2026, that question has a sharper edge than usual. Gold is trading near $4,400–$4,450 per troy ounce, still up more than 4% on the month even after wiping out much of its mid-August gains, while Bitcoin has spent the second half of the year rebuilding support in the high-$70,000s after cratering from its October 2025 all-time high of $126,073. Silver, meanwhile, is the standout performer of 2026, up roughly 63% year-over-year and trading around $65–$68 an ounce.
This is not a year in which “buy the haven asset and wait” is sufficient advice. It is a year in which the composition of a hard-asset allocation — gold versus silver versus Bitcoin, physical versus paper, spot versus futures — determines whether a portfolio actually hedges the risks in front of it: a Federal Reserve caught between a hawkish Chair and a weakening labor market, oil pushing back toward $100 a barrel on renewed Middle East escalation, and a dollar sliding to four-month lows.
Key Takeaways
- Gold is holding a structural bid from record central bank buying and remains the highest-conviction defensive asset for Q4 2026, even after retreating from January’s $5,597.23 all-time high.
- Silver has outperformed gold on a percentage basis in 2026, but its higher volatility and industrial-demand sensitivity make it a tactical, not core, holding.
- Bitcoin is trading roughly 38% below its October 2025 peak and is behaving more like a high-beta risk asset than a stable hedge — a fact institutional flow data now confirms directly.
- The Federal Reserve’s September 15–16 policy meeting is the single most important near-term catalyst for all three assets, with markets pricing a real probability of a rate hike, not a cut, for the first time this cycle.
- A blended barbell allocation — core gold, a smaller tactical silver sleeve, and a conviction-sized Bitcoin position — is the framework most wealth management advisory desks are now recommending over a single-asset hedge.
The Q4 2026 Macro Backdrop: Why Precious Metals Are Repricing Risk
The single biggest driver of gold price today dynamics is not inflation in isolation — it’s the collision of inflation, fiscal risk, and geopolitical escalation happening simultaneously. Fresh escalation in the Iran conflict has pushed Brent crude back toward the $100/barrel threshold, which is feeding directly into headline CPI expectations one week before the Fed’s rate decision. At the same time, Fed Chair Kevin Warsh has signaled the central bank still has “work to do” on price control, and CME FedWatch data has shown the probability of a 25-basis-point hike at the September meeting swinging as high as 66.4% — a dramatic reversal from expectations just weeks earlier that the Fed would be cutting.
This is the paradox advisors need to explain to clients: gold is rallying despite elevated rate-hike odds, which historically pressure non-yielding assets. That is a signal in itself. It tells you the market is pricing gold less as a pure real-rate trade and more as structural insurance against fiscal and geopolitical fragility — a distinction that should inform position sizing for the rest of 2026.
Gold: The Central Bank Bid Has Not Broken
| Metric | Value (Sept 2026) | Context |
|---|---|---|
| Spot price | ~$4,400–$4,450/oz | Down from Jan 2026 record of $5,597.23 |
| Month-over-month | +4.1% | Holding gains despite recent pullback |
| Key demand driver | Record central bank buying | Structural, not cyclical |
| Key resistance | $4,500 | Repeated rejection point in August–Sept |
| 2026 round trip | Record high → -24% crash → rebound | Extreme volatility even within a “safe haven” |
Gold’s 2026 story has been a full round trip: a record $5,626 intraday spike in January, a brutal 24% correction into the second quarter, and a rebound back above $4,400 by late summer on renewed central bank accumulation and dollar weakness. The GLD ETF has seen periods of heavy institutional outflow (a single-day $2.91 billion withdrawal in March was the largest in over a decade), which tells advisors that retail and ETF investors have been more reactive than central banks, who have kept buying through the volatility. That divergence matters: central bank demand is the more durable signal for a Q4 allocation thesis.
Silver: Highest Torque, Highest Risk
Silver’s 173% year-over-year gain at its May peak and current ~63% YoY level make it the best-performing major hard asset of 2026, but the ride has been violent — an intraday range spanning roughly $40.72 to $121.58 over the past year. Silver’s dual identity as both a monetary metal and an industrial input (solar, electronics, defense manufacturing) means it amplifies gold’s macro moves in both directions. For a wealth management advisory building Q4 portfolios, silver functions best as a tactical satellite position, not a core allocation — sized to what a client can tolerate losing a third of in a single quarter.
Bitcoin: Digital Gold Narrative Is Losing the 2026 Argument
Bitcoin is currently trading near $77,000–$79,000, roughly 38–40% below its October 2025 all-time high of $126,073.42. JPMorgan’s own CME futures open-interest data — widely used as an institutional-positioning proxy — has shown hedge funds reducing direct Bitcoin exposure while rotating toward gold for defensive positioning through much of 2026. Gold ETF outflows have still outpaced Bitcoin ETF outflows on a relative-asset basis, and Tether’s own treasury (roughly 146 metric tons of gold versus ~98,933 BTC) illustrates that even crypto-native institutions are diversifying into bullion, not away from it.
None of this means Bitcoin is a bad asset for Q4 2026 — it means its role in the portfolio has shifted. It should be underwritten as a long-duration, high-volatility growth asset with optionality, not as the primary inflation or geopolitical hedge that gold remains.
Building the Q4 2026 Barbell: A Wealth Management Advisory Framework
| Client Risk Profile | Gold Allocation | Silver Allocation | Bitcoin Allocation | Rationale |
|---|---|---|---|---|
| Conservative / capital preservation | 8–12% | 0–2% | 0–1% | Gold as pure ballast; minimal volatility budget |
| Balanced / growth-with-income | 6–8% | 2–4% | 2–4% | Barbell: metals for stability, BTC for asymmetric upside |
| Aggressive / long horizon | 4–6% | 3–5% | 5–10% | Higher BTC conviction sized to tolerate a 30%+ drawdown |
The logic here is not novel, but the sizing discipline is what separates outperforming wealth management advisory practices from reactive ones in 2026: gold absorbs macro shock and provides crisis liquidity; silver captures industrial-cycle torque; Bitcoin provides long-run asymmetric upside tied to institutional adoption curves that are still compounding, just more slowly than 2024–2025 bulls expected.
Three Tactical Considerations Heading Into September 15–16
- Rate decision volatility risk. A surprise hike would likely pressure gold and Bitcoin simultaneously in the short term, even though gold’s structural bid should reassert within weeks. Advisors should stress-test client portfolios for a 5–8% precious-metals drawdown scenario around the meeting date.
- Dollar weakness as a tailwind. The dollar’s slide to a four-month low, driven partly by yen appreciation, is currently the most bullish near-term factor for dollar-denominated gold and silver — a trend worth monitoring through the ECB and BoJ’s own September decisions.
- Premium and liquidity costs. Physical gold and silver premiums remain elevated due to persistent supply-chain constraints on minted product; advisors allocating to physical bullion (versus ETFs or futures) should budget for those costs explicitly in client-facing return projections.
FAQ
Is now a good time to buy gold for a Q4 2026 portfolio?
Gold remains structurally supported by record central bank demand even after its correction from January’s all-time high. Most advisors view current levels as a reasonable entry point for core allocations, though clients should expect continued volatility around the Fed’s September and subsequent Q4 meetings.
Why has Bitcoin underperformed gold in 2026 despite the “digital gold” narrative? Institutional positioning data shows hedge funds rotating toward gold and away from direct Bitcoin exposure for defensive purposes in 2026. Bitcoin has behaved more like a high-volatility risk asset tied to liquidity conditions than a stable, uncorrelated hedge this year.
How much silver should a diversified portfolio hold?
Given silver’s extreme volatility — an intraday range of roughly $40 to $121 over the past year — most wealth management advisory desks recommend treating it as a tactical, smaller-sized satellite position rather than a core holding of equal weight to gold.
What is the single biggest near-term risk to precious metals prices?
A hawkish surprise from the Federal Reserve’s September meeting, where markets have priced a meaningfully higher-than-expected probability of a rate hike rather than a cut, is the most immediate catalyst that could pressure both gold and silver in the short term.

Every housing cycle produces a chorus of crash predictions, and 2026 has been no exception. But the data emerging through the third quarter tells a more measured story than the headlines suggest: this is a market undergoing what several major forecasters are now calling “The Great Recalibration” — not a collapse, but a prolonged, uneven reset in which affordability improves slowly, regionally, and unevenly rather than through a sharp price correction.
Key Takeaways
- No major forecaster — Fannie Mae, NAR, Zillow, Redfin, or Realtor.com — is projecting a national home price crash in 2026; forecasts cluster in a 1% to 4% annual price growth range.
- Existing home sales fell 4.2% in the first half of 2026, with June sales down 2.4% to a seasonally adjusted annual rate of 4.09 million units, according to the National Association of Realtors — softness driven by elevated mortgage rates, not distressed selling.
- 30-year fixed mortgage rates are expected to average roughly 6.3% through 2026, per consensus forecasts from Realtor.com, Redfin, and industry surveys — a “new equilibrium” rather than a return to sub-5% pandemic-era rates.
- Home values fell in 24 of the 50 largest US markets as of late 2025; Zillow projects that number to roughly halve to around 12 markets in 2026, indicating regional divergence rather than a uniform correction.
- Nearly two-thirds of prospective buyers (62%) have been waiting for rates to fall before purchasing — the same share that made the identical bet in 2025 and were wrong, underscoring the risk of timing the market on rate predictions alone.
The State of the 2026 Housing Market: Reset, Not Crash
The consensus among major housing economists — at Redfin, Zillow, NAR, Fannie Mae, and J.P. Morgan Global Research — is unusually aligned for a sector prone to disagreement: 2026 is a “recalibration” year, characterized by softening sales volume, modest price growth, and mortgage rates settling into a new, higher-than-pandemic-era range rather than a sharp downward price correction.
J.P. Morgan Global Research’s mid-2026 housing outlook noted that existing home sales pulled back 2.4% in June to a seasonally adjusted annual rate of 4.09 million units, extending a first-half 2026 decline of 4.2%. The bank attributed the softness directly to elevated mortgage rates rather than to distressed inventory or forced selling — a critical distinction from the dynamics that preceded the 2008 crash, where oversupply and subprime defaults, not rate-driven demand softness, drove the collapse.
Mortgage Rate Trajectory: The Central Variable
Mortgage rates remain the single most important variable shaping the 2026 housing market. Forecasts have converged around an average 30-year fixed rate near 6.3% for the year, with Fannie Mae’s Home Price Expectations Survey — which polls more than 100 housing economists — projecting home prices to rise a modest 1.7% in 2026 and 2% in 2027 under that rate assumption. Some forecasters see slightly more optimistic paths: S&P Global has projected an average closer to 5.77%, while Zillow has taken the more cautious position that rates will likely stay above 6% throughout 2026 despite gradual easing.
| Forecaster | 2026 Home Price Growth | 2026 Mortgage Rate (30-yr avg) |
|---|---|---|
| Fannie Mae | +3.2% | ~6.3% |
| National Association of Realtors | +4.0% (median price) | ~6.3% |
| Mortgage Bankers Association | +0.6% | ~6.3% |
| Realtor.com | +2.2% | ~6.3% |
| Zillow | +1.2% | Above 6% |
| Redfin | +1.0% | Low 6% range |
No forecaster in this table projects a price decline — the dispersion is between “modest growth” and “very modest growth,” which is the clearest quantitative rebuttal to crash narratives currently circulating in social media and lower-authority financial commentary.
Regional Divergence: Where the Real Risk Sits
The national picture obscures significant regional variation, and this is where “crash predictions” have the most factual grounding — at the metro level, not the national level. Zillow’s research noted that home values fell in 24 of the 50 largest US markets as of October 2025, with that number of declining markets expected to roughly halve to about 12 in 2026 as affordability improves. This implies that roughly a quarter of major US metros experienced genuine, if modest, price depreciation heading into 2026 — a regional reality that gets flattened into “national crash” narratives online but is more accurately described as localized correction concentrated in previously overheated Sun Belt and pandemic-boomtown markets.
Inventory: The Structural Wildcard
Inventory levels are projected to increase by approximately 8.9% to 12% in 2026, according to appraisal-industry forecasting, though they remain below pre-pandemic averages. This matters directly for crash risk: a genuine price collapse typically requires oversupply relative to demand. Current inventory growth, even at the high end of forecasts, is not projected to push supply into the oversupplied territory that preceded the 2008 downturn — it is a gradual normalization from historically tight conditions, not a supply glut.
The “Waiting for Rates to Fall” Trap
One of the more revealing data points for 2026 buyer psychology comes from a U.S. News survey: nearly two-thirds of prospective homebuyers (62%) were waiting for mortgage rates to fall before buying in 2026 — and the identical share (62%) made the same bet in 2025, and lost it, as rates did not fall meaningfully. This is a behavioral pattern directly analogous to the cash-hoarding trap in personal savings: postponing action based on a rate prediction that forecasters themselves have repeatedly gotten wrong carries its own opportunity cost, particularly if home prices continue their modest upward drift as most forecasters project.
Mortgage Rate Strategies for 2026 Buyers and Owners
- Rate locks with float-down options. With rates expected to hover in a narrow 6.0%–6.5% band rather than swing dramatically, a float-down provision on a rate lock offers modest downside protection without requiring buyers to time a broader market move.
- Adjustable-rate mortgages for shorter holding periods. For buyers expecting to sell or refinance within 5–7 years, ARMs priced meaningfully below the 6.3% fixed-rate consensus can reduce carrying costs without exposure to a 30-year rate commitment.
- Points purchases in a stable-rate environment. Because forecasters see rates stabilizing rather than falling sharply, buying down the rate with points becomes more mathematically attractive than in a falling-rate environment where a near-term refinance might otherwise recapture the cost.
- Regional due diligence over national headlines. Given that roughly a quarter of major metros were still seeing price declines heading into 2026, buyers and investors should underwrite specific metro-level inventory and price-trend data rather than relying on national crash or boom narratives.
Frequently Asked Questions
Is the US housing market going to crash in 2026?
No major housing forecaster — including Fannie Mae, NAR, Zillow, Redfin, and the Mortgage Bankers Association — projects a national price decline in 2026; forecasts range from roughly 0.6% to 4% price growth, with existing home sales projected to be flat to modestly higher.
Why do home sales keep falling if prices aren’t crashing?
Existing home sales fell 4.2% in the first half of 2026 primarily because elevated mortgage rates (averaging around 6.3%) are suppressing transaction volume, not because of distressed or forced selling — a key structural difference from the 2008 crash.
Should I wait for mortgage rates to drop before buying?
Roughly 62% of buyers made this bet in both 2025 and 2026, and rates did not fall meaningfully either year according to consensus forecasts; buyers evaluating this strategy should weigh the opportunity cost of continued modest home-price appreciation against uncertain rate movement.
Conclusion
The 2026 real estate data supports a “Great Recalibration” thesis, not a crash thesis: sales volume is softening under the weight of a stabilized-but-elevated 6.3% mortgage rate environment, national price growth remains positive across every major forecaster, and the genuine downside risk is concentrated regionally in a shrinking subset of previously overheated metros rather than distributed nationally. For buyers, sellers, and investors, the 2026 opportunity lies less in timing a crash that the data does not support and more in navigating rate strategy and regional selection with precision.

So Delicious Dessert Recall: Affected Products, FDA Guidelines, and Consumer Action

Pakistan’s Current Account Deficit Narrows Sharply to $98 Million in August 2026

Japan Eyes 3.5% Defense Spending: What It Means for Bonds, Stocks, and the BOJ

PSX & KSE Forecast 2026: Navigating the Latest IMF Reports & World Bank Metrics

Trump Administration’s Crypto Policy: Deregulation and the Future of Digital Assets

Monetary Policy and the Policy Rate

Gold, Silver & Bitcoin Prices Q4 2026: Wealth Management Strategies

Business Insurance for Digital Exports: Protecting Your Company in the AI Era

Real Estate Crash Predictions 2026: Data-Backed Regional Guide

What is a “Lead-Left” Bank? Unpacking Morgan Stanley’s Role in Anthropic’s Mega-IPO

Is SPY Overvalued in September 2026? Fed Rate Hike Odds & Intrinsic Value

Pakistan’s KSE-100 Nears Record Territory Even as the Trade Gap Persists

US Consumer Sentiment Sinks as Retail Sales Drop

Barclays Q2 2026 Results: Income Beats, Costs Rise 7%

Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities

Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World

Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns

China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech

What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact

15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide

Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation

China’s Property Woes Could Last Until 2030—Despite Beijing’s Best Censorship Efforts
-
 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
 Analysis8 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
 Asia9 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
 Global Economy9 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
 AI9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
 Exports9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025