
Global Economy
Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation

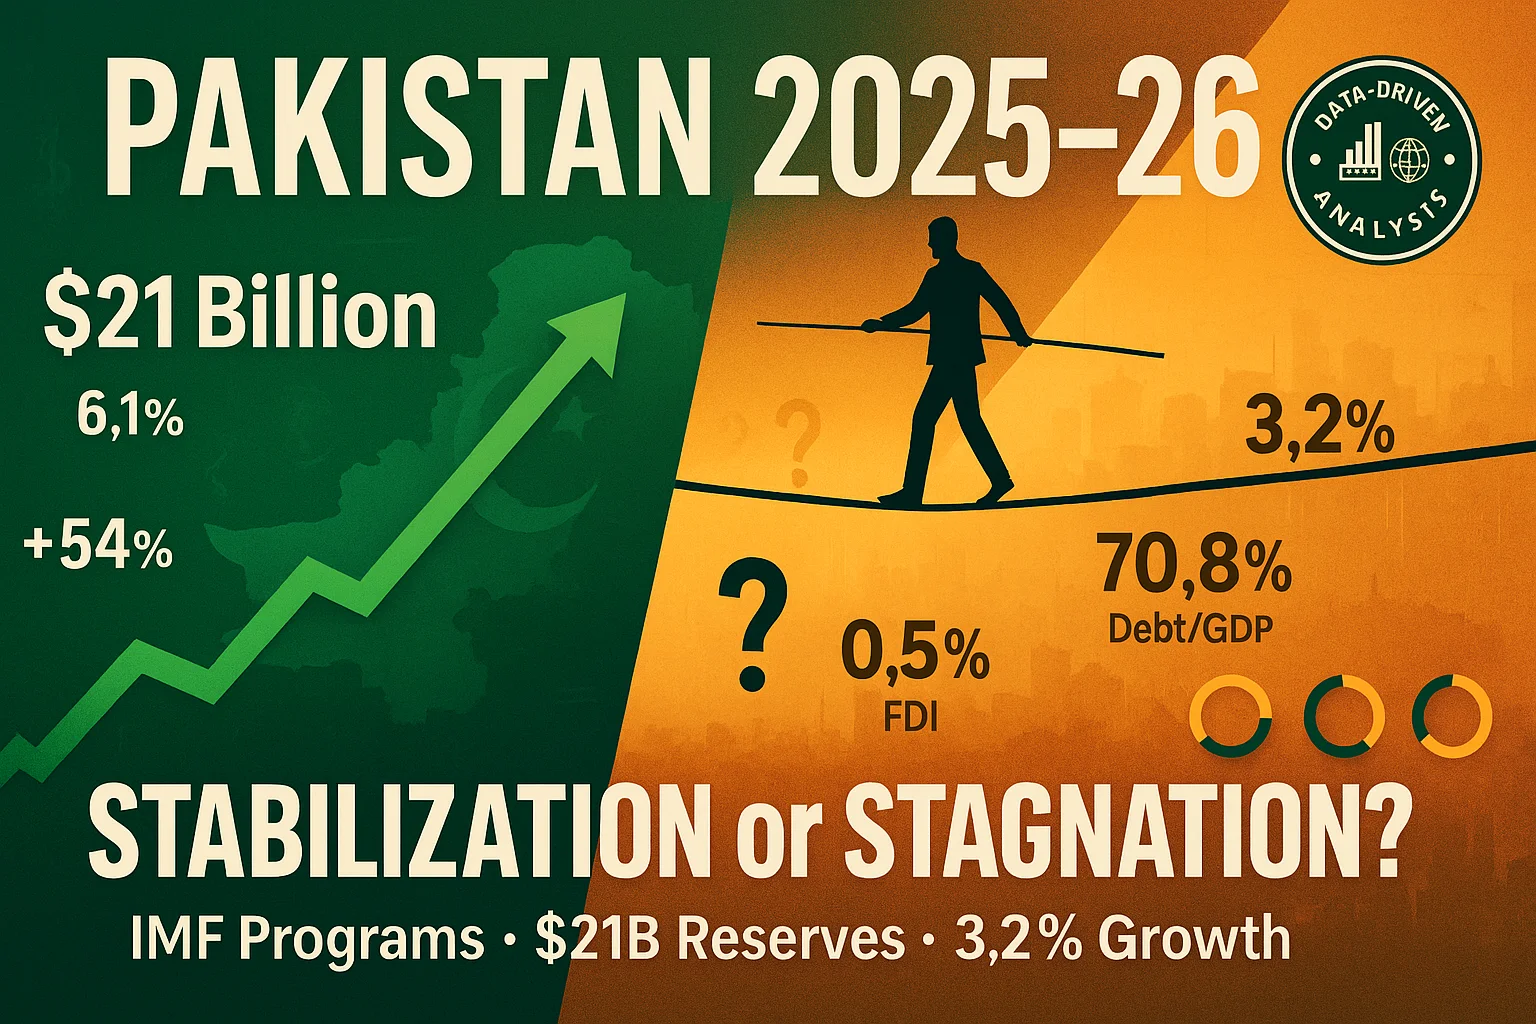
Can Pakistan finally break its bailout addiction, or is 2025 just another chapter in a recurring crisis?
Pakistan’s economy shows stabilization with $21B reserves and 6% inflation, but 3.2% growth barely exceeds population. Analyzing IMF programs, debt dynamics, and 2026 prospects for investors and policymakers.
The International Monetary Fund’s latest disbursement of $1.2 billion to Pakistan in December 2025 represents far more than a routine financial transaction. It’s a barometer of a nation caught between tentative stabilization and the persistent gravitational pull of economic inertia. Pakistan achieved a primary surplus of 1.3 percent of GDP in fiscal year 2025, in line with IMF targets, marking genuine fiscal progress. Yet beneath this achievement lies an uncomfortable truth: growth projections inch from 2.6% in FY25 to just 3.2% by FY26—barely matching population growth for a country of 240.5 million people.
This isn’t recovery. It’s containment.
For investors, policymakers, and Pakistan’s burgeoning middle class, 2025 presents a watershed moment. The immediate crisis of 2023—when foreign reserves plummeted to dangerously low levels and default fears paralyzed markets—has receded. But the challenge now is profoundly different: translating stabilization into sustained, inclusive growth that creates jobs and opportunities at scale.
The Stabilization Mirage: Real Progress or Borrowed Time?
Pakistan’s economic metrics tell a story of contradictions. On one hand, foreign exchange reserves surged to $21.1 billion as of December 2025, the highest level since March 2022. The rupee has shown unexpected resilience, with a 15.4 percent real effective appreciation in FY25 signaling currency stability after years of depreciation. The Pakistan Stock Exchange’s KSE-100 index has been nothing short of spectacular, climbing 54.70% year-over-year to reach 170,830 points, making it one of Asia’s strongest-performing equity markets.
These aren’t trivial achievements. Remittances hit a record $31.2 billion during the first ten months of fiscal year 2025, rising 30.9% year-over-year, with Saudi Arabia emerging as the top source. Inflation eased to 6.1% in November 2025 from a one-year high of 6.2% in October, a dramatic decline from the 23.4% average of the previous year.
“Pakistan’s economic outlook for 2025-2026 shows stabilization after crisis, with foreign reserves reaching $21 billion and inflation declining to 6.1%. However, GDP growth of 3.2% barely exceeds population growth, while 70.8% debt-to-GDP ratio and weak 0.5% FDI signal persistent challenges. The country must implement structural reforms to transition from containment to genuine inclusive growth.”
Yet dig deeper, and fragility persists. Foreign direct investment remains subdued at just 0.5-0.6% of GDP—levels that reflect continuing investor skepticism about Pakistan’s business environment. Unemployment is projected to fall only modestly from 8.3% to 7.5%, revealing weak job creation capacity. The country’s public debt reached Rs80.52 trillion (70.8% of GDP) by end-June 2025, up from Rs71.24 trillion the previous year—an increase of Rs9.3 trillion in a single year.
Consider what this means: Pakistan is running faster just to stay in place. Per capita income of $1,677 combined with 3.2% growth against 2% population growth translates to barely 1% improvement in living standards annually. For a nation where around 45% of the population lives below the poverty line according to a June 2025 World Bank report, this trajectory offers little hope.
The Debt Trap: Pakistan’s Fiscal Straitjacket
Here’s the brutal arithmetic constraining Pakistan’s future: nearly half of projected FY26 outlays—Rs7.5 trillion out of Rs17.4 trillion—is earmarked for debt servicing, equaling 77% of net federal revenues. This leaves Pakistan in what economists call “fiscal capture”—a situation where debt service crowds out virtually all productive spending.
Compare this globally. India, with debt around 82% of GDP, devotes 25-30% of central revenues to interest; Brazil spends roughly 20-25% with 88% debt-to-GDP. Pakistan’s debt servicing burden rivals Argentina’s, a country synonymous with fiscal distress. The difference? Pakistan borrows in currencies it cannot print, at interest rates it cannot control, making it acutely vulnerable to global financial shocks.
The IMF projects some relief, with public debt expected to decline from 70.8% to 60.8% of GDP by FY28 under continued fiscal consolidation. But this depends on maintaining primary surpluses of 2-2.5% of GDP annually—an extraordinary political challenge requiring sustained austerity in a democracy where 45% of citizens live in poverty.
What makes Pakistan’s debt particularly concerning isn’t just its size but its cost. Pakistan recorded a quarterly decline of Rs1.37 trillion in public debt in September 2025, the first since December 2019, achieved through early repayments of expensive debt. Yet the underlying structure remains precarious: domestic debt accounts for nearly half of GDP, keeping interest costs elevated, while external debt fell to 26% of GDP in FY25 from 31% two years earlier—progress, but from dangerously high levels.
The IMF Paradox: Lifeline or Dependency Trap?
Pakistan is operating under two simultaneous IMF programs: a 37-month Extended Fund Facility focused on economic stabilization and a Resilience and Sustainability Facility addressing climate vulnerabilities. Together, these have disbursed around $3.3 billion, with the latest reviews unlocking another $1.2 billion.
This marks Pakistan’s 25th IMF program since joining in 1950—a statistic that speaks volumes about the country’s inability to break its boom-bust cycle. Each program stabilizes the economy temporarily, but structural reforms remain incomplete. Tax collection as a percentage of GDP languishes around 10-11%, one of the lowest globally. Energy sector circular debt continues to accumulate despite repeated restructuring attempts. State-owned enterprises hemorrhage billions in losses annually.
The IMF’s 2025 Governance and Corruption Diagnostic Assessment found Pakistan’s economy loses an estimated 5-6.5% of GDP to corruption through “elite capture,” where influential groups shape policy for their benefit. This isn’t just morally troubling—it’s economically catastrophic. When market distortions and policy capture persist, private investment remains suppressed, foreign investors stay away, and productive capacity stagnates.
Yet paradoxically, the IMF program is working—at least on paper. The fiscal discipline it enforces has stabilized the currency, rebuilt reserves, and restored some international credibility. The question isn’t whether the IMF program is effective; it’s whether Pakistan can internalize these disciplines once external oversight ends.
2026 Prospects: Three Scenarios
Base Case: Muddle-Through Stabilization (60% probability)
Under current policies, Pakistan limps forward with 3-3.5% growth, just ahead of population expansion. The IMF program continues through 2027, providing external anchor and financing. The budget deficit narrows from -6.8% to -4.0% of GDP, with a primary surplus rising to 2.5%. Inflation stabilizes in the 5-7% range. Foreign reserves gradually build toward $25-28 billion by end-2026, providing 3.5-4 months of import cover.
This scenario delivers stability but not transformation. Living standards improve marginally. Job creation remains weak. Brain drain continues as educated Pakistanis seek opportunities abroad. The country avoids crisis but doesn’t achieve escape velocity. Think of it as economic purgatory—not hell, but certainly not heaven.
Upside Case: Reform Breakthrough (25% probability)
Imagine Pakistan actually implements long-delayed structural reforms. Tax-to-GDP ratio increases 2-3 percentage points through base broadening and digitalization. Major state-owned enterprises undergo genuine privatization, not cosmetic restructuring. Energy sector reforms sustainably reduce circular debt. The Special Investment Facilitation Council delivers $5-7 billion in Gulf investments, particularly in agriculture, IT, and mining.
In this scenario, growth accelerates to 4.5-5% by late 2026. Foreign direct investment doubles to 1-1.2% of GDP. The stock market rally continues, with the KSE-100 reaching 200,000 points. Pakistan begins attracting portfolio flows as international investors recognize improved fundamentals. Manufacturing competitiveness improves as energy costs decline.
What makes this plausible? Pakistan has demonstrated capacity for reform under pressure. The recent debt prepayment and fiscal consolidation show technical competence exists. The question is political will. Coalition governments prioritizing short-term survival over long-term transformation make sustained reform unlikely, but not impossible.
Downside Case: External Shock Relapse (15% probability)
Global commodity price spikes, particularly oil, blow out the current account. Regional geopolitical tensions escalate, disrupting trade and investor confidence. Political instability undermines policy continuity. Climate shocks—floods or droughts—require expensive emergency spending, blowing fiscal targets.
In this scenario, the current account deficit widens beyond 1% of GDP. Reserves deplete rapidly. The rupee comes under severe pressure. Inflation rebounds to double digits. The stock market corrects 30-40%. Pakistan returns to IMF mid-program for emergency adjustment, triggering another painful stabilization cycle.
This isn’t alarmist speculation—it’s Pakistan’s historical pattern. The country has faced similar setbacks repeatedly. What’s changed is improved reserve buffers and a more disciplined fiscal stance provide better shock absorption than in past cycles. But vulnerabilities remain acute.
The 2026 Inflection Point: What Must Happen
For Pakistan to transition from stabilization to genuine growth in 2026, five critical factors must align:
Revenue mobilization breakthroughs. Pakistan cannot sustain itself on 10-11% tax-to-GDP. Broadening the tax base, improving compliance, and rationalizing exemptions must deliver at least 1-1.5 percentage points of GDP in additional revenues. This isn’t technically difficult—digitalization and data integration can dramatically improve collection. It’s politically difficult because it requires taxing privileged sectors that have historically evaded their obligations.
Energy sector resolution. Circular debt and high electricity costs strangle industrial competitiveness. Pakistan’s electricity tariffs are among the highest in South Asia, making manufacturing globally uncompetitive. Addressing this requires politically painful decisions: rationalizing capacity payments to independent power producers, reducing transmission losses, improving recovery rates, and possibly renegotiating contracts. Without this, Pakistan cannot compete in global manufacturing.
Investment climate transformation. Why does Pakistan attract only 0.5% of GDP in FDI while Bangladesh draws 1.5% and Vietnam 6%? The answer: bureaucratic red tape, policy unpredictability, weak contract enforcement, and infrastructure deficits. Creating genuine one-stop investment facilitation, reducing regulatory approvals from months to weeks, and providing policy certainty would unlock billions in investment.
Export competitiveness revival. Pakistan’s exports have stagnated around $30-32 billion annually for years while regional peers have surged. Vietnam’s exports exceeded $370 billion in 2024; Bangladesh, despite political turmoil, maintains $45-50 billion. Pakistan needs export-led growth, requiring currency competitiveness, trade facilitation, value chain integration, and quality upgrading. The textile sector alone could double exports with better policy support.
Human capital investment. With 64% of the population under age 30, Pakistan possesses a demographic dividend that could propel growth—or become a demographic disaster if unmanaged. This requires massive investment in education, vocational training, and healthcare. Currently, education spending hovers around 2% of GDP, among the world’s lowest. Doubling this, with reforms ensuring quality, would transform long-term potential.
The Corruption Challenge: Elite Capture and Growth
The IMF’s corruption diagnostic reveals something Pakistan has long known but rarely confronted systematically: 5-6.5% of GDP is lost annually to corruption through elite capture. This isn’t petty bribery—it’s systemic policy distortion where powerful groups extract rents through protective regulations, subsidized inputs, tax exemptions, and procurement manipulation.
Consider the energy sector. Independent power producers negotiated extraordinarily favorable contracts in the 1990s and 2000s, guaranteeing dollar returns regardless of demand. These “capacity payments” now drain billions annually, creating circular debt that cascades through the economy. Why do these contracts persist? Because the beneficiaries have political influence to block reform.
Or examine tax exemptions. Pakistan grants hundreds of billions in tax expenditures annually—concessions to specific sectors, mostly benefiting large, connected businesses. A 2024 analysis found rationalizing just 30% of these exemptions could raise 1.5% of GDP in additional revenue. Yet reform stalls because beneficiaries lobby intensively against rationalization.
Breaking elite capture requires more than anti-corruption campaigns; it demands institutional reform: transparent procurement systems, merit-based bureaucracy, independent regulators, and genuine competition policy. The IMF diagnostic is helpful precisely because it shifts the conversation from moralistic hand-wringing to concrete institutional diagnostics.
Climate and Resilience: The Overlooked Variable
Here’s what makes Pakistan’s outlook uniquely precarious: climate vulnerability. The 2025 monsoon floods affected almost 7 million people and caused an estimated 0.6% of GDP in damage. This follows the catastrophic 2022 floods that inundated one-third of the country, causing $30 billion in damages.
Pakistan ranks among the world’s most climate-vulnerable nations despite contributing negligible global emissions. Rising temperatures threaten agricultural productivity in a country where agriculture employs 40% of the workforce. Glacier melt in the north creates water scarcity risks for irrigation-dependent farming. Extreme weather events—floods, droughts, heatwaves—are increasing in frequency and intensity.
The IMF’s Resilience and Sustainability Facility, providing $200 million in the latest disbursement, addresses this directly. But Pakistan needs far more comprehensive climate adaptation: improved water storage and irrigation systems, disaster-resilient infrastructure, agricultural diversification, and early warning systems. The World Bank estimates Pakistan requires $8-10 billion annually in climate adaptation investments through 2030.
Climate isn’t just an environmental issue—it’s a macroeconomic variable that can blow apart fiscal plans, devastate agricultural output, and trigger massive humanitarian emergencies requiring expensive relief. Any serious 2026 outlook must account for climate risk.
The Regional Context: Where Pakistan Stands
Pakistan doesn’t compete in isolation. Its South Asian neighbors offer instructive contrasts. India, despite comparable governance challenges, maintains 6-7% growth through a larger domestic market, more diversified economy, and deeper capital markets. Bangladesh, having graduated from least-developed status, sustains 5-6% growth driven by garment exports and steady policy continuity.
Even Sri Lanka, having endured debt default and political crisis in 2022, is stabilizing faster than expected. Its reform program, while painful, has restored some fiscal credibility and attracted investment interest.
Pakistan’s advantages are real: a large, young population; strategic location between South Asia, Central Asia, and the Middle East; reasonable infrastructure; and a substantial diaspora providing remittances and potential investment. Its disadvantages are equally real: political instability, security challenges, weak institutions, and policy inconsistency.
The critical question: can Pakistan leverage its advantages while addressing its weaknesses? Historical evidence suggests caution. Pakistan has squandered similar opportunities repeatedly. But circumstances have changed. The regional security environment has stabilized somewhat. China’s Belt and Road infrastructure provides connectivity options. Gulf states, particularly Saudi Arabia and UAE, show investment interest. Global firms seeking China+1 diversification could include Pakistan.
The window exists. Whether Pakistan can seize it depends on choices made in 2025-26.
What This Means for Stakeholders
For investors: Pakistan offers asymmetric opportunities with commensurate risks. The stock market’s 50%+ returns in 2025 reflect compressed valuations catching up to improved fundamentals. Banking, cement, energy, and consumer sectors show promise. But political and policy risks remain elevated. Diversification is essential. Consider Pakistan as a 5-10% portfolio allocation, not a concentrated bet.
For businesses: Pakistan’s 240 million person market and low per-capita income suggest massive consumption growth potential as incomes rise. But doing business requires patient capital, local partnerships, and willingness to navigate bureaucracy. Sectors with demonstrated success—textiles, IT services, food processing—offer proven paths. Emerging sectors like renewable energy, e-commerce, and fintech show potential but require regulatory navigation.
For policymakers: The 2025-26 period represents a narrow window for transformative reform. Stabilization creates space for politically difficult decisions—but that space won’t last forever. Prioritize revenue mobilization, energy sector restructuring, investment climate improvement, and export competitiveness. Most critically, build institutional capacity that outlasts any single government. Pakistan’s problem isn’t lack of plans—it’s lack of implementation and sustainability.
For citizens: Understand that stabilization isn’t prosperity. Demand more than fiscal metrics; demand job creation, service delivery, education access, and corruption accountability. Pakistan’s youth represent its greatest asset—but only if provided opportunities to contribute productively. Brain drain isn’t inevitable; it’s a policy choice reflecting failure to create domestic opportunity.
The Verdict: Cautious Optimism Grounded in Reality
So where does this leave Pakistan in 2025, looking toward 2026? In a place simultaneously better and more fragile than simple metrics suggest.
The stabilization is real. Pakistan has stepped back from the 2023 precipice. Reserves are rebuilding, inflation has declined, fiscal discipline has improved, and market confidence has partially returned. These aren’t trivial achievements—they required painful adjustment and represent genuine progress.
But stabilization isn’t transformation. Growth barely outpacing population expansion doesn’t create jobs at scale. Debt servicing consuming half the budget leaves no fiscal space for development. Foreign investment at 0.5% of GDP signals ongoing skepticism. Poverty affecting 45% of citizens demands far more aggressive inclusive growth.
The choice Pakistan faces isn’t between crisis and prosperity—it’s between muddling through and breakthrough. Muddling through means 3-3.5% growth indefinitely, stable but stagnant, avoiding disaster but not achieving potential. Breakthrough means accelerating to 5-6% sustained growth through genuine reform, creating millions of jobs, dramatically reducing poverty, and fulfilling Pakistan’s considerable potential.
Which path materializes depends on choices made in 2025-26. The external environment is reasonably favorable—global growth continues, commodity prices are manageable, Gulf investment interest exists, and IMF support provides buffer. The domestic environment is more uncertain—political stability is fragile, coalition dynamics complicate reform, and vested interests resist change.
History suggests skepticism. Pakistan has disappointed repeatedly, choosing expedience over reform, short-term survival over long-term strategy. But history also shows capacity for surprise. Pakistan has demonstrated resilience through extraordinary challenges. The question isn’t capability—it’s will.
For 2026, expect continued stabilization with modest growth acceleration if reforms progress. The base case of 3.2-3.5% growth, 5-6% inflation, $25-28 billion reserves, and gradual debt-to-GDP improvement is achievable and likely. Whether Pakistan breaks through to 5%+ sustained growth depends on policy courage—expanding the tax base, restructuring energy, improving business climate, and prioritizing exports.
The immediate crisis has passed. The chronic challenges remain. Pakistan’s economic outlook for 2025-26 is neither euphoric nor catastrophic—it’s cautiously optimistic, grounded in real progress but acutely aware of formidable obstacles ahead.
The country stands at a crossroads. One path leads to continued muddling—stable but mediocre, avoiding crisis but not achieving potential. The other leads to genuine transformation—politically difficult but economically transformative. Which path Pakistan takes will define not just 2026, but the trajectory of the next decade.
The data is mixed. The potential is real. The choice is Pakistan’s.
Sources Referenced:
- International Monetary Fund (IMF) reports and projections
- State Bank of Pakistan data
- World Bank Pakistan assessments
- Trading Economics statistical data
- Ministry of Finance debt sustainability analysis
- Pakistan Stock Exchange performance metrics
- Multiple authoritative economic research institutions


In under two years, the regulatory posture toward crypto in the United States has flipped from adversarial to explicitly promotional. What began as an executive order in January 2025 has cascaded into a stablecoin law, a coordinated SEC-CFTC framework, a five-category classification system for digital assets, and — as of this week — a genuine test of whether Congress can finish the job with comprehensive market-structure legislation. Here is the full architecture of Trump-era crypto policy as it stands in September 2026.
The Foundation: Executive Order 14178 and the White House Report
The administration’s crypto agenda traces back to Executive Order 14178, issued at the start of the second Trump term. On July 30, 2025, the President’s Working Group on Digital Asset Markets — established under that order — issued a comprehensive report titled “Strengthening American Leadership in Digital Financial Technology,” according to Practical Law’s coverage. That report became the blueprint both the SEC and CFTC would spend the next year implementing.
SEC’s “Project Crypto” and CFTC’s “Crypto Sprint”
Within 48 hours of the White House report’s release, both major regulators launched dedicated initiatives. SEC Chair Paul Atkins announced “Project Crypto” on July 31, 2025 — an agency-wide effort to implement the White House’s recommendations, with five stated priorities including, notably, “onshoring crypto to the US,” per Practical Law. Chair Atkins directed the SEC’s policy divisions to coordinate with the agency’s Crypto Task Force, led by Commissioner Hester Peirce, a longtime industry-friendly voice at the Commission.
The very next day, then-Acting CFTC Chair Caroline Pham launched a parallel “Crypto Sprint,” a 12-month initiative covering the listing of spot digital assets on CFTC-registered exchanges, allowing derivatives market participants to use tokenized collateral including stablecoins, and establishing a “CEO Innovation Council” of 12 exchange executives, according to K&L Gates. Within months, the CFTC confirmed spot digital assets were available for trading on a CFTC-registered exchange for the first time.
The GENIUS Act: America’s First Federal Stablecoin Law
The most concrete legislative achievement of the period has been the GENIUS Act, the first U.S. federal law specifically governing stablecoins. Its enactment triggered a wave of follow-on rulemaking: K&L Gates noted that the Treasury Department, the Office of the Comptroller of the Currency, and other federal banking agencies all opened rulemakings to implement the law during 2026. The GENIUS Act’s definition of “digital asset” has since become the template other agencies build from — the SEC’s own proposed crypto-asset offering rules explicitly mirror the GENIUS Act’s definitional language.
March 2026: The SEC-CFTC Coordination Breakthrough
The most significant structural shift arrived in March 2026. On March 11, SEC Chairman Paul Atkins and CFTC Chairman Michael Selig signed a Memorandum of Understanding to formally coordinate the two agencies’ historically overlapping and often conflicting jurisdiction over digital assets, according to Latham & Watkins’ policy tracker. The MOU commits both agencies to a “minimum effective dose” of regulation intended to promote innovation while still protecting market integrity.
Six days later, on March 17, 2026, the SEC and CFTC jointly published an interpretive release — their first major coordinated statement since the MOU — sorting digital assets into a five-category framework, according to Holland & Knight: digital commodities, digital collectibles, digital tools, payment stablecoins (aligned with the GENIUS Act definition), and a fifth category covering more traditional securities-like tokens. That classification system is now the reference point nearly every subsequent rulemaking builds from.
Trump-era crypto policy timeline:
| Date | Development | Body |
|---|---|---|
| Jan 2025 | Executive Order 14178 | White House |
| Jul 30, 2025 | Digital asset policy report | Presidential Working Group |
| Jul 31, 2025 | “Project Crypto” launched | SEC (Chair Atkins) |
| Aug 1, 2025 | “Crypto Sprint” launched | CFTC (Acting Chair Pham) |
| — 2025 | GENIUS Act enacted | Congress |
| Mar 11, 2026 | SEC-CFTC MOU signed | SEC + CFTC |
| Mar 17, 2026 | Five-bucket digital asset classification | SEC + CFTC joint release |
| Aug 2026 | “Regulation Crypto Assets” proposed | SEC |
| Sep 10, 2026 | Revised 630-page CLARITY Act released | Senate Republicans |
| Sep 15, 2026 | Procedural vote scheduled | U.S. Senate |
SEC Proposes “Regulation Crypto Assets”
In August 2026, the SEC moved from interpretation to formal rulemaking, proposing “Regulation Crypto Assets” — a bespoke offering regime specifically for crypto investment contracts. According to Sidley Austin’s analysis, Chairman Atkins said the proposed rules “draw heavily from Congressional work over recent years, particularly the CLARITY Act,” explicitly designing the rule to give the industry a regulatory head start pending final legislation. The proposal’s four-year window for a startup exemption mirrors the CLARITY Act’s own timeline for a token project to reach “mature blockchain system” status — a deliberate signal that the SEC expects the legislative and regulatory tracks to converge.
The Unfinished Business: CLARITY Act’s Uncertain Fate
Despite the extensive regulatory groundwork, the industry’s top legislative priority — the Digital Asset Market CLARITY Act, which would legislatively divide SEC/CFTC jurisdiction and create a comprehensive market-structure framework — remains unpassed as of this writing. The House passed its version, but the bill has stalled in the Senate, falling short of the 60 votes needed for passage, according to Holland & Knight.
Senate Republicans released a substantially revised, 630-page version of the bill on September 10, 2026, adding over 100 changes and specifically targeting “decentralized-in-name-only” protocols by requiring them to register with the CFTC, per Investing News Network. A pivotal procedural vote is scheduled for September 15, 2026, after the Senate returns from recess — but the bill already missed one legislative window in August, and CNBC reported that industry insiders, including SALT CEO John Darsie, remain skeptical of passage in 2026 given the difficulty of moving major legislation heading into midterm elections.
What Happens If CLARITY Fails
Crucially, the industry’s regulatory position does not collapse if CLARITY dies in the Senate. As CNBC’s reporting notes, “viewed from a narrow lens, the investment is already paying off, even if Clarity dies” — the SEC and CFTC have already built out much of the practical framework administratively through the MOU, the joint interpretive release, and the proposed Regulation Crypto Assets rule. Legislation would lock the framework into statute, providing durability against a future administration reversing course, but its absence would not undo the deregulatory shift already underway across every major digital-asset regulator, including the Office of the Comptroller of the Currency, which has also moved toward a looser supervisory framework for bank involvement in digital assets.
Final Verdict
The second Trump administration’s crypto policy has been unusually coordinated and fast-moving by regulatory standards: an executive order, a detailed policy report, twin agency initiatives, the first federal stablecoin law, an inter-agency MOU, a joint classification framework, and now a formal rulemaking — all within about 18 months. The remaining variable is whether Congress can convert that administrative groundwork into durable statute via the CLARITY Act, and the September 15 Senate vote is the clearest near-term test of that question. Either outcome, the substantive deregulatory shift toward “onshoring crypto to the US” is already largely in place at the regulatory level — legislation would cement it, not create it.
Barclays reported second-quarter income of £8.3 billion, up £1.2 billion from a year earlier, and upgraded its full-year 2026 income target even as operating expenses climbed 7% year-on-year — a mixed but ultimately reassuring signal for UK banking-sector health as the country navigates elevated gilt yields and a new premiership.
Income Growth Outpaces a Rise in Costs
Barclays reported second-quarter operating expenses of £4.5 billion, up 7% year-on-year, which the bank attributed to business growth, inflation, and increased investment spending, according to CNBC’s markets coverage. Despite the cost increase, income rose to £8.3 billion, and adjusted earnings per share beat Wall Street consensus, prompting shares to initially react positively before falling more than 7% amid broader market volatility on the results day.
Group Chief Executive C.S. Venkatakrishnan struck a confident tone on the outlook, saying the bank was upgrading its 2026 Group income target to approximately £31.5 billion and remained committed to delivering all financial and distribution targets through 2028, according to the same CNBC report.
Why the Results Matter Beyond Barclays
The results land at a delicate moment for UK financial markets more broadly. Ten-year gilt yields have been trading near 5% amid uncertainty over new Prime Minister Andy Burnham’s fiscal programme, while 30-year yields — sensitive to long-term fiscal credibility — have hovered near multi-year highs. A major UK bank posting income growth and raising its full-year guidance amid that backdrop offers a data point suggesting the underlying corporate and consumer credit environment remains healthier than the gilt market’s elevated risk pricing might suggest on its own.
Context: A Resilient Consumer Backdrop
Barclays’ results also arrive alongside broader UK data that has surprised to the upside. UK retail sales rose 1% in June against expectations for a 0.3% decline, while consumer confidence climbed to a six-month high in July, supported by warmer weather and a spending lift tied to the football World Cup — trends that plausibly support the credit and transaction-fee income underpinning Barclays’ income beat. Annual consumer price inflation, meanwhile, slowed to a 15-month low of 2.6% in June, giving the Bank of England room to hold interest rates steady at its policy meeting this week.
The Cost Pressure Story Isn’t Unique to Barclays
The 7% rise in Barclays’ operating expenses reflects a broader pattern across UK banking: inflation-driven wage costs, continued investment in technology and compliance infrastructure, and the general cost of doing business in a higher-rate environment. How rival UK lenders navigate the same pressures in their own upcoming results will be a key signal of whether Barclays’ income upgrade reflects bank-specific execution strength or a sector-wide tailwind from resilient consumer activity.
What to Watch
Barclays’ upgraded £31.5 billion income target sets a clear benchmark against which the rest of 2026 results will be measured, while the sustainability of the current cost growth rate — set against a Bank of England policy backdrop still calibrated around inflation risk — will determine whether margin expansion continues into 2027. Investors will also be watching how the bank’s guidance holds up if gilt-market volatility around the new government’s fiscal plans intensifies.
Dubai has climbed to its highest position ever on one of finance’s most closely watched rankings, and the achievement is no accident — it is the direct output of a decade-long, numerically explicit government strategy that few other financial centres have attempted to execute with this level of precision.
The Ranking Itself
The Dubai International Financial Centre has recorded its highest-ever position on the Global Financial Centres Index at seventh place worldwide, the highest ranking ever achieved by any financial centre across the Middle East, Africa and South Asia region, and the only MEASA-region centre to feature in the global top 20 — underscoring both its regional dominance and genuine global competitiveness.
The D33 Strategy Behind the Number
The ranking is explicitly tied to Dubai’s own stated ambitions. The GFCI result is described as pivotal to Dubai’s goal of becoming one of the world’s top four financial centres by 2033, in line with the Dubai Economic Agenda, or D33, which targets a doubling of the emirate’s economy over the decade. Separately, Dubai Chambers has confirmed the plan targets cumulative economic output of AED 32 trillion, or roughly $8.7 trillion, over the decade, supported by 100 transformative projects centred on trade expansion, digital innovation and sustainable growth.
The Underlying Economic Engine
The financial-centre ambitions are backed by genuine current-quarter growth. Dubai’s economy reached AED 232 billion in first-quarter 2026 GDP, a 2.4 percent year-on-year increase, with the finance, construction, healthcare, wholesale and retail trade, and real estate sectors all contributing to the broad-based expansion. Middle East Briefing separately projects the wider UAE economy will expand around 5 percent in 2026, with local banks positioned to increase lending both domestically — supporting SMEs, consumers and project finance — and across borders into markets like Saudi Arabia, where UAE banks’ comparatively lower interbank rates create an arbitrage opportunity.
Real Money Behind the Ranking
The GFCI climb is being validated by tangible transaction volume rather than sentiment alone. Weekly UAE business tracking shows a steady drumbeat of institutional activity: Sharjah Islamic Bank reported AED 803.9 million in net profit, up 15.3 percent, ADI Chain secured a $50 million investment to build sovereign digital infrastructure, and Capital.com reported $1.1 trillion in second-quarter trading volume routed through the jurisdiction. Separately, UAE and Saudi banks are projected to lead GCC credit growth in 2026, reinforcing Dubai and Abu Dhabi’s combined position as the region’s default financial gateway.
Why This Matters for Pakistan and South Asia
Dubai’s ascent as a financial hub carries direct relevance for Pakistan, where — as detailed in our companion coverage of Pakistan’s remittance exposure — roughly 55 percent of the country’s substantial remittance inflows originate from the Gulf Cooperation Council. A deepening, increasingly sophisticated DIFC-anchored financial ecosystem in Dubai means more efficient, lower-cost channels for that capital, alongside growing opportunities for Pakistani and South Asian firms to access GCC-sourced project finance and cross-border credit as UAE banks expand lending beyond their domestic market.
What is Dubai’s global financial centre ranking in 2026?
Dubai’s DIFC recorded its highest-ever ranking on the Global Financial Centres Index at 7th place worldwide in 2026 — the highest ever achieved by any Middle East, Africa or South Asia financial centre — as part of its stated goal to become a top-four global financial hub by 2033.
The Risk Beneath the Growth Story
Not every signal points to unambiguous strength. AGBI’s own reporting notes that UAE banks’ second-quarter results are likely to show weaker profits, slower lending and narrower margins, even as analysts characterise the underlying sector as fundamentally resilient — a reminder that Dubai’s financial-hub ambitions are being pursued against a genuinely more difficult regional operating environment shaped by the Strait of Hormuz disruption and broader Gulf security concerns, not in isolation from them.
The Bottom Line
Dubai’s climb to seventh in the GFCI rankings is less a one-off achievement than a measurable checkpoint on an explicitly numbered, decade-long strategic roadmap — one increasingly backed by real GDP growth, credit expansion, and institutional trading volume rather than ambition alone.

Diesel Prices 2026–2027: Why Cheaper Crude May Not Mean Cheap Fuel

2027 Social Security COLA: Key Details and Dates

KSE-100 Sees Major Drop Post-SBP Rate Hike

Big Tech’s AI Spending Test: Can Revenue Catch Up With Capital Expenditure?

AI Infrastructure Investment Strategies for 2026

Pakistan Freelancers Tax 2026: Payments, Documentation and Formal Growth

Strait of Hormuz Crisis: What the Latest Tanker Attacks Mean for Oil, Shipping and Global Trade

AI Customer Service in 2026: What’s Working, What’s Failing, and What to Buy

Open a Savings Account Online: How to Actually Earn 10x the National Average Rate

Global Housing Market 2026: Where Prices Rise, Where They Don’t

PSX and KSE-100 Record Highs: An Insider’s Guide to Pakistan Stocks

So Delicious Dessert Recall: Affected Products, FDA Guidelines, and Consumer Action

Pakistan’s Current Account Deficit Narrows Sharply to $98 Million in August 2026

Japan Eyes 3.5% Defense Spending: What It Means for Bonds, Stocks, and the BOJ

Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities

Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World

Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns

China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech

What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact

15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025

How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide

Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide

Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
-
 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
 Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
 Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
 Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
 AI11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
 Exports11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
Pingback: Pakistan's Startup Revival: How Hybrid Financing Drove a $74 Million Surge in 2025 - The Economy
Pingback: K-Electric Tariff Cut Sparks $2B Arbitration Crisis - The Economy