
Banks
Trump’s Fed Pick Signals Institutional Reckoning

Kevin Warsh’s nomination as chair could spark sweeping changes to the central bank—if he can navigate the political gauntlet ahead
President Donald Trump nominated Kevin Warsh as the next Federal Reserve chair on January 30, ending months of speculation and launching what promises to be one of the most consequential leadership transitions in the central bank’s modern history. The choice of Warsh, a former Fed governor who has publicly called for “regime change” at the institution, signals an impending reconsideration of the Fed’s expanded mandate and operational independence—even as markets rallied on relief that Trump selected a relatively orthodox candidate over potentially more pliable alternatives.
The announcement, delivered via Truth Social with characteristic Trumpian superlatives, positions Warsh to succeed Jerome Powell when his term expires in May. Yet beneath the market’s initial sigh of relief—the dollar surged nearly one percent while gold plummeted almost five percent—lies a more complex and potentially destabilizing dynamic. Warsh arrives at the Fed not as a continuity candidate but as an avowed critic who has spent years arguing that the institution has strayed dangerously from its core mission, expanded its balance sheet recklessly, and lost the credibility necessary to anchor inflation expectations.
“The credibility deficit lies with the incumbents that are at the Fed, in my view,” Warsh declared during a CNBC interview last July, using language rarely directed at the central bank by prospective chairs. This forthright assessment of the institution he now seeks to lead encapsulates the tension at the heart of his nomination: Warsh brings impeccable credentials and crisis-tested experience from his 2006-2011 tenure as a Fed governor during the global financial meltdown, yet he returns as something closer to a reformer than a steward.
The case for overhaul
Warsh’s critique of the Federal Reserve extends well beyond the tactical disagreements over interest rate policy that typically animate debates about monetary management. Instead, he has articulated a fundamental challenge to what he characterizes as “mission creep”—the Fed’s gradual expansion into climate risk assessment, diversity initiatives, and an arsenal of unconventional policy tools that, in his view, have politicized the institution and undermined its independence.
During an April lecture hosted by the Group of Thirty, Warsh argued that “the Fed’s current wounds are largely self-inflicted.” His prescription involves what he has termed a new “Treasury-Fed accord,” invoking the 1951 agreement that liberated the central bank from its obligation to support government bond prices. Such an accord, Warsh contends, would establish clearer boundaries around the Fed’s balance sheet management and restore a division of labor between monetary and fiscal authorities that has eroded over successive crises.
The intellectual coherence of Warsh’s position stands in stark contrast to the political pressures that brought him to this juncture. Trump has berated Powell relentlessly for maintaining rates he considers excessively restrictive, demanded cuts to levels historically associated with economic distress, and even launched a Justice Department criminal investigation into the Fed chair over renovation cost overruns—an episode that shocked senators from both parties and raised profound questions about central bank independence. Trump praised Warsh effusively, predicting he would “go down as one of the GREAT Fed Chairmen, maybe the best,” yet this endorsement comes freighted with expectations that may prove incompatible with the institutional reforms Warsh has long advocated.
The paradox of the hawk turned dove
Warsh built his reputation during his first Fed stint as an inflation hawk who frequently warned of price pressures that never materialized. During the recovery from the 2008 crisis, when unemployment hovered near ten percent, he persistently cautioned about upside inflation risks—a position that, in retrospect, appears to have unnecessarily constrained the Fed’s support for a struggling economy. This history makes his recent evolution toward endorsing rate cuts all the more noteworthy, and potentially suspect.
The transformation appears rooted in Warsh’s conviction that artificial intelligence and deregulation are ushering in a productivity renaissance that will allow faster growth without inflation—a thesis he outlined in a January 2025 Wall Street Journal column arguing that “the Trump administration’s strong deregulatory policies, if implemented, would be disinflationary” and that cuts in government spending would further reduce price pressures. This theoretical framework conveniently aligns with Trump’s political imperatives, raising questions about whether Warsh’s intellectual journey reflects genuine economic analysis or strategic positioning for the role he now seeks.
Markets appear uncertain how to reconcile these competing signals. As reported by Bloomberg, the dollar and short-dated Treasuries rallied on relief that Trump selected Warsh “rather than someone seen as more willing to ignore inflation and slash interest rates,” yet analysts remain skeptical about his newfound accommodation. Deutsche Bank analysts suggested they “do not view him as structurally dovish” despite his recent rhetoric, while University of Michigan economist Justin Wolfers noted that Warsh’s hawkish record represents “exactly not who the president wants,” raising concerns that “deals were made.”
The confirmation crucible
Even assuming Warsh’s nomination survives the Senate Banking Committee—itself far from assured—he faces structural constraints that may frustrate both his reformist ambitions and Trump’s demand for aggressive rate cuts. Interest rate decisions are made not by the chair alone but by the twelve-member Federal Open Market Committee, which includes seven governors and five rotating regional bank presidents. As the Council on Foreign Relations observed, “while the chair presides over the committee, he cannot dictate policy without securing the support of a majority of its members.”
Current committee members have shown little appetite for the dramatic easing Trump envisions. The Fed’s December projections indicated just one quarter-point cut expected in 2026, with policymakers citing inflation that remains stubbornly above the two percent target at 2.7 percent. Warsh would need to build consensus among colleagues, some of whom may view his appointment as a politicization of the central bank, at precisely the moment when his patron demands results that economic conditions may not justify.
The confirmation process itself has become unexpectedly treacherous. Senator Thom Tillis of North Carolina, a crucial Republican vote on the narrowly divided Banking Committee, has vowed to oppose any Fed nominee until the Justice Department probe of Powell is resolved—a probe widely viewed as political retaliation. As NBC News reported, Senate Majority Leader John Thune acknowledged that without Tillis’s support, Warsh could “probably not” win confirmation. Democratic senators, meanwhile, have denounced the nomination as fundamentally compromised, with Senator Elizabeth Warren calling on Republicans to block the pick unless Trump ends his “witch hunts” against Powell and Governor Lisa Cook.
Global reverberations
The implications extend well beyond domestic monetary policy. Warsh’s potential chairmanship arrives at a moment of extraordinary fragility in the international financial architecture. Trump’s erratic foreign policy—including threats against Greenland and sweeping tariff proposals—has already undermined confidence in American institutions. The spectacle of a president openly attempting to bend the Fed to his will, backed by criminal investigations and threats to fire sitting governors, has sent a chilling message to central bankers and finance ministers worldwide about the durability of American commitment to rules-based governance.
Atlantic Council experts noted that “if Warsh wants to cement the Fed’s standing, he will need to act—and be seen to act—as an independent guardian of price stability and full employment.” Yet achieving this will require navigating between Trump’s demands for accommodation and the Fed’s institutional imperative to maintain credibility. The risk is that Warsh becomes neither effective reformer nor trusted independent actor, but rather a chair whose every decision is scrutinized for evidence of political influence—a dynamic that could prove far more corrosive to Fed independence than any specific policy choice.
Markets have begun pricing in these uncertainties. The initial relief that greeted Warsh’s selection has given way to more sober assessments as investors contemplate the path ahead. According to CNBC, precious metals experienced historic volatility, with silver plunging thirty percent in its worst day since 1980—a dramatic unwinding of positions that had accumulated amid fears of Fed politicization and dollar debasement. This suggests markets are betting that Warsh will prove more institutionally conservative than feared, yet they remain vigilant for signs that political pressures will overwhelm technocratic judgment.
The productivity wager
At the core of Warsh’s intellectual framework lies a bet on supply-side transformation. He contends that artificial intelligence, deregulation, and efficiency gains can deliver the holy grail of economic policy: robust growth with subdued inflation. If correct, this would allow the Fed to cut rates while maintaining price stability, satisfying Trump’s political demands without sacrificing the institution’s credibility.
Yet this argument confronts considerable skepticism. The promised productivity boom from previous technological revolutions—personal computers, the internet, mobile computing—took years to materialize in aggregate statistics, and often arrived alongside disruptive transitions that central banks struggled to navigate. Warsh has criticized the Fed’s “bloated balance sheet” and called for significant reductions as reported by Yahoo Finance, but shrinking the balance sheet while simultaneously cutting rates presents technical and communications challenges that could roil markets accustomed to the Powell Fed’s cautious incrementalism.
Moreover, the productivity thesis serves conveniently to reconcile Warsh’s hawkish past with his dovish present, raising questions about whether it represents rigorous analysis or motivated reasoning. If inflation proves more persistent than his framework suggests—whether due to Trump’s tariffs, immigration restrictions, or other supply constraints—Warsh will face an excruciating choice between vindicating his intellectual evolution by staying accommodative or reverting to his inflation-fighting instincts and incurring presidential wrath.
Powell’s shadow
One factor that may complicate Warsh’s transition has received insufficient attention: Jerome Powell could choose to remain on the Board of Governors even after his chairmanship expires. While most chairs have resigned entirely upon losing their leadership role, Powell’s term as a governor extends until early 2028, and there are indications he may stay to serve as a counterweight to political pressure.
Such a scenario would present Warsh with a formidable challenge. Powell commands enormous respect within the institution and global financial community, having navigated the pandemic recession, the subsequent inflation surge, and now Trump’s unprecedented assault on Fed independence with a calm determination that has largely maintained market confidence. His presence on the board as a voting member would serve as a constant reminder of alternative approaches and potentially rally committee members resistant to Warsh’s reforms or susceptible to presidential pressure.
The way forward
Kevin Warsh’s nomination represents a pivotal moment for American economic governance. His potential chairmanship could catalyze an overdue reckoning with the Fed’s expanded mandate, bloated balance sheet, and tendency toward what he views as technocratic overreach. Alternatively, it could mark the beginning of a more politically pliable central bank that subordinates rigorous economic analysis to executive branch preferences—precisely the outcome that central bank independence was designed to prevent.
The most likely path lies somewhere between these extremes. Warsh possesses the credentials and crisis experience to command respect, the intellectual framework to justify policy choices that may diverge from both Trump’s demands and the Powell Fed’s approach, and sufficient political acumen to navigate the treacherous confirmation process ahead. Yet he assumes office at a moment when the Fed’s independence has never been more contested, when inflation remains above target despite three rate cuts, when fiscal deficits are expanding rapidly, and when global economic conditions remain volatile and uncertain.
The ultimate test will be whether Warsh can execute his vision of Fed reform while maintaining the institution’s credibility and independence—or whether the political circumstances of his appointment will overwhelm his reformist intentions, leaving the Federal Reserve neither fish nor fowl but rather an institution fundamentally changed in ways that undermine its effectiveness. For investors, policymakers, and citizens navigating an increasingly uncertain economic landscape, the answer to this question will shape not just interest rates and inflation outcomes, but the very architecture of American economic governance for decades to come.
As markets digest the Warsh nomination and prepare for his confirmation hearings in the spring, one reality has become clear: the Powell era’s studied pragmatism and consensus-driven incrementalism is ending. What replaces it—whether constructive reform or corrosive politicization—remains the most consequential economic policy question of 2026.


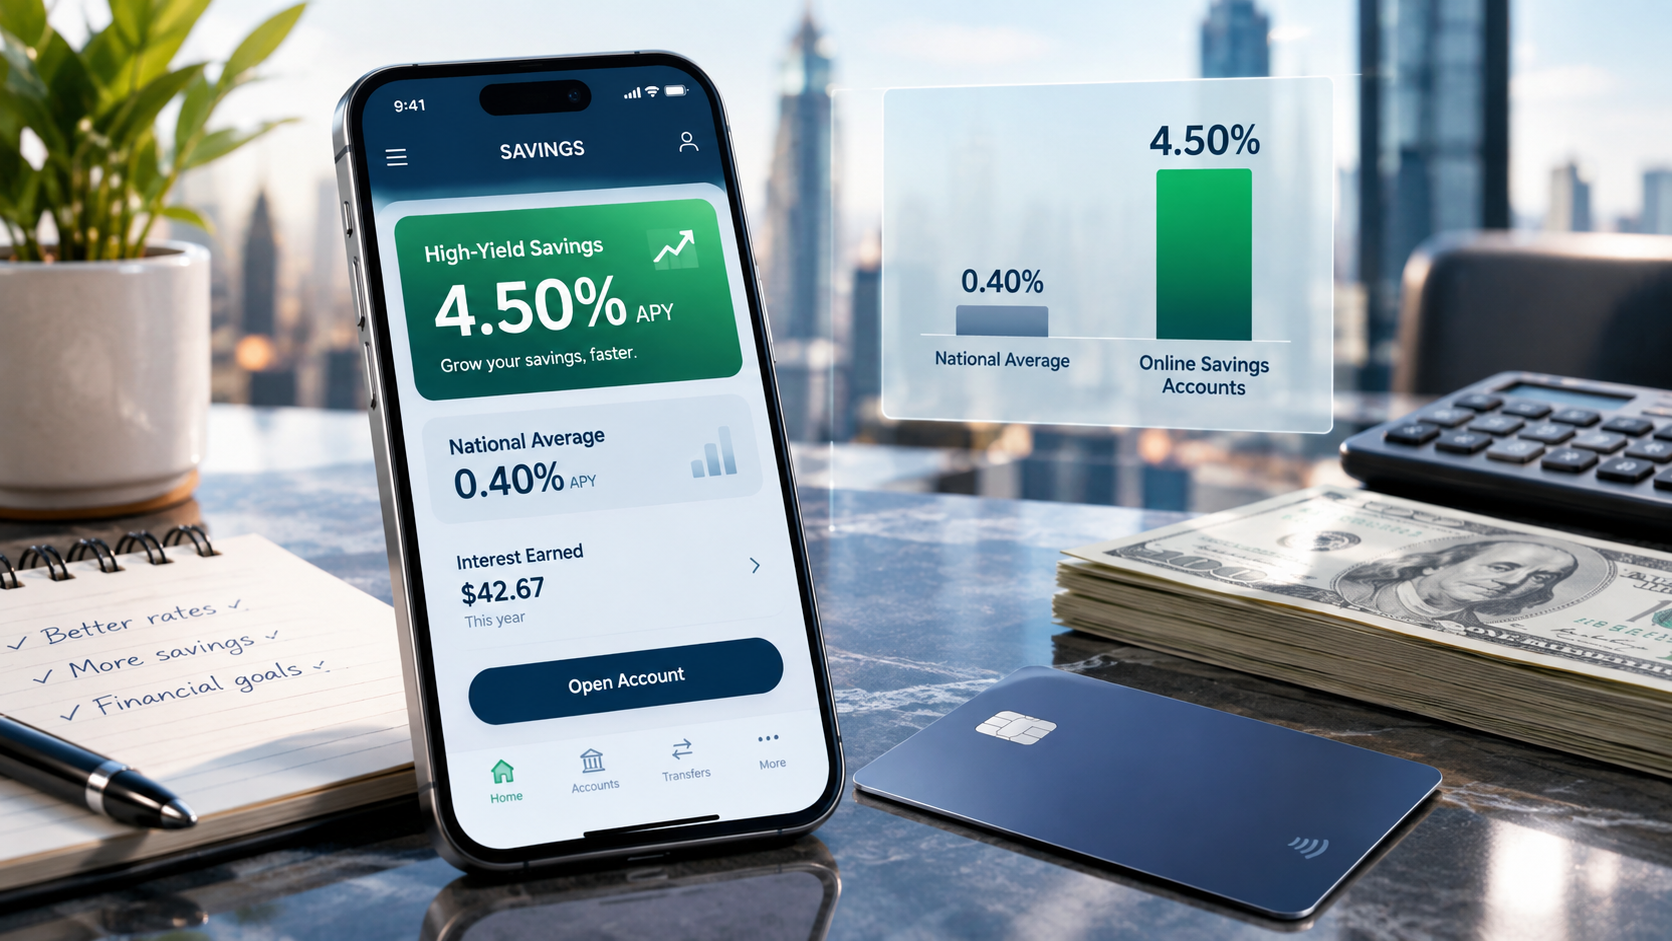
The national average savings account rate sits at roughly 0.38%–0.45% APY, while top online high-yield savings accounts pay upward of 4%–4.70% APY — meaning the bank you choose, not just how much you save, can be the single biggest factor in your interest earnings.
Opening a savings account online has become the default choice for rate-conscious savers, since digital-only banks and online divisions of traditional banks consistently outpace brick-and-mortar savings rates by a wide margin. But comparing accounts requires looking past the advertised headline rate to understand balance tiers, promotional periods, and what happens to your rate after an introductory offer ends.
This guide explains how online savings accounts actually work, what drives the rate you’ll really earn, and how to choose between the many competing options.
How Online Savings Accounts Work
Online banks can typically offer higher rates than traditional brick-and-mortar banks because they carry lower overhead — no branch network to maintain — and pass some of that savings on to depositors in the form of better APY.
Key takeaway: The national average savings account rate is approximately 0.38%–0.45% APY, while top online high-yield savings accounts regularly offer 4.00%–4.70% APY — roughly ten times the national average. On a $10,000 balance, that difference amounts to hundreds of dollars in additional interest per year with zero additional risk.
What to Check Before Opening an Account
- APY (Annual Percentage Yield) — the actual compounded return you’ll earn, not to be confused with a simple interest rate.
- Minimum balance to earn the advertised APY — some accounts pay the top rate only above a certain balance, with a much lower rate below it.
- Minimum opening deposit — ranges from $0 to $500 or more depending on the institution.
- FDIC or NCUA insurance — standard coverage protects deposits up to $250,000 per depositor, per institution, per ownership category.
- Whether the rate is promotional or ongoing — some “welcome” APYs apply only for a limited introductory period before reverting to a lower standard rate.
- Withdrawal limitations — some accounts retain federal transaction limits or impose their own monthly withdrawal caps.
Step-by-Step: Opening a Savings Account Online
- Compare APY, fees, and minimum balance requirements across several online banks rather than defaulting to your existing checking account’s bank.
- Complete the online application — typically name, address, Social Security number, and identity verification.
- Link a funding source — an existing bank account, debit card, or mailed check, depending on the provider.
- Fund the account — minimum opening deposits are commonly $0 to $50 for online-only high-yield accounts, though some require more.
- Set up automatic transfers, if desired, to build consistent savings habits without manual deposits.
- Monitor the rate periodically — since APYs on high-yield accounts are variable and can change based on broader interest rate movements.
Financial and Strategic Implications: What Your Rate Actually Earns You
The gap between average and top-tier rates compounds meaningfully over time, particularly for larger balances or longer savings horizons.
| Savings Scenario | At National Average (~0.40% APY) | At High-Yield Rate (~4.50% APY) |
|---|---|---|
| $5,000 balance, 1 year | ~$20 interest | ~$225 interest |
| $10,000 balance, 1 year | ~$40 interest | ~$450 interest |
| $25,000 balance, 1 year | ~$100 interest | ~$1,125 interest |
| $10,000 balance, 5 years (compounded) | ~$202 total interest | ~$2,461 total interest |
Expert insight: FDIC insurance protects deposits up to $250,000 per depositor, per insured bank, per ownership category — meaning a saver with more than $250,000 in cash should consider splitting funds across multiple FDIC-insured institutions, or using accounts with expanded coverage structures, to ensure full protection.
Watch for Rate Cliffs and Tiered Balances
Some accounts advertise an attractive headline APY that only applies below a certain balance threshold or above a specific minimum — with a meaningfully lower rate applying outside that band. Always check the full rate schedule, not just the number in the advertisement, since the effective blended rate on your actual balance can be lower than the headline figure suggests.
Promotional Rates vs. Standing Rates
A number of online banks offer an elevated introductory APY for new customers for a limited window (commonly 3 months), after which the rate reverts to the bank’s standard ongoing rate. This can still be worthwhile for short-term savings goals, but shouldn’t be confused with the account’s long-term earning rate when comparing options for a multi-year savings strategy.
How to Choose the Right Online Savings Account
- Compare the ongoing rate, not just the promotional rate — a lower “everyday” APY may still beat a competitor’s post-promotion rate.
- Confirm there’s no monthly maintenance fee, or that any fee is easily waived, since a fee can offset meaningful interest earnings on smaller balances.
- Check transfer speed to and from linked accounts — since online-only banks rely on electronic transfers, which can take one to three business days depending on the institution.
- Verify FDIC or NCUA insurance explicitly before depositing significant funds.
- Consider a cash management account as an alternative if you want features like debit card access alongside a competitive yield, since some non-bank cash management accounts offer similar or higher rates with added flexibility.
- Match the account structure to your goal — a basic high-yield savings account suits an emergency fund, while a CD may suit money you won’t need for a fixed period, often at a comparably competitive or higher rate.
Key takeaway: The single most impactful decision most savers make isn’t picking the absolute highest APY on a comparison table — it’s simply moving money out of a near-zero-interest traditional savings account at all, since even a “merely good” online rate typically represents a 5–10x improvement over the national average.
Future Outlook: Savings Rate Trends Through 2027
- Online savings rates remain closely tied to broader interest rate policy. As monetary policy shifts, high-yield savings APYs typically move in the same direction with a short lag, meaning current top rates are not guaranteed to persist indefinitely.
- Competition among online banks and fintech platforms continues to compress the rate-comparison gap. New entrants regularly launch promotional rates to attract deposits, rewarding savers who periodically re-shop rather than staying with the same account indefinitely.
- Cash management accounts are increasingly competing directly with traditional savings accounts. Several non-bank financial platforms now offer FDIC-insured cash accounts with yields competitive with — or exceeding — dedicated high-yield savings products, often with additional liquidity features.
- Inflation-adjusted “real return” awareness is growing among savers. As savers increasingly compare APY against inflation expectations rather than viewing it in isolation, the gap between a merely adequate rate and a genuinely strong rate is becoming a more prominent part of account-selection decisions.
Frequently Asked Questions
What’s a good APY for an online savings account right now?
Top online high-yield savings accounts commonly offer APYs in the 4.00%–4.70% range, substantially above the national average of roughly 0.38%–0.45%.
Is an online savings account as safe as a traditional bank savings account?
Yes, as long as the institution is FDIC-insured (or NCUA-insured for credit unions), your deposits receive the same $250,000 per-depositor protection regardless of whether the bank has physical branches.
Do I need a minimum balance to open a savings account online?
It varies by institution — many online banks allow you to open an account with $0 to $50, while some require a larger minimum deposit, commonly in the $100–$500 range.
Will my online savings account rate stay the same over time?
Not necessarily. High-yield savings APYs are variable and generally move with broader interest rate conditions, and some accounts feature limited-time promotional rates that revert to a lower standard rate after an introductory period.
Can I have more than one online savings account?
Yes, and many savers deliberately do — both to compare rates across institutions and to spread balances above $250,000 across multiple FDIC-insured banks for full deposit insurance coverage.
Danone recalled So Delicious Salted Caramel Cluster pints on Sept 15, 2026. Check UPC 744473476138 and best-by dates on or before April 3, 2028.
- Danone USA issued a voluntary recall on 15 September 2026 of So Delicious Dairy Free Salted Caramel Cluster Non-Dairy Frozen Dessert pints, posted by the FDA.
- The reason: potential presence of foreign materials, such as small stones and other hard objects, within the cashew inclusions.
- Affected product: SKU 136603, UPC 744473476138, best-by dates on and before 3 April 2028. Pints with a later best-by date are not affected.
- No other So Delicious flavours, codes or products are involved. Distribution was nationwide to US retail stores.
- This is the second such recall in under a year — an identical issue prompted a December 2025 recall of the same product.
1. Introduction & Immediate Context
If you have a pint of So Delicious Dairy Free Salted Caramel Cluster in your freezer, check it before reading anything else.
Danone USA is recalling So Delicious Dairy Free Salted Caramel Cluster Non-Dairy Frozen Dessert pints with best-by dates on and before 3 April 2028 due to the potential presence of foreign materials, such as small stones and other hard objects, within the cashew inclusions, according to the company announcement posted by the FDA on 15 September 2026. The issue was identified through consumer complaints, and the FDA has been informed of the voluntary recall.
Danone is working with retail partners to remove affected product from shelves. Unaffected product remains available, and product shipped going forward is not affected.
2. Instant Product-Matching Table
Check all three fields. Flavour name alone is not sufficient, because packaging varies by retailer and the brand rebranded during 2026.
| Field | What to look for | Where to find it |
|---|---|---|
| Product name | So Delicious Dairy Free® Salted Caramel Cluster Non-Dairy Frozen Dessert (pints) | Front label |
| SKU | 136603 | Product listing / retailer receipt |
| UPC | 744473476138 | Back of container |
| Best-by date | On and before 3 April 2028 | Bottom of container |
| Package size | Pint | — |
| Distribution | Nationwide, US retail stores | — |
If all fields match: do not consume the product.
For a refund or replacement coupon: contact the So Delicious Dairy Free Consumer Care Line at 1-833-367-8975, available Monday to Friday, 9 a.m. to 6 p.m. ET.
If your best-by date falls after 3 April 2028: your pint is not part of this recall.
2.1 Comparison with the December 2025 recall
Households that checked their freezers last winter should check again — the date ranges are different.
| Recall | Date issued | Best-by range affected | SKU / UPC | Status |
|---|---|---|---|---|
| December 2025 | 15 December 2025 | Before 08 Aug 2027 | 136603 / 744473476138 | Completed; FDA terminated |
| September 2026 | 15 September 2026 | On and before 3 April 2028 | 136603 / 744473476138 | Active |
The September 2026 range extends roughly eight months beyond the earlier one. Product that passed the December check may still fall inside the current recall.
3. Structural Drivers and Competitor Gaps: Why Twice?
Almost all coverage of this recall stops at the checklist. The pattern is the more useful part of the story.
The stated cause is word-for-word identical to the December 2025 recall — foreign materials such as small stones and hard objects within cashew inclusions — as Fast Company noted in observing that this is now a pattern rather than an isolated incident. The company’s public language has also closely mirrored its statements from the previous year, including the assurance that the issue has been identified and corrected.
The mechanism points upstream. Small stones in cashew inclusions is a raw-material sorting failure, not a manufacturing-line failure. Tree nuts are harvested from the ground or from drying floors, and the standard controls are optical sorting, density separation and metal or X-ray detection at intake. Stones are specifically the contaminant these systems exist to catch, and they are difficult for downstream detection to find because their density can be close to that of the nut itself. A recurrence of the same contaminant in the same inclusion implies the corrective action taken after December 2025 did not resolve the root cause — most plausibly at a supplier or sorting-specification level rather than at the plant.
The recall also reached other jurisdictions. The Canadian Food Inspection Agency issued a Class 2 recall for a related So Delicious Dairy Free cashew-base salted caramel product over plastic-like and gravel-like fragments, indicating a supply-chain rather than single-facility scope.
There are no confirmed injury reports in the current recall documentation, and the FDA categorises this as a consumer-level alert. Foreign-object recalls carry dental-fracture and choking risk rather than illness risk, which is why the guidance is disposal rather than medical monitoring.
4. Key Implications for Stakeholders
Consumers with dietary restrictions. Dairy-free frozen dessert buyers often have limited substitutes, and repeat recalls in a narrow category are disproportionately disruptive. Only this single flavour is affected; other So Delicious products remain unaffected in both recalls.
Allergy-tracking households. Note that this is a foreign-object recall, not an allergen recall. No undeclared allergen is involved, so the standard cross-contamination protocols do not apply here — physical inspection and disposal do.
Retailers. The overlapping date ranges across two recalls create genuine shelf-audit complexity. Scanning by UPC alone will flag unaffected stock; the best-by date is the discriminating field.
Food safety professionals. A repeat of an identical contaminant within nine months is the type of event that typically attracts closer FDA attention to the corrective-action plan filed after the first recall.
How to verify anything you read about this. The FDA recalls, market withdrawals and safety alerts database is updated continuously and is the authoritative source. Secondary coverage has circulated conflicting date ranges by mixing the 2025 and 2026 notices.
5. Frequently Asked Questions
Q1: Which So Delicious products are recalled?
Only So Delicious Dairy Free Salted Caramel Cluster Non-Dairy Frozen Dessert pints with SKU 136603, UPC 744473476138 and a best-by date on or before 3 April 2028. No other flavours, codes or products from the brand are involved.
Q2: What should I do if I have the recalled product?
Do not eat it. Dispose of it and contact the So Delicious Dairy Free Consumer Care Line at 1-833-367-8975, open Monday to Friday, 9 a.m. to 6 p.m. ET, for a refund or replacement coupon.
Q3: Why was So Delicious recalled?
Because of the potential presence of foreign materials such as small stones and other hard objects within the cashew inclusions. The issue was identified through consumer complaints, and the FDA was informed of the voluntary recall.
Q4: Is this the same as the previous So Delicious recall?
It is the same product and the same stated cause, but a different date range. The December 2025 recall covered best-by dates before 8 August 2027 and has been terminated; the September 2026 recall covers dates on and before 3 April 2028.
Q5: Has anyone been hurt?
No confirmed injury reports appear in the current recall documentation. The FDA has categorised the action as a consumer-level alert.
Barclays reported second-quarter income of £8.3 billion, up £1.2 billion from a year earlier, and upgraded its full-year 2026 income target even as operating expenses climbed 7% year-on-year — a mixed but ultimately reassuring signal for UK banking-sector health as the country navigates elevated gilt yields and a new premiership.
Income Growth Outpaces a Rise in Costs
Barclays reported second-quarter operating expenses of £4.5 billion, up 7% year-on-year, which the bank attributed to business growth, inflation, and increased investment spending, according to CNBC’s markets coverage. Despite the cost increase, income rose to £8.3 billion, and adjusted earnings per share beat Wall Street consensus, prompting shares to initially react positively before falling more than 7% amid broader market volatility on the results day.
Group Chief Executive C.S. Venkatakrishnan struck a confident tone on the outlook, saying the bank was upgrading its 2026 Group income target to approximately £31.5 billion and remained committed to delivering all financial and distribution targets through 2028, according to the same CNBC report.
Why the Results Matter Beyond Barclays
The results land at a delicate moment for UK financial markets more broadly. Ten-year gilt yields have been trading near 5% amid uncertainty over new Prime Minister Andy Burnham’s fiscal programme, while 30-year yields — sensitive to long-term fiscal credibility — have hovered near multi-year highs. A major UK bank posting income growth and raising its full-year guidance amid that backdrop offers a data point suggesting the underlying corporate and consumer credit environment remains healthier than the gilt market’s elevated risk pricing might suggest on its own.
Context: A Resilient Consumer Backdrop
Barclays’ results also arrive alongside broader UK data that has surprised to the upside. UK retail sales rose 1% in June against expectations for a 0.3% decline, while consumer confidence climbed to a six-month high in July, supported by warmer weather and a spending lift tied to the football World Cup — trends that plausibly support the credit and transaction-fee income underpinning Barclays’ income beat. Annual consumer price inflation, meanwhile, slowed to a 15-month low of 2.6% in June, giving the Bank of England room to hold interest rates steady at its policy meeting this week.
The Cost Pressure Story Isn’t Unique to Barclays
The 7% rise in Barclays’ operating expenses reflects a broader pattern across UK banking: inflation-driven wage costs, continued investment in technology and compliance infrastructure, and the general cost of doing business in a higher-rate environment. How rival UK lenders navigate the same pressures in their own upcoming results will be a key signal of whether Barclays’ income upgrade reflects bank-specific execution strength or a sector-wide tailwind from resilient consumer activity.
What to Watch
Barclays’ upgraded £31.5 billion income target sets a clear benchmark against which the rest of 2026 results will be measured, while the sustainability of the current cost growth rate — set against a Bank of England policy backdrop still calibrated around inflation risk — will determine whether margin expansion continues into 2027. Investors will also be watching how the bank’s guidance holds up if gilt-market volatility around the new government’s fiscal plans intensifies.

Diesel Prices 2026–2027: Why Cheaper Crude May Not Mean Cheap Fuel

2027 Social Security COLA: Key Details and Dates

KSE-100 Sees Major Drop Post-SBP Rate Hike

Big Tech’s AI Spending Test: Can Revenue Catch Up With Capital Expenditure?

AI Infrastructure Investment Strategies for 2026

Pakistan Freelancers Tax 2026: Payments, Documentation and Formal Growth

Strait of Hormuz Crisis: What the Latest Tanker Attacks Mean for Oil, Shipping and Global Trade

AI Customer Service in 2026: What’s Working, What’s Failing, and What to Buy

Open a Savings Account Online: How to Actually Earn 10x the National Average Rate

Global Housing Market 2026: Where Prices Rise, Where They Don’t

PSX and KSE-100 Record Highs: An Insider’s Guide to Pakistan Stocks

So Delicious Dessert Recall: Affected Products, FDA Guidelines, and Consumer Action

Pakistan’s Current Account Deficit Narrows Sharply to $98 Million in August 2026

Japan Eyes 3.5% Defense Spending: What It Means for Bonds, Stocks, and the BOJ

Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities

Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World

Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns

China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech

What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact

15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025

How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide

Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide

Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
-
 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
 Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
 Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
 Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
 AI11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
 Exports11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025