
Global Finance
Federal Constitutional Court upholds Super tax

ISLAMABAD — Pakistan’s Federal Constitutional Court’s, three-judge bench this week delivered a quiet revolution. By upholding the controversial ‘Super Tax’ on the country’s wealthiest entities, the court did more than green-light a potential Rs300 billion (approximately $1.08bn) revenue haul. It etched into constitutional jurisprudence a stark boundary: fiscal policy is the exclusive domain of the legislature, not the judiciary. The ruling, led by Chief Justice Amin-ud-Din Khan, is a landmark reassertion of parliamentary sovereignty in economic governance, setting aside what it termed “judicial overreach” by lower courts. In a nation perennially navigating a crisis of public finance, this is a decisive shift of power back to the tax-writing desks of Parliament and away from the benches of the High Courts.
Why This Ruling Reshapes Pakistan’s Economic Constitution
The core of the dispute was seductively simple: could Parliament, through Sections 4b and 4c of the Income Tax Ordinance, levy a one-off surcharge on companies and individuals with incomes exceeding Rs500 million? High Courts in Karachi and Lahore had struck down or ‘read down’ the provisions, arguing on grounds of equity and policy merit. The Federal Constitutional Court’s reversal is foundational. It hinges on a strict interpretation of the separation of powers, a doctrine as venerable in Western polities as it is often contested in developing democracies. The bench declared that determining “tax slabs, rates, thresholds, or fiscal policy” is not a judicial function. This judicial restraint aligns Pakistan with a global constitutional consensus, echoing principles long established in jurisdictions like the United Kingdom, where parliamentary supremacy over taxation is absolute, and reaffirmed in landmark rulings by constitutional courts worldwide.
The immediate ‘what next’ is fiscal. The Federal Board of Revenue (FBR) can now confidently collect a tax it estimates will bring Rs300 billion into a chronically anaemic public exchequer. For context, that sum nearly equals the entire annual development budget for Pakistan’s infrastructure and social projects. In a country where the tax-to-GDP ratio languishes at around 10.6%—among the world’s lowest—this injection is not merely significant; it is transformative for a government negotiating yet another International Monetary Fund (IMF) programme predicated on enhancing revenue mobilization. The IMF has explicitly called for Pakistan to raise its tax-to-GDP ratio by 3 percentage points to 13% over the 37-month Extended Fund Facility program, making this ruling critically important for fiscal consolidation.
The Doctrine of Judicial Restraint in a Hot Economy
Why did the court rule so emphatically? Beyond the black-letter law, the decision is a strategic retreat from judicial entanglement in macroeconomic management. Pakistan’s courts have historically been activist, even in complex economic matters. This ruling signals a pivot toward a philosophy of judicial restraint, recognizing that judges lack the electoral mandate and technocratic apparatus to micromanage the nation’s balance sheet. As recognized in constitutional scholarship on the limits of judicial review, courts venturing into fiscal policy often create market uncertainty and implementation chaos—precisely what the FCC seeks to avoid.
The ruling also clarifies the temporal application of the tax: Section 4b applies from 2015 and 4c from 2022, ending years of legal limbo for businesses. This provides the certainty that investors and the World Bank consistently argue is critical for economic growth. For the business elite in Karachi’s financial district or Lahore’s industrial hubs, the message is clear: future battles over tax policy must be fought in the parliamentary arena, not the courthouse.
What Next: The Real Test of Governance Begins
The court has handed Parliament and the FBR a powerful tool and, with it, a profound responsibility. The ‘what next’ question now shifts from constitutionality to capacity and fairness. Can the FBR, an institution often criticized for its opacity and broad discretionary powers, administer this super tax efficiently and without political favouritism? Will the revenue truly be deployed for its stated purposes—from rehabilitating displaced persons (the original 2015 rationale) to bridging the general budget deficit? Court observations during hearings revealed that of Rs144 billion collected between 2015 and 2020, only Rs37 billion was spent on rehabilitation of internally displaced persons, raising legitimate questions about fiscal accountability.
Furthermore, Parliament’s exclusive authority is now doubly underscored. This invites, indeed demands, more rigorous legislative scrutiny of future finance bills. The ruling empowers backbenchers and opposition members to engage deeply in tax design, knowing the courts will not provide a backstop for poorly crafted law. Sustainable revenue growth requires not just legal authority but broad-based political legitimacy—a challenge that remains for Pakistan’s democratic institutions.
A Global Signal in an Age of Inequality
Finally, this ruling resonates beyond Pakistan’s borders. In an era of rising wealth inequality and global debates on taxing the ultra-rich, the judgment affirms the state’s constitutional right to enact progressive fiscal measures. The OECD and World Bank have increasingly emphasized the importance of progressive taxation in addressing inequality, with research showing that countries sustainably increasing their tax-to-GDP ratio to 15% experience significantly higher GDP per capita growth compared to countries whose tax ratio stalls around 10%—exactly Pakistan’s predicament.
The court has not endorsed the Super Tax’s wisdom; it has endorsed Parliament’s right to decide. It places Pakistan within a contemporary movement toward progressive wealth taxation, yet grounds it in the ancient principle that only the representatives of the people hold the power to tax—a foundational tenet of parliamentary sovereignty recognized across democratic systems.
The Constitutional Architecture Emerges
The ruling carries particular significance given Pakistan’s recent constitutional evolution. The creation of the Federal Constitutional Court through the 27th Constitutional Amendment, as Arab News analysis suggests, represents an institutional opportunity to resolve longstanding ambiguities in economic governance. When constitutional rules governing taxation, resource allocation, and federal-provincial fiscal relations remain unclear, governments litigate instead of coordinate, and businesses defend rather than invest. The FCC’s decisive stance on parliamentary authority in taxation may signal the court’s broader approach to economic constitutionalism—one that prizes institutional clarity and democratic accountability over judicial management of complex policy questions.
The marble halls of the FCC have thus returned a weighty question to the carpeted chambers of Parliament: having won the constitutional right to tax, can they now craft a fiscal contract with the nation that is both solvent and just? The Rs300 billion figure is a start, but the real accounting of this ruling’s success will be measured in the credibility of the state it helps to build—and whether Pakistan can finally escape the cycle of perpetually low tax collection that has constrained its development aspirations for decades.
This landmark decision arrives at a critical juncture as Pakistan navigates its Extended Fund Facility program with the IMF, with fiscal reforms remaining central to the country’s economic stabilization. The court’s affirmation of parliamentary supremacy in taxation provides the constitutional foundation necessary for sustainable revenue mobilization—but parliamentary action must now match judicial clarity.


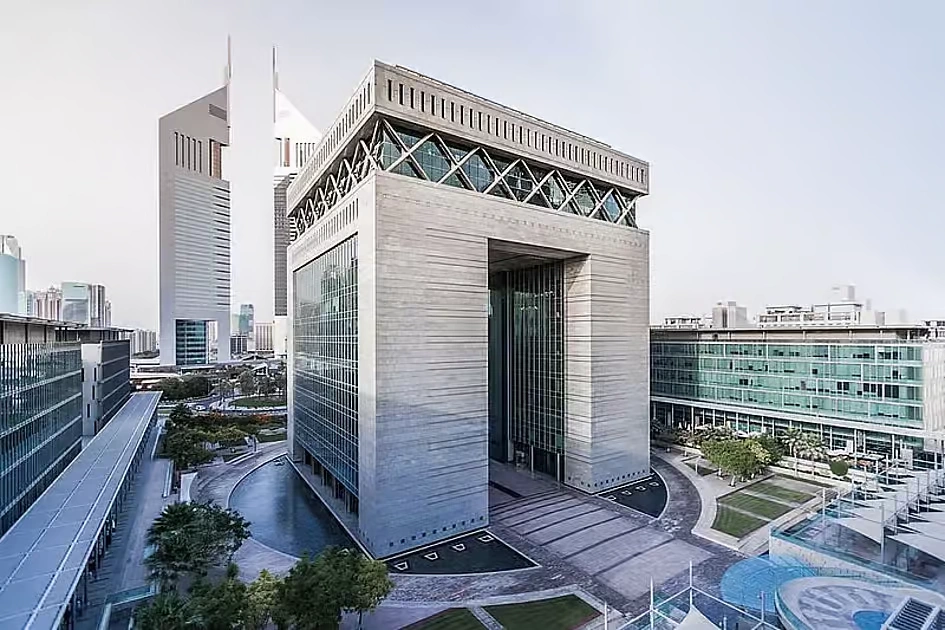
Dubai has climbed to its highest position ever on one of finance’s most closely watched rankings, and the achievement is no accident — it is the direct output of a decade-long, numerically explicit government strategy that few other financial centres have attempted to execute with this level of precision.
The Ranking Itself
The Dubai International Financial Centre has recorded its highest-ever position on the Global Financial Centres Index at seventh place worldwide, the highest ranking ever achieved by any financial centre across the Middle East, Africa and South Asia region, and the only MEASA-region centre to feature in the global top 20 — underscoring both its regional dominance and genuine global competitiveness.
The D33 Strategy Behind the Number
The ranking is explicitly tied to Dubai’s own stated ambitions. The GFCI result is described as pivotal to Dubai’s goal of becoming one of the world’s top four financial centres by 2033, in line with the Dubai Economic Agenda, or D33, which targets a doubling of the emirate’s economy over the decade. Separately, Dubai Chambers has confirmed the plan targets cumulative economic output of AED 32 trillion, or roughly $8.7 trillion, over the decade, supported by 100 transformative projects centred on trade expansion, digital innovation and sustainable growth.
The Underlying Economic Engine
The financial-centre ambitions are backed by genuine current-quarter growth. Dubai’s economy reached AED 232 billion in first-quarter 2026 GDP, a 2.4 percent year-on-year increase, with the finance, construction, healthcare, wholesale and retail trade, and real estate sectors all contributing to the broad-based expansion. Middle East Briefing separately projects the wider UAE economy will expand around 5 percent in 2026, with local banks positioned to increase lending both domestically — supporting SMEs, consumers and project finance — and across borders into markets like Saudi Arabia, where UAE banks’ comparatively lower interbank rates create an arbitrage opportunity.
Real Money Behind the Ranking
The GFCI climb is being validated by tangible transaction volume rather than sentiment alone. Weekly UAE business tracking shows a steady drumbeat of institutional activity: Sharjah Islamic Bank reported AED 803.9 million in net profit, up 15.3 percent, ADI Chain secured a $50 million investment to build sovereign digital infrastructure, and Capital.com reported $1.1 trillion in second-quarter trading volume routed through the jurisdiction. Separately, UAE and Saudi banks are projected to lead GCC credit growth in 2026, reinforcing Dubai and Abu Dhabi’s combined position as the region’s default financial gateway.
Why This Matters for Pakistan and South Asia
Dubai’s ascent as a financial hub carries direct relevance for Pakistan, where — as detailed in our companion coverage of Pakistan’s remittance exposure — roughly 55 percent of the country’s substantial remittance inflows originate from the Gulf Cooperation Council. A deepening, increasingly sophisticated DIFC-anchored financial ecosystem in Dubai means more efficient, lower-cost channels for that capital, alongside growing opportunities for Pakistani and South Asian firms to access GCC-sourced project finance and cross-border credit as UAE banks expand lending beyond their domestic market.
What is Dubai’s global financial centre ranking in 2026?
Dubai’s DIFC recorded its highest-ever ranking on the Global Financial Centres Index at 7th place worldwide in 2026 — the highest ever achieved by any Middle East, Africa or South Asia financial centre — as part of its stated goal to become a top-four global financial hub by 2033.
The Risk Beneath the Growth Story
Not every signal points to unambiguous strength. AGBI’s own reporting notes that UAE banks’ second-quarter results are likely to show weaker profits, slower lending and narrower margins, even as analysts characterise the underlying sector as fundamentally resilient — a reminder that Dubai’s financial-hub ambitions are being pursued against a genuinely more difficult regional operating environment shaped by the Strait of Hormuz disruption and broader Gulf security concerns, not in isolation from them.
The Bottom Line
Dubai’s climb to seventh in the GFCI rankings is less a one-off achievement than a measurable checkpoint on an explicitly numbered, decade-long strategic roadmap — one increasingly backed by real GDP growth, credit expansion, and institutional trading volume rather than ambition alone.
Rich Nations Face Make‑or‑Break Moment at COP31 Preparatory Talks
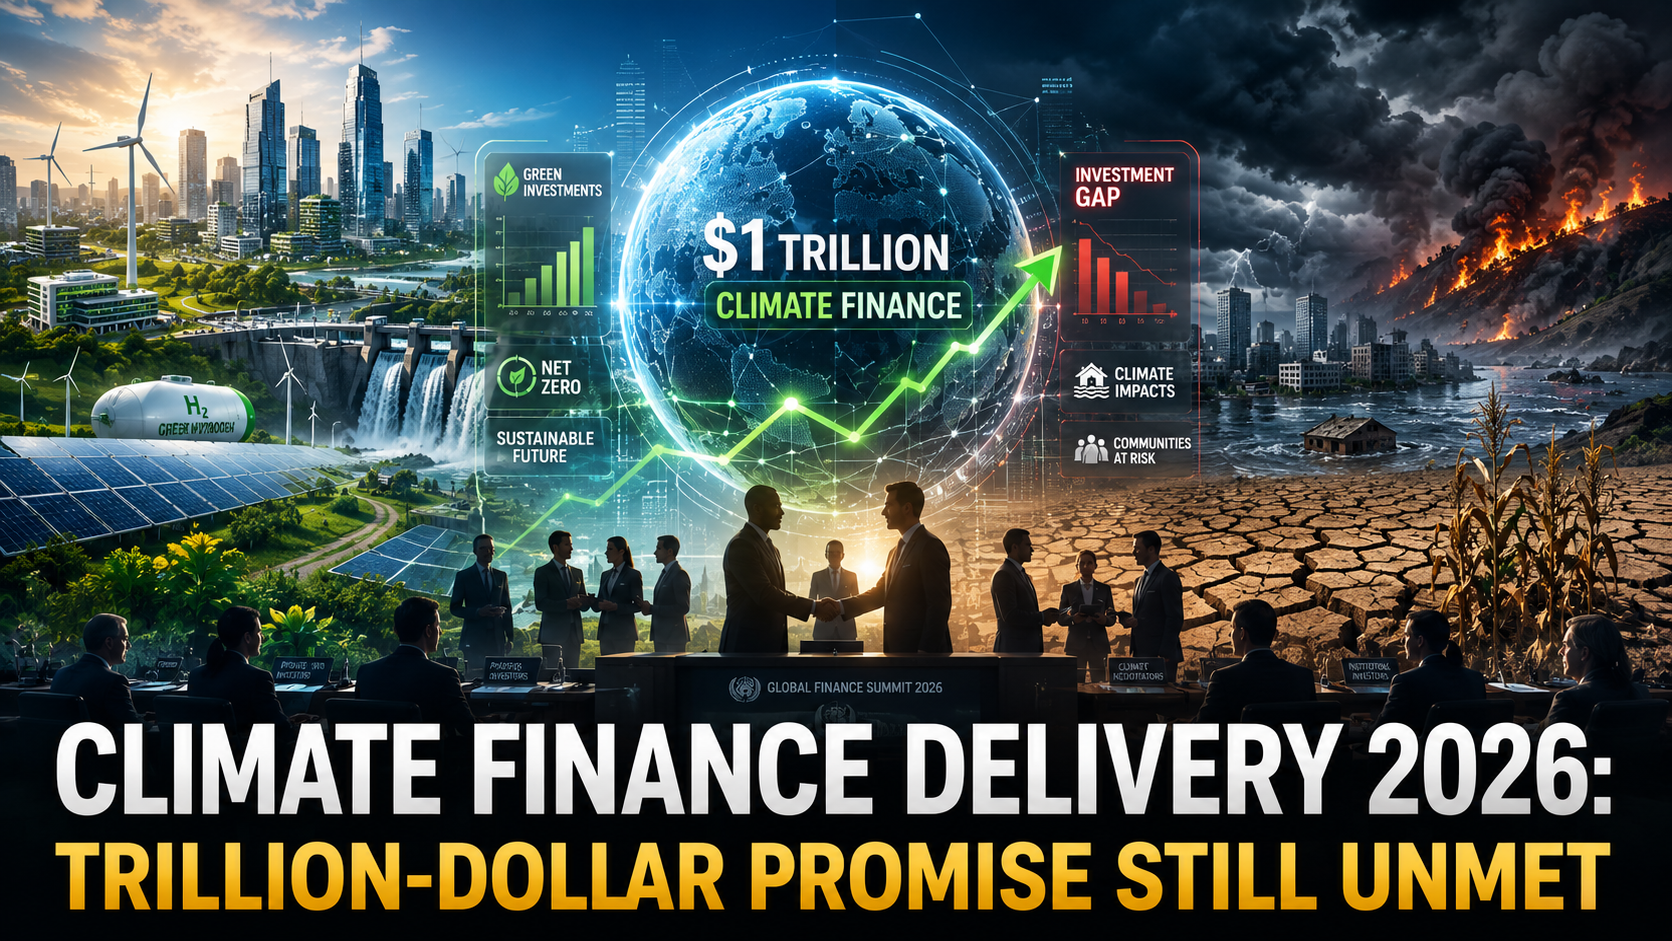
The United Nations Framework Convention on Climate Change (UNFCCC) has released a sobering assessment: climate finance delivery 2026 remains a staggering $1.1 trillion short of the $2.4 trillion that developing countries need annually to transition to low‑carbon economies and adapt to climate impacts (UNFCCC Standing Committee on Finance, June 2026). The report, published ahead of the pre‑COP31 ministerial in Bonn, reveals that total climate finance flows reached $1.3 trillion in 2024 (the latest available data), virtually flat from 2023. While the number is a record in absolute terms, the chasm between what is provided and what is needed is widening, not narrowing.
The Structure of the Shortfall
The $2.4 trillion annual need is broken down into three components: $1.2 trillion for mitigation (clean energy, industry decarbonisation), $800 billion for adaptation (sea walls, drought‑resilient crops, early warning systems), and $400 billion for loss and damage (compensation for unavoidable climate impacts). Currently, mitigation receives the lion’s share of finance—over 85%—mostly in the form of loans that add to debt burdens. Adaptation, which is most critical for the poorest countries, receives only $130 billion, and loss and damage, despite the operationalisation of a dedicated fund at COP28 in 2023, has seen a mere $2 billion in pledges against the $400 billion ask.
The loss and damage fund, a hard‑won victory for vulnerable nations, is emblematic of the gap between rhetoric and reality. Rich countries have committed just 0.5% of what the UNFCCC secretariat estimates is required for countries like Pakistan (2022 floods), Vanuatu (cyclones), and the Sahel (desertification) to rebuild in a climate‑resilient manner. The World Bank, which hosts the fund, has been slow to disburse, and the US, historically the largest historical emitter, has contributed only $500 million, a fraction of its fair share (World Bank Loss and Damage Fund Update, June 2026).
The NCQG Negotiations: Who Pays?
The NCQG negotiations (new collective quantified goal on climate finance) are the central battlefield of COP31, scheduled for November 2026 in Brasília. The current goal, set at COP15 in 2009, was $100 billion a year by 2020—a target met only in 2022. The new goal must reflect the drastically increased needs and a broader donor base. The EU and the US are insisting that China, now the world’s largest emitter and the second‑largest economy, must become a formal contributor, arguing that the 1992 division of the world into “Annex I” (developed) and “non‑Annex I” (developing) is outdated. China and the G77+China grouping counter that historical responsibility and per‑capita emissions still place the primary obligation on the old industrial powers.
The deadlock has been partially broken by a bridging proposal from the COP31 presidency (Brazil) that would create a three‑tiered system: Tier 1 contributors (traditional donors) would provide grants and concessional finance; Tier 2 contributors (high‑income developing countries like China, Saudi Arabia, Singapore) would provide non‑concessional loans and technology transfer; and Tier 3 contributors (multilateral development banks) would leverage their balance sheets to mobilise private capital. The proposal would set a cumulative target of $1.5 trillion a year by 2030, but the tiers’ shares remain hotly contested (UNFCCC, Pre‑COP31 Ministerial Draft Text, June 2026).
Mobilising Private Finance: The MDB Reform Agenda
Given the fiscal constraints in donor countries, the real engine of increased climate finance must be the multilateral development banks (MDBs) and the private sector. The World Bank, under its new president, has implemented the recommendations of the G20 Capital Adequacy Framework review, which could unlock an additional $100 billion in lending headroom over a decade without requiring new capital. The Bank is launching a new “Climate Enhanced” bond, where coupon payments are linked to verified emission reduction outcomes in a portfolio of African clean‑cooking and reforestation projects, targeting institutional investors hungry for impact‑linked returns (World Bank, Outcome Bond Issuance, June 2026).
The International Finance Corporation is expanding its “Green Up” guarantee facility, which de‑risks private investments in emerging‑market renewable energy by covering first‑loss risks. The Glasgow Financial Alliance for Net Zero (GFANZ) has evolved from a coalition of pledges to a set of country‑specific investment platforms: in Vietnam, a Just Energy Transition Partnership has mobilized $15 billion, and in Senegal, a similar platform is targeting $5 billion for solar and green hydrogen. These vehicles blend public concessional capital with private investment, but scaling them to the $2.4 trillion level remains aspirational.
The Cost of Inaction
The UNFCCC report emphasizes that every year of underfunding magnifies the eventual bill. The cost of inaction—measured in destroyed infrastructure, lost crop yields, and health crises—is accelerating. Swiss Re estimates that unabated climate change could reduce global GDP by 11% by 2050 (Swiss Re Institute, “Climate Economics”, 2026). For the private sector, climate risk is already material: supply chains are being disrupted by floods in Bangladesh and droughts in Panama, and insurance coverage is retreating from vulnerable regions, leaving assets stranded. The business case for closing the climate finance gap is not charitable; it is self‑interest.
The pre‑COP31 talks in Bonn are being described by veteran negotiators as the most consequential since Copenhagen 2009. The outcome will determine whether the Paris Agreement’s 1.5°C target remains within reach. The message from the UNFCCC is unambiguous: the world’s financial architecture is not fit for purpose in the face of a climate emergency, and the window for reform is closing fast.

The Asian Development Bank (ADB) has formally approved a landmark $700mn loan for Pakistan’s insurance sector, signaling an aggressive attempt to fortify the country’s fragile financial architecture against systemic climate and economic shocks. Signed in Islamabad by regional directors, the capital injection arrives at a delicate moment for the South Asian nation. With domestic insurance penetration languishing at historic lows, this massive facility represents more than a simple fiscal cushion. It is a legally binding blueprint designed to restructure how risk is priced, managed, and mitigated across one of the least developed financial markets in Asia.
Pakistan’s macroeconomic situation remains precarious. While recent agreements with the International Monetary Fund have temporarily stabilized foreign exchange reserves, structural vulnerabilities run deep. The country remains exceptionally exposed to environmental catastrophes. The devastating floods of 2022, for instance, caused over $30 billion in economic damage, yet less than 2% of those losses were covered by commercial insurance policies, according to data from the World Bank.
This lack of a domestic safety net forces the federal government to rely heavily on emergency deficit spending, worsening an already critical public debt burden. The domestic insurance sector has historically failed to expand beyond basic corporate coverage and mandatory automotive policies. By injecting capital directly into regulatory reform and market modernization, this new multilateral program intends to build a self-sustaining risk ecosystem that reduces the state’s direct liability when the next inevitable crisis hits.
The Asian Development Bank program is structured around three core pillars managed alongside the Securities and Exchange Commission of Pakistan (SECP). On October 14, 2025, initial program drafts detailed that the initial $300 million tranche will focus immediately on legislative overhauls. This includes updating the Insurance Ordinance of 2000 to align with international risk-based capital models. By forcing domestic firms to maintain capital reserves proportional to their actual underwriting risk, the regulator hopes to weed out insolvent operators and build institutional trust.
The remaining $400 million is tied to developing specialized market infrastructure. A primary objective is the creation of a national catastrophe reinsurance pool, which will distribute large-scale agricultural and infrastructure risks across international markets. Data from the Asian Development Bank reveals that current domestic reinsurance capacity cannot support even 10% of Pakistan’s commercial property assets. This shortfall forces local insurers to pass expensive premiums onto small businesses or avoid writing disaster policies altogether.
Furthermore, the loan introduces strict digital transformation mandates. Under the supervision of SECP Chairman Akif Saeed, domestic insurance companies will be required to build open-API architectures. This technological shift will enable mobile microinsurance platforms to reach rural populations. Currently, over 80% of Pakistan’s agricultural workforce operates entirely outside the formal banking system. Bringing these citizens into the financial fold via digital crop and health insurance is vital for long-term stability.
The capital will also support the modernization of the state-owned National Insurance Company Limited (NICL). Long criticized for administrative inefficiencies, NICL will undergo a complete digital audit to streamline claims processing. The goal is to reduce the average claim settlement time from nine months down to less than thirty days, setting a new operational benchmark for the private sector to follow.
To ensure compliance, the Ministry of Finance will establish a dedicated oversight committee. This body will publish quarterly progress reports on fund utilization, directly matching benchmarks set by the Securities and Exchange Commission of Pakistan. This level of transparency aims to reassure external bondholders that the funds are driving deep structural change rather than merely patching short-term fiscal deficits.
Pakistan Financial Sector Reforms
Moving beyond the immediate mechanics of the loan, the structural intervention reveals a deeper macroeconomic reality. Multilateral lenders are shifting away from general budgetary support toward targeted financial market interventions. The choice to focus heavily on insurance highlights a recognition that traditional banking sector liquidity cannot solve long-term capital scarcity. Without a functioning insurance market, local commercial banks remain hesitant to extend long-term credit for infrastructure or industrial expansion.
Why does Pakistan’s insurance sector require structural reform?
Pakistan’s insurance sector requires structural reform because its penetration rate sits below 1% of GDP, leaving the population exposed to macroeconomic and climate shocks. Outdated regulatory frameworks, low consumer trust, and insufficient capitalization prevent domestic insurers from absorbing large-scale commercial risks or offering viable microinsurance products.
This low penetration rate creates a dangerous loop. Because the domestic market is small, international reinsurers charge a premium to cover Pakistani risks. This keeps insurance costs prohibitively high for small and medium-sized enterprises (SMEs). According to a report by the Organization for Economic Co-operation and Development, economies with insurance penetration rates above 3% recover from economic shocks nearly three times faster than those dependent on ad-hoc state aid.
To contextualize Pakistan’s position relative to its regional peers, the stark divergence in financial depth becomes obvious when looking at insurance penetration across South Asia:
| Country | Insurance Penetration (% of GDP) | Primary Regulatory Model | State-Owned Market Share |
| India | 4.2% | Risk-Based Capital | Moderate (~40%) |
| Sri Lanka | 1.2% | Solvency II Equivalent | Low (~15%) |
| Bangladesh | 0.55% | Fixed Capital | High (~60%) |
| Pakistan | 0.91% | Solvency I (Outdated) | High (~50%) |
The structural overhaul also targets the core asset allocation of Pakistani insurance companies. Historically, domestic insurers have parked up to 85% of their premium reserves in low-yielding government bonds. While this strategy offers safe returns, it deprives the private sector of vital investment capital. The new risk-based capital framework will incentivize insurance firms to diversify their portfolios into corporate debt, venture funds, and green infrastructure bonds, fundamentally altering the flow of liquidity throughout the wider economy.
This portfolio diversification is expected to unlock roughly $1.5 billion in private sector investment over the next five years. By shifting away from sovereign debt, insurance companies will finally begin functioning as true institutional investors. This transition is critical for deepening Pakistan’s capital markets and reducing the corporate sector’s reliance on expensive, short-term commercial bank loans.
The downstream consequences of this capital injection will reshape the landscape of climate risk mitigation finance across South Asia. As climate patterns become increasingly erratic, the financial burden of rebuilding public infrastructure cannot rest solely on the national budget. By establishing a formalized framework for catastrophe bonds and weather-indexed insurance, Pakistan is laying the groundwork for private capital to absorb environmental risks.
For local businesses and agricultural operators, the rollout of inclusive insurance growth initiatives will alter daily operations. Consider a typical farmer in the Punjab region. Under the current system, a single season of erratic monsoon rainfall can result in total financial ruin, forcing the liquidation of assets and long-term poverty. Introducing reliable, low-cost crop insurance creates an economic floor, ensuring that families can purchase seeds and fertilizer for the following season regardless of weather outcomes.
On a macro scale, this shift stabilizes consumer demand and maintains rural purchasing power during downturns. The Financial Stability Board has consistently pointed out that unmitigated environmental risks pose a direct threat to banking stability. When agricultural yields collapse, non-performing loans spike across rural banking networks. By insulating farmers, the insurance sector acts as a shock absorber for the entire financial network.
Furthermore, international credit rating agencies monitor these developments closely. When agencies like Moody’s or Fitch assess Pakistan’s sovereign credit rating, the lack of disaster risk financing has historically acted as a significant negative factor. Demonstrating a structured, well-capitalized insurance mechanism lowers the country’s overall risk profile. Over time, this improvement can lower borrowing costs for both the state and private corporations looking to access international bond markets.
Private equity firms are already taking note of these regulatory changes. Several regional financial technology startups have initiated talks with local partners to launch dedicated insurtech apps. These ventures aim to capitalize on Pakistan’s high mobile penetration rate, transforming insurance from an elite corporate luxury into an accessible, everyday retail product for millions of previously unserved citizens.
Debt-Funded Financial Reforms
While the program’s objectives are ambitious, critics argue that loading another $700 million in foreign-currency debt onto Pakistan’s balance sheet carries profound risks. The country’s external debt obligations already consume a massive portion of its annual tax revenues. Some independent analysts suggest that using dollar-denominated loans to fund long-term domestic institutional adjustments creates a dangerous currency mismatch. If the Pakistani rupee depreciates significantly against the US dollar over the next decade, the cost of servicing this loan could vastly outweigh the economic benefits generated by the insurance sector.
The picture is more complicated when examining institutional capacity. Passing progressive legislation is simple compared to enforcing it across a resistant financial sector. Many smaller, family-owned insurance firms may lack the technical capabilities or capital depth to comply with the new risk-based guidelines. Forcing these entities into rapid compliance or liquidation could lead to market consolidation, reducing competition and leaving consumers with fewer choices and higher premiums.
Furthermore, skeptics point to the historical track record of state-led modernization schemes in Pakistan. Previous attempts to reform public enterprises have frequently stalled due to political interference and bureaucratic inertia. Without sustained political will and total regulatory independence for the SECP, there is a legitimate concern that these funds could be absorbed by administrative overhead rather than driving meaningful market change.
To mitigate these structural risks, external auditors must be given absolute authority to halt tranche releases if specific, pre-negotiated operational milestones are missed. Reliance on internal progress metrics has failed past reform programs, making independent verification a vital prerequisite for this initiative’s long-term success.
The ADB’s $700 million program is an unhedged bet on the transformative power of regulatory modernization. It attempts to address a fundamental structural vulnerability that has left Pakistan’s population and economy exposed to escalating macroeconomic and environmental shocks. Success will not be measured by the speed at which the capital is disbursed, but by whether the SECP can successfully build a competitive, well-capitalized marketplace that earns public trust.
If executed correctly, this initiative will provide Pakistan with the financial shock absorbers necessary to withstand future crises without relying on emergency bailouts. If it fails, it will simply become another line item on an already unsustainable national debt ledger. The coming years will determine whether this capital injection marks the birth of a resilient domestic risk market or stands as a costly reminder of the limits of debt-funded institutional engineering.
Building economic resilience requires structural foundations capable of outlasting temporary political cycles.

Diesel Prices 2026–2027: Why Cheaper Crude May Not Mean Cheap Fuel

2027 Social Security COLA: Key Details and Dates

KSE-100 Sees Major Drop Post-SBP Rate Hike

Big Tech’s AI Spending Test: Can Revenue Catch Up With Capital Expenditure?

AI Infrastructure Investment Strategies for 2026

Pakistan Freelancers Tax 2026: Payments, Documentation and Formal Growth

Strait of Hormuz Crisis: What the Latest Tanker Attacks Mean for Oil, Shipping and Global Trade

AI Customer Service in 2026: What’s Working, What’s Failing, and What to Buy

Open a Savings Account Online: How to Actually Earn 10x the National Average Rate

Global Housing Market 2026: Where Prices Rise, Where They Don’t

PSX and KSE-100 Record Highs: An Insider’s Guide to Pakistan Stocks

So Delicious Dessert Recall: Affected Products, FDA Guidelines, and Consumer Action

Pakistan’s Current Account Deficit Narrows Sharply to $98 Million in August 2026

Japan Eyes 3.5% Defense Spending: What It Means for Bonds, Stocks, and the BOJ

Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities

Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World

Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns

China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech

What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact

15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025

How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide

Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide

Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
-
 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
 Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
 Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
 Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
 AI11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
 Exports11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025