Analysis
Hyundai to Buy SoftBank’s Last Boston Dynamics Stake for $325 Million

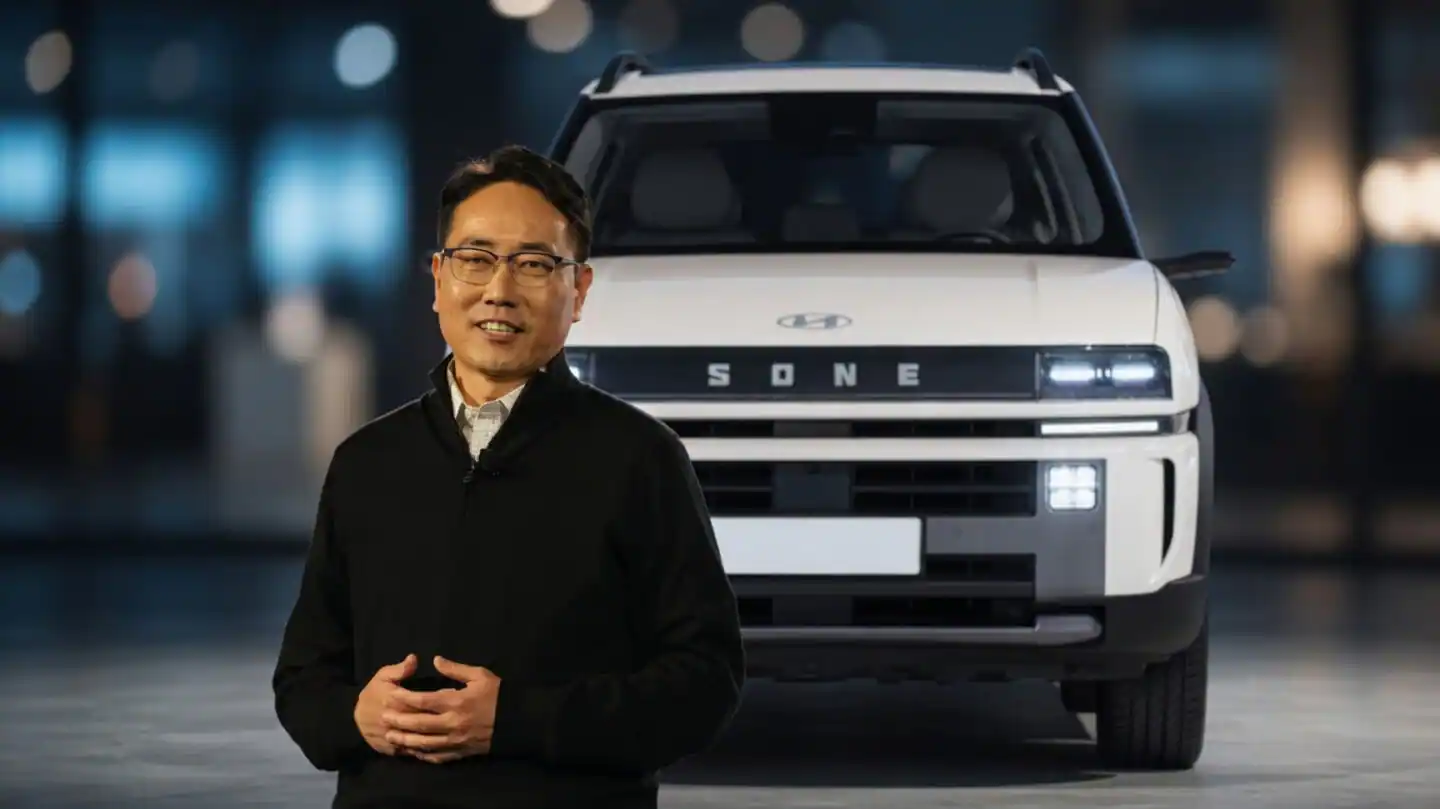
Hyundai Motor Group is about to own Boston Dynamics outright. According to South Korea’s Maeil Business Newspaper, the automaker plans to pay $325 million for SoftBank Group’s remaining 9.65% stake in the robotics firm, ending an ownership arrangement that has run since 2021. A board meeting is expected on June 22 to approve the purchase. It’s a tidy transaction by Hyundai’s standards. It’s also the final word on a five-year bet that has quietly become one of the most consequential industrial pivots in the automotive sector.
The timing isn’t incidental. Boston Dynamics’ Atlas humanoid robot began commercial production in January 2026, with every unit already committed to Hyundai’s own factories and Google DeepMind. SoftBank is cashing out just as the asset it’s selling starts to look genuinely valuable — and just as Hyundai prepares to run Boston Dynamics without an outside shareholder watching over the next phase.
This deal didn’t appear out of nowhere. SoftBank Group, under chairman Masayoshi Son, sold Boston Dynamics to Hyundai in a transaction completed in 2021, with Hyundai Motor Group — through Group Executive Chair Euisun Chung and affiliates Hyundai Motor, Kia, Hyundai Mobis and Hyundai Glovis — acquiring an 80% controlling stake for roughly $880 million, a deal that valued the robotics maker at $1.1 billion. Buried in that original agreement was a put option: the right for SoftBank to sell its remaining shares back to Hyundai at a later date, on terms fixed years in advance.
SoftBank has now chosen to exercise it. The report said SoftBank had told Hyundai that it would like to exercise its rights to sell its remaining stake in Boston Dynamics under a put option agreed when it sold Boston Dynamics to Hyundai. Hyundai Motor and SoftBank did not immediately respond to requests for comment when Reuters approached both companies on Friday.
That’s the mechanical story. The more interesting one is what the price implies.
Quick Math: A Valuation That’s Tripled
A $325 million payment for 9.65% of the company implies a Boston Dynamics valuation near $3.4 billion — more than three times the $1.1 billion mark set in 2020. That’s a striking re-rating for a robotics firm that, as recently as two years ago, was still mostly known for viral videos of robots dancing and opening doors. The jump reflects something specific: Atlas has gone from lab demo to factory deployment, and investors — even quasi-investors selling out via a contractual put option — are pricing that shift accordingly.
It gets more dramatic at the edges. Hyundai Glovis’ internal investment in Boston Dynamics last August reportedly implied a valuation closer to 30 trillion Korean won, or roughly $22 billion — a figure that, if accurate, would represent a near 24-fold increase from the 2021 baseline. The $325 million SoftBank exit, by contrast, is calculated off the original deal’s contractual formula, not current market enthusiasm. That gap between contract price and market price is the whole story here.
What Hyundai Is Actually Buying
Strip away the headline number and the deal does three concrete things.
First, it removes the last outside shareholder. Once the transaction closes, Hyundai Motor Group — through Chung and its four affiliates — will own 100% of Boston Dynamics, up from just over 90% today. No more SoftBank board seat, no more minority-shareholder reporting obligations, no more need to coordinate strategic decisions with a partner whose core business (AI infrastructure, chip investment, OpenAI exposure) has nothing to do with industrial robotics.
Second, it closes a chapter that’s been unusually well-traveled even by Silicon Valley standards. Boston Dynamics started life as an MIT spinoff, was bought by Google in 2013, sold to SoftBank in 2017, and then sold again to Hyundai in 2020. At the time of the original Hyundai transaction, SoftBank chairman Masayoshi Son said Boston Dynamics was “at the heart of smart robotics,” adding that SoftBank was pleased to partner with Hyundai to accelerate the company’s commercialisation. Four ownership changes in twelve years is a lot of turbulence for a company whose core engineering talent has remained largely intact throughout.
Third, and most practically, it simplifies governance at exactly the moment Boston Dynamics needs to scale manufacturing rather than research. The company’s enterprise-grade Atlas humanoid entered production at its Boston headquarters in January 2026, with initial deployments scheduled this year at Hyundai’s own Robotics Metaplant Application Center and at Google DeepMind, which is collaborating on the robot’s AI foundation models. Hyundai has also flagged a planned robotics factory — tied to a broader $26 billion U.S. manufacturing investment — capable of producing roughly 30,000 robots annually, expected to come online by 2028.
- 9.65% — SoftBank’s remaining stake being sold
- $325 million — the transaction price
- ~$3.4 billion — implied Boston Dynamics valuation from this deal
- 100% — Hyundai’s ownership of Boston Dynamics once the deal closes
- 30,000 units/year — capacity target for Hyundai’s planned robotics factory
Why a Robotics Bet Is Becoming an Industrial Strategy
How Much Will Hyundai Pay for Boston Dynamics’ Remaining Stake?
Hyundai Motor Group is acquiring SoftBank’s remaining 9.65% stake in Boston Dynamics for $325 million, a figure tied to a put option set in the original 2020 acquisition agreement. The purchase, expected to gain board approval on June 22, would make Boston Dynamics a wholly owned Hyundai subsidiary for the first time.
What’s notable isn’t the deal mechanics — it’s what Hyundai is signaling about its own identity. Car manufacturers buying robotics companies isn’t new. What’s new is a car manufacturer treating a robotics subsidiary as core enough to warrant full consolidation rather than a strategic minority position kept at arm’s length.
Hyundai’s own materials describe Atlas units beginning work at the Metaplant America facility in Savannah, Georgia, doing parts sequencing — repetitive, physically demanding tasks suited to humanoid form factors moving through human-built environments. That’s not a research demo. That’s a line item in a manufacturing budget. The picture is more complicated than “car company diversifies into robots.” It’s closer to a car company concluding that the next decade of competitive advantage in automotive manufacturing runs through humanoid labor, and deciding it doesn’t want a partner’s name on the cap table while it builds that capability.
That conclusion has industry-wide resonance. Tesla’s Optimus program has set an aggressive public timeline that hasn’t yet matched Boston Dynamics’ deployment pace, while Figure AI continues to raise capital around a similar thesis: humanoid robots as general-purpose industrial labor. Hyundai’s full buyout of Boston Dynamics is, among other things, a statement that it intends to compete in that race with an asset it controls outright, not one it shares.
The most immediate effect lands on SoftBank’s balance sheet. Son’s group has been redirecting capital aggressively toward AI infrastructure — most notably its roughly $41 billion commitment tied to OpenAI — and a clean, contractually pre-agreed exit from a non-core industrial asset fits that pattern. $325 million is a rounding error against SoftBank’s broader AI exposure, but it’s a clean one: no negotiation, no valuation dispute, just a put option exercised on schedule.
For Hyundai, the second-order effects are more interesting. Full ownership removes friction from decisions that matter over the next two years — capital allocation toward the 30,000-unit factory, IP licensing terms with Nvidia and Google DeepMind on AI foundation models, and how aggressively Boston Dynamics pursues customers beyond Hyundai’s own plants once 2027 capacity opens up. Boston Dynamics has indicated that all 2026 Atlas production is already committed to Hyundai and DeepMind, with outside customers arriving no earlier than 2027 — a sequencing decision that’s far easier to make without a second shareholder’s interests in the room.
There’s a market-confidence angle too. Hyundai’s stock on Korean exchanges moved higher within a day of the January CES announcement detailing the Atlas production plan, evidence that investors are pricing in optionality on humanoid robotics as a genuine Hyundai growth vector, not a side project. Full consolidation of Boston Dynamics — clean financials, no minority-interest carve-outs — should make that thesis easier for analysts to model going forward.
For component suppliers and automotive-adjacent manufacturers, the relevant detail is structural: Boston Dynamics says the new Atlas was deliberately designed around automotive-supply-chain compatibility, reducing unique parts so that the robot can be built using processes and vendors Hyundai already has in place. That’s a meaningful signal for any supplier currently serving Hyundai’s vehicle lines — robotics may become an adjacent revenue stream rather than a separate procurement universe.
Not everyone treats this as an unambiguous win. The implied valuation jump — from $1.1 billion in 2020 to roughly $3.4 billion in this transaction, and reportedly far higher in Hyundai’s own internal August 2025 mark — invites an obvious question: is Boston Dynamics actually worth that much, or is the number inflated by hype around humanoid robotics broadly, the same enthusiasm currently propping up Tesla’s Optimus narrative and Figure AI’s funding rounds?
Skeptics point out that Atlas’s entire 2026 production run is committed to exactly two customers, both with existing equity or strategic ties to Boston Dynamics. That’s not yet a market validating the product — it’s two related parties buying from themselves. Genuine third-party demand, the kind that would justify a multi-billion-dollar valuation independent of Hyundai’s own balance sheet, won’t be testable until 2027 at the earliest, when Boston Dynamics says it will onboard outside customers.
There’s also a simpler reading available: this is a contractual housekeeping transaction, not a strategic announcement. SoftBank agreed to a put option years ago and is exercising a right it always had, at a price formula set in 2020 — not a price discovered through fresh negotiation reflecting 2026 market conditions. Reading too much industrial strategy into a mechanical buyout, this view holds, risks mistaking routine cap-table cleanup for a grand robotics thesis.
Both readings can be true simultaneously. The transaction is mechanically routine and strategically significant — the put option made the timing inevitable, but Hyundai’s appetite to consolidate fully, rather than let the option lapse or renegotiate terms, says something real about how central robotics has become to its planning.
Strip away the contractual scaffolding and what’s left is a company quietly repositioning itself. Hyundai didn’t set out five years ago to become a humanoid robotics manufacturer with a side business making cars — but the capital allocation, the factory investment, and now the full ownership consolidation all point in that direction without anyone at Hyundai needing to say so directly. SoftBank, for its part, is simply following its own capital toward a bigger AI bet, leaving behind an asset that’s grown more valuable than anyone priced it to be in 2020.
Whether Boston Dynamics is worth $3.4 billion, $22 billion, or something in between will be tested honestly only once Atlas ships to a customer that isn’t also a shareholder. Until then, Hyundai owns the answer outright.


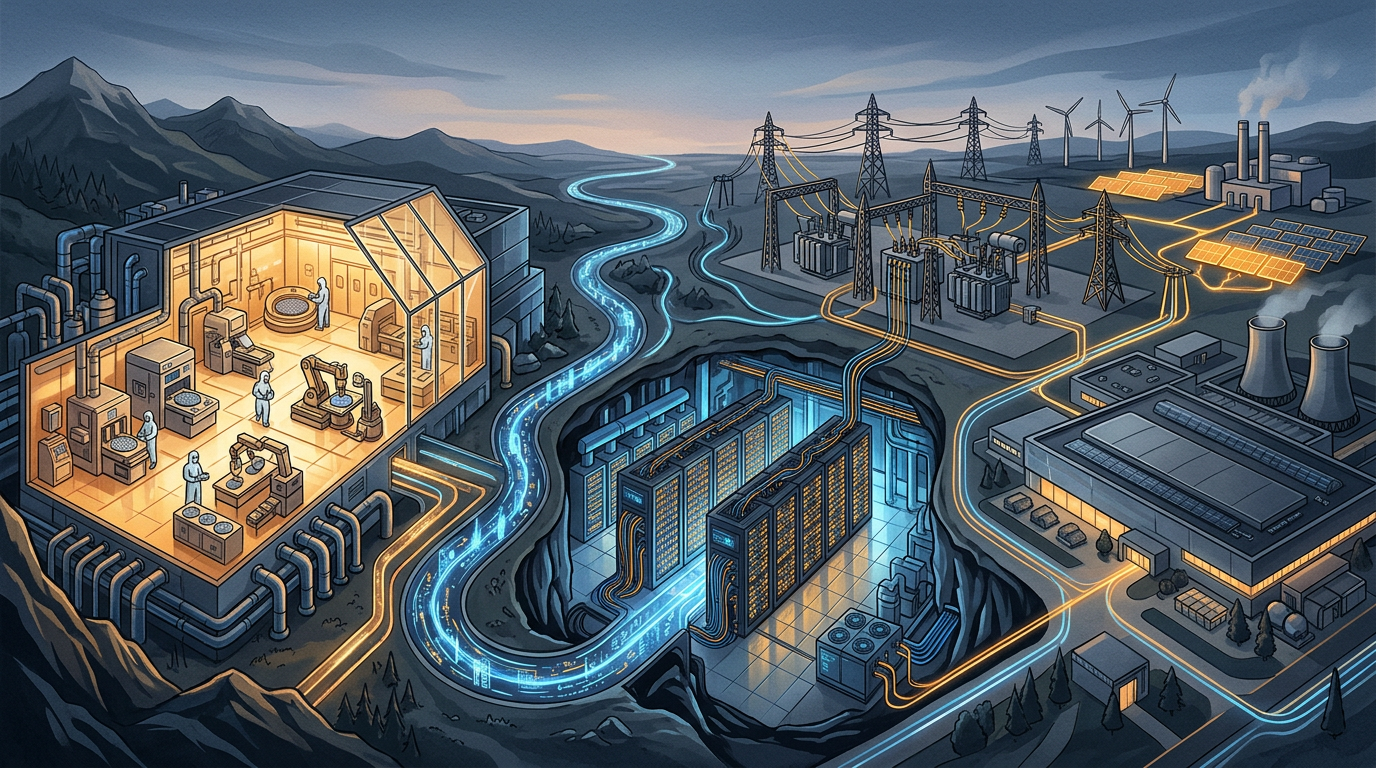
Investing in AI infrastructure—data centers, chips, and power—is particularly critical in 2026. As global economic growth diverges, capital has become far more sensitive to borrowing costs, forcing investors to look past compelling narratives and focus on realistic valuations. Rather than forecasting guaranteed returns, this guide examines key research methodologies and risk factors. According to the IMF’s October 2026 outlook, global growth is projected at 3.1% with inflation at 4.7%, even as its financial stability assessment cautions that underlying market vulnerabilities remain despite apparent resilience.
Key takeaways
- Match each investment decision to its time horizon, currency and ability to withstand losses.
- Separate observable earnings or contractual cash flows from optimistic forecasts.
- Compare diversification, fees, taxes, liquidity and regulatory restrictions before committing capital.
- Track primary institutional evidence and update assumptions when conditions change.
- Readers in Pakistan should consider rupee exposure and availability of regulated investment channels.
Why this matters now
The central question behind AI infrastructure investing 2026 is not merely what may happen next. It is which economic mechanisms could change cash flow, purchasing power or risk. The Bank for International Settlements’ 2026 review describes an economy supported by technological investment but constrained by geopolitical and fiscal pressures. A robust financial plan must therefore survive both a favourable and an adverse scenario.
Follow the investment chain, not just the headline
AI infrastructure spending flows through chips, advanced packaging, servers, networking, cooling, power equipment, real estate and utilities. Revenue can arrive at different times: hardware producers may book orders long before a data-centre tenant earns adequate cash flow from AI services. The BIS identifies AI investment as a support for recent global activity, but capital intensity can create financial fragility. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Semiconductors: strong demand does not erase cycles
Leading-edge manufacturing is capital intensive and technically complex. Constraints in memory, packaging or fabrication can create pricing power, while capacity expansions can later produce oversupply. Compare long-term contracts, customer concentration, inventory and returns on invested capital. A rising revenue line is insufficient if shareholders continually finance new assets.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Data centres and the cost of electricity
AI computing requires secure access to electricity, transmission connections, cooling water where relevant, and backup capacity. The International Energy Agency’s Energy and AI assessment documents the central role of electricity planning. Before evaluating an operator, examine energy contracts, utilization rates, construction delays and whether customers can meet long-term commitments. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Financing and correlated downside
The IMF warns that leveraged AI investments and concentrated exposures could magnify a valuation correction. Capital providers must distinguish contracted cash receipts from optimistic future sales estimates. Watch for circular financing, where investors and customers are economically dependent on each other’s ability to keep spending. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Pakistan’s realistic entry points
Pakistan is unlikely to replicate an advanced-chip fabrication cluster quickly. More plausible routes include enterprise software, cybersecurity, specialised engineering, managed services and targeted power or fibre investments where the economics support them. Any local investment thesis needs reliable energy, regulatory clarity, payment rails and skills rather than the assumption that every AI project is profitable. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Comparison and decision framework
| Question | Stronger evidence | Warning sign |
|---|---|---|
| What drives returns? | Audited cash flows, clear contract or transparent index | Undefined or projected returns |
| What can go wrong? | Explicit scenario and downside analysis | Claims of guaranteed gains |
| Is it affordable to hold? | Low transparent fees and adequate liquidity | Leverage, costly spreads or lockups |
| Is access legitimate? | Appropriate licensing and clear legal rights | Unverified brokers or custody |
| Is the exposure diversified? | Multiple independent sources of return | One company, sector or currency |
What it means for Pakistani savers and investors
A Pakistani reader faces both international investment risk and local purchasing-power risk. For example, a foreign asset can rise in US-dollar terms while the rupee conversion and transaction costs alter the realized local outcome. The opposite can also occur. Record the starting exchange rate, applicable taxes, custody charges and capital-transfer restrictions, and confirm current requirements with the State Bank of Pakistan and the relevant securities regulator. Overseas access should not be assumed universally available.
An emergency reserve, expensive consumer debt and near-term family obligations deserve attention before any speculative allocation. A portfolio that cannot meet a sudden cash requirement may force sales at the worst moment. The objective is not to remove risk—impossible in markets—but to choose risks that fit the investor’s actual liabilities.
Risks, limitations and uncertainty
Institutional forecasts are conditional and can change after policy decisions, commodity shocks, conflict escalation or unexpectedly weak earnings. Historic correlations are not binding promises about future asset performance. The analysis does not provide live stock prices, current investment product quotes, real-time exchange rates or individualized tax advice. Prices, regulations and product eligibility should be checked on the transaction date.
Frequently asked questions
Is this a guaranteed investment opportunity?
No. Every financial asset or strategy involves uncertainty. The existence of a popular investment theme is not evidence that an individual security is fairly priced.
What should beginners examine first?
Understand the product, the financial loss you could tolerate, fees and liquidity. Verify the provider and decide whether the money may be needed soon.
How do interest rates affect the analysis?
They influence financing costs, discount rates, exchange rates and demand. The effect differs by sector, maturity and business balance sheet.
Can Pakistani residents invest in foreign markets?
Access depends on current foreign-exchange, banking, brokerage, securities and tax rules, and on the investor’s individual circumstances. Check current regulations and regulated providers rather than assuming access.
How often should this analysis be refreshed?
Review institutional economic releases monthly and re-evaluate immediately after material earnings, regulatory or policy changes. Avoid reacting mechanically to every daily market movement.
Is diversification enough to prevent losses?
No. Diversification may reduce company-specific risk but cannot eliminate broad market, currency, inflation or systemic risks.
Conclusion
Sound financial decisions begin with verifiable evidence, reasonable valuation, awareness of uncertainty and a plan that survives adverse outcomes. Readers should compare multiple independent sources and avoid letting a compelling headline substitute for due diligence.
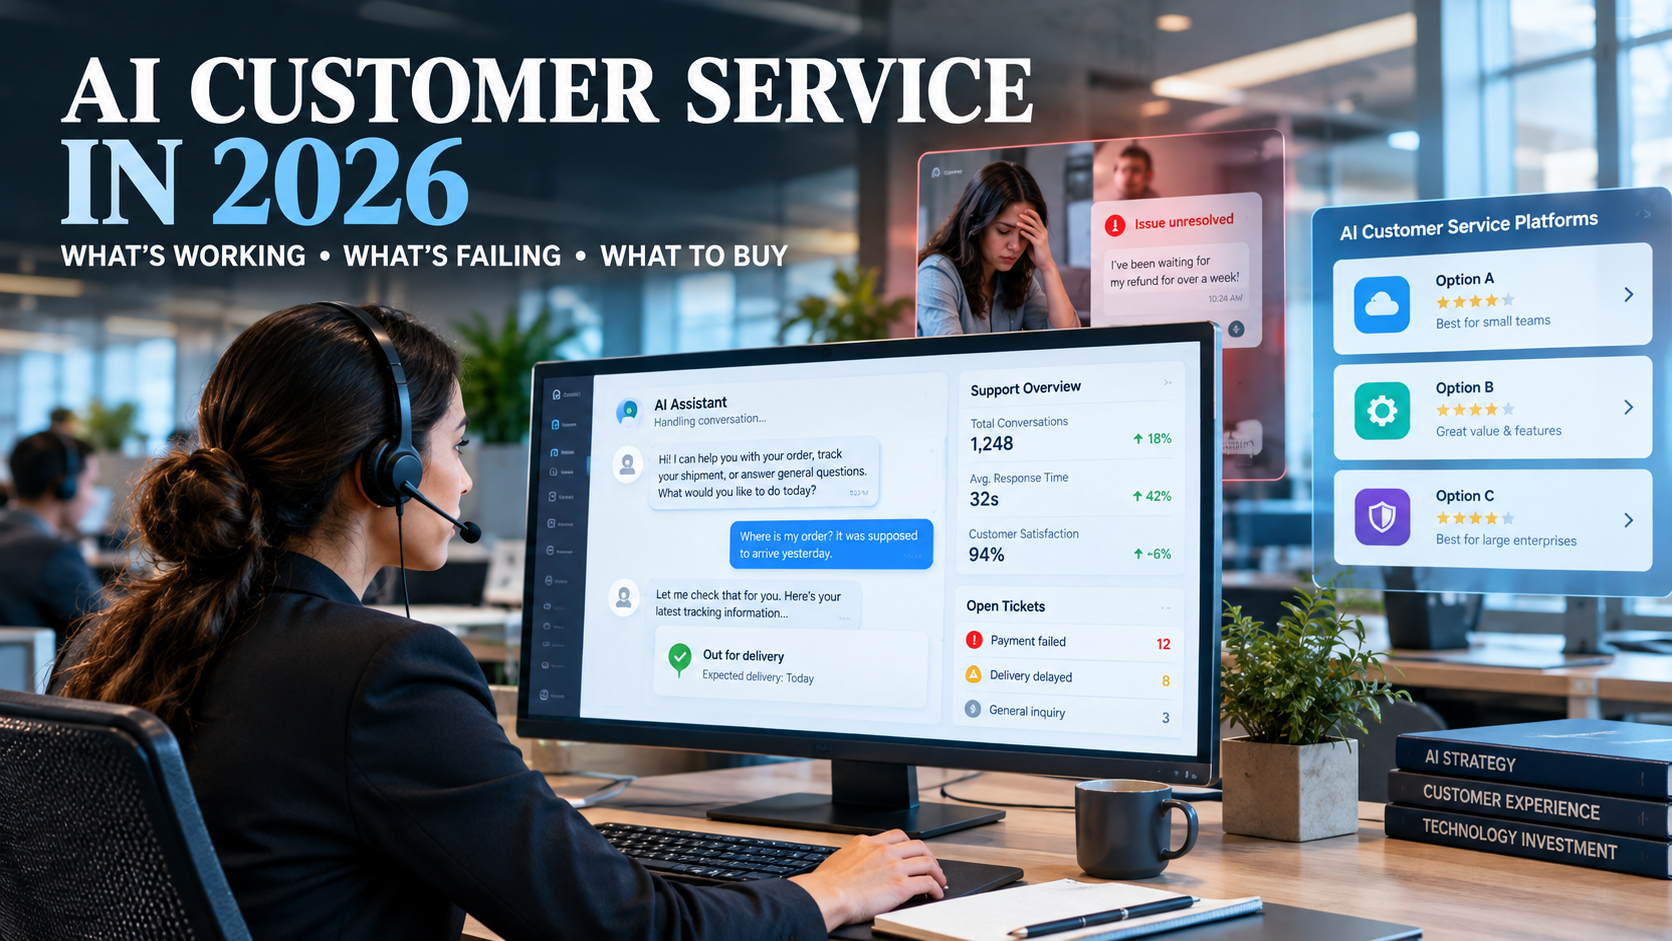
Almost every support team is now using AI. Far fewer customers say it solves their problem. That gap is the real story of AI customer service in 2026, and it decides which deployments pay off.
Key Takeaways
- Adoption doubled fast: Salesforce’s May 2026 survey of 3,075 service professionals found AI agent adoption rose from 39% to 66% in a year. getmacha
- Results lag: Only 24% of consumers said their last AI service interaction was fully resolved by AI alone, per an Ada and NewtonX study. getmacha
- Value shows up quickly: 70% of organizations deploying agents saw measurable value within 60 days. agilebrandguide
- Data is the blocker: 72% of service operations professionals call data readiness a major obstacle. agilebrandguide
- Forecast: Gartner expects agentic AI to autonomously resolve 80% of common customer service issues by 2029. raftlabs
What “AI Customer Service” Means Now
The first wave was scripted chatbots. The current wave is agentic AI: systems that interpret open-ended intent, read live customer data and resolve issues across connected systems without following a script. cygnet
The difference is action. A chatbot answers “where’s my order?” An agent checks the order system, issues the refund and updates the CRM.
The Adoption Numbers
| Metric | Figure | Source |
|---|---|---|
| Service orgs using AI agents | 66% (up from 39%) | Salesforce, May 2026 |
| Orgs using at least one form of AI | 85% | Salesforce |
| Teams at mature AI deployment | 10% | Intercom, Jan 2026 |
| Consumers fully resolved by AI alone | 24% | Ada/NewtonX, Mar 2026 |
| Agent use across customer-facing and internal work | 77% | Salesforce |
One caution applies to the headline adoption figures: Salesforce sells AI agents for service, so it has a commercial reason to publish momentum numbers. The Salesforce data is useful, but read it as a vendor’s view. Salesforce’s own service product page promotes the AI Agents Edition report, if you want to see how it frames the findings. getmacha
The Trust Gap
The most important number in this market isn’t adoption. It’s the 24% full-resolution rate. Companies are deploying AI faster than customers are being helped by it.
One compilation of 2026 statistics adds that 64% of customers wish companies would stop using AI in customer service, according to a Lorikeet survey. That’s a single-vendor figure, so use it as a directional signal rather than a settled fact. It still matches what most people have experienced: the bot that can’t escalate, the loop that never reaches a human. coworker
Where AI service typically fails:
- No escalation path: The customer can’t reach a person.
- Stale or fragmented data: The agent can’t see order history or account status.
- Overreach: The agent attempts complex or emotional cases it shouldn’t.
- Hidden AI: Customers feel tricked when they don’t know it’s a bot.
Where It Works
AI customer service performs best on narrow, high-volume, low-emotion requests: order status, password resets, returns and refunds, appointment changes and billing questions. 95% of service professionals say they trust AI for simple requests. Trust drops sharply as complexity rises. agilebrandguide
The ROI Question
Return figures vary widely. One 2026 compilation puts average ROI at $3.50 for every $1 spent, with leading organizations reaching 8x. Treat those as ceilings, not promises. The same compilation also notes 62% of service leaders worry about unpredictable AI costs. Usage-based pricing can erase savings if volume spikes. ringlyringly
A practical ROI model needs four inputs:
- Containment rate: Share of contacts fully resolved without a human
- Cost per contact: Human-handled versus AI-handled
- Quality impact: CSAT and repeat-contact rate, not just deflection
- Total AI cost: Licenses, usage fees, integration and ongoing tuning
Deflection that frustrates customers is a hidden cost. If containment rises while CSAT falls, you’re borrowing against retention.
Platform Landscape
Enterprise buyers commonly compare these platforms: Salesforce Agentforce, IBM watsonx Assistant, Microsoft Copilot Studio, Cognigy and Kore.ai. Each has strengths, so match the platform to your stack: cygnet
| If you already run… | Consider first |
|---|---|
| Salesforce CRM | Agentforce |
| Microsoft 365 and Dynamics | Copilot Studio |
| Heavy voice and contact-center volume | Cognigy |
| Multi-function (support, IT, HR) automation | Kore.ai |
| Regulated or hybrid environments | IBM watsonx Assistant |
This table is a starting framework, not a ranking. Integration depth with your CRM and ticketing systems usually matters more than headline features.
What the Workforce Impact Looks Like
Estimates of job impact are speculative and vary by source. One forecast says Gartner predicts organizations will replace 20% to 30% of service agents with generative AI by 2026. What’s more certain is that roles change: simpler tickets disappear, and humans handle harder, more emotional cases. That requires different training and often different pay structures. raftlabs
A Buyer’s Checklist
Before signing a contract, answer these:
- Data readiness: Is customer data clean, unified and accessible to the agent?
- Escalation design: Can customers reach a human in one step?
- Transparency: Do customers know they’re talking to AI?
- Governance: Who audits agent decisions and refunds?
- Metrics: Are you tracking resolution and CSAT, not only deflection?
- Pricing: What happens to cost when volume doubles?
What’s Next
Salesforce’s research frames the next phase around governance and workforce roles, recommending clear roles for AI architects and data specialists, plus transparent interactions with clear escalation to humans. That advice is sensible regardless of vendor. agilebrandguide
The Bottom Line
AI customer service works when it’s narrow, well-fed with data and honest about its limits. It fails when companies treat it as a headcount-cutting shortcut. With adoption now past 60%, competitive advantage will come less from having AI and more from deploying it without losing customer trust. Start with simple, high-volume requests, measure resolution rather than deflection, and keep a human exit visible.
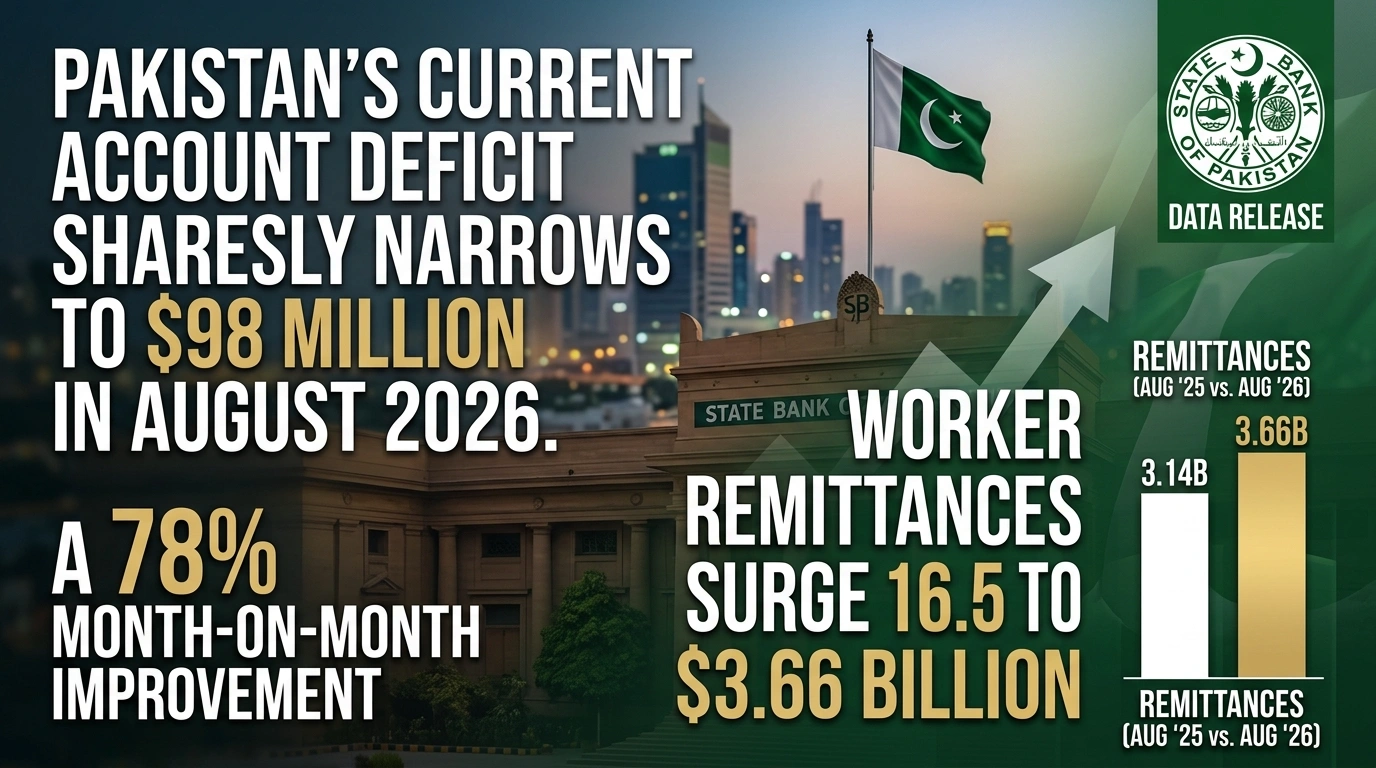
Karachi — Pakistan’s external balance demonstrated significant resilience as the monthly Current Account Deficit (CAD) contracted sharply to $98 million in August 2026, down 78% month-on-month from $445 million recorded in July 2026. Official data released by the State Bank of Pakistan (SBP) highlights that strong worker remittance inflows and steady export growth offset a surging import bill, providing crucial relief to the nation’s balance of payments.
Compared to the same period last year, the monthly shortfall narrowed by 69.7.3% from the $324 million deficit registered in August 2025. Cumulatively, during the first two months of the current fiscal year (2MFY27), Pakistan’s current account deficit stood at $543 million, marking a 36.3% reduction compared to the $853 million deficit incurred in 2MFY26, according to official economic indicators compiled by Dawn News Financial Analysis.
Key Drivers Behind August 2026 External Account Performance
1. Robust Remittance Inflows as the Core Anchor
Overseas Pakistani workers remitted $3.656 billion during August 2026, registering a 16.5% year-on-year (YoY) increase compared to $3.14 billion in August 2025 and a 0.7% month-on-month growth over July’s $3.63 billion.
- Saudi Arabia: Remained the largest contributor, accounting for $873.5 million (+19% YoY).
- United Arab Emirates (UAE): Inflows rose to $749.8 million (+17% YoY).
- United Kingdom & EU: Remittances from the UK totaled $563.7 million (+22% YoY), while European Union corridors dispatched $496 million (+7% MoM).
- United States: Inflows reached $308.9 million (+16% YoY).
Cumulative remittance inflows for 2MFY27 reached $7.29 billion, representing a 14.7% YoY increase from $6.36 billion recorded during the same period in FY26, as reported by Express Tribune Business.
2. Trade Balance and Import-Export Dynamics
- Exports of Goods & Services: Reached $3.33 billion in August 2026, reflecting a 5.0% YoY rise compared to $3.17 billion in August 2025.
- Imports of Goods & Services: Expanded to $6.64 billion, an increase of 8.0% YoY from $6.15 billion in August 2025, driven largely by essential industrial raw materials and energy imports required to support ongoing economic revival.
Macroeconomic Comparison Matrix: Current Account Breakdown
The table below illustrates the shift across key trade and primary income metrics for Pakistan’s balance of payments, as monitored by Trading Economics – Pakistan Balance of Payments:
| Economic Metric | August 2026 | July 2026 | August 2025 | 2MFY27 Cumulative | 2MFY26 Cumulative | YoY Shift (%) |
| Current Account Balance | -$98M | -$445M | -$324M | -$543M | -$853M | -36.3% |
| Worker Remittances | $3.656B | $3.630B | $3.140B | $7.286B | $6.353B | +14.7% |
| Total Exports (Goods & Services) | $3.330B | $3.180B | $3.170B | $6.510B | $6.120B | +6.37% |
| Total Imports (Goods & Services) | $6.640B | $6.520B | $6.150B | $13.160B | $12.380B | +6.30% |
| Foreign Exchange Reserves (Excl. CRR) | $17.280B | $16.900B | $14.520B | $17.280B | $14.520B | +19.0% |
| Net Foreign Direct Investment (FDI) | $315.9M | $185.2M | $175.1M | $501.1M | $342.0M | +46.5% |
Exchange Rate Competitiveness & FDI Momentum
REER and NEER Movements
Alongside the current account update, SBP data revealed that Pakistan’s Real Effective Exchange Rate (REER) index recorded a minor increase of 0.02% MoM, reaching 107.92 in August 2026 compared to 107.89 in July 2026.
Meanwhile, the Nominal Effective Exchange Rate (NEER) index depreciated by 0.79% MoM to 38.02 in August from 38.32 in July. While a REER above 100 indicates mild export price pressure, analysts cited by Reuters Global Markets note that exchange rate stability has helped maintain import predictability without severely penalizing key manufacturing sectors.
Surge in Foreign Direct Investment
Net Foreign Direct Investment (FDI) inflows saw a sharp increase, totaling $315.9 million in August 2026—an 80.4% YoY expansion compared to $175.1 million in August 2025. Key capital inflows targeted energy, telecommunications, and infrastructure projects, underscoring rising investor confidence supported by ongoing fiscal discipline and structural economic reforms monitored by Bloomberg Markets.
Macroeconomic Implications & Policy Outlook
- Foreign Reserve Buffer Expansion: Total SBP-held foreign exchange reserves (excluding CRR/SCRR) expanded to $17.28 billion, an increase of 19% YoY. This build-up strengthens Pakistan’s external liquidity buffer, providing over 2.6 months of import cover.
- Impact on Monetary Policy: The narrowing CAD and stable exchange rate dynamics offer the State Bank of Pakistan headroom to maintain a measured monetary easing cycle, encouraging domestic capital formation without reigniting demand-pull inflation.
- IMF Program Benchmark Compliance: Lower current account vulnerabilities position Pakistan favorably for ongoing review under international financial assistance programs, ensuring sustained access to multilateral funding channels.

AI Infrastructure Investment Strategies for 2026

Pakistan Freelancers Tax 2026: Payments, Documentation and Formal Growth

Strait of Hormuz Crisis: What the Latest Tanker Attacks Mean for Oil, Shipping and Global Trade

AI Customer Service in 2026: What’s Working, What’s Failing, and What to Buy

Open a Savings Account Online: How to Actually Earn 10x the National Average Rate

Global Housing Market 2026: Where Prices Rise, Where They Don’t

PSX and KSE-100 Record Highs: An Insider’s Guide to Pakistan Stocks

So Delicious Dessert Recall: Affected Products, FDA Guidelines, and Consumer Action

Pakistan’s Current Account Deficit Narrows Sharply to $98 Million in August 2026

Japan Eyes 3.5% Defense Spending: What It Means for Bonds, Stocks, and the BOJ

PSX & KSE Forecast 2026: Navigating the Latest IMF Reports & World Bank Metrics

Trump Administration’s Crypto Policy: Deregulation and the Future of Digital Assets

Monetary Policy and the Policy Rate

Gold, Silver & Bitcoin Prices Q4 2026: Wealth Management Strategies

Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities

Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World

Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns

China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech

What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact

15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide

Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation

Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-
 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
 Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
 Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
 Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
 AI10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
 Exports10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025