
Investment
US Oil Giants Demand Investment Guarantees Before Venezuela Entry as Trump Negotiates Access to World’s Largest Reserves

Behind closed doors this week, America’s most powerful oil executives delivered an uncomfortable message to President Donald Trump’s administration: Venezuela’s vast oil reserves—the world’s largest at 303 billion barrels—remain off-limits without unprecedented investment protections.
As Trump seeks to reshape global energy markets following the dramatic U.S. military operation that captured Venezuelan President Nicolás Maduro, industry leaders from ExxonMobil, Chevron, and ConocoPhillips are demanding written guarantees against nationalization, sanctions reversals, and political interference before committing capital to a country that expropriated more than $30 billion in foreign assets just over a decade ago.
The stakes extend far beyond Venezuela’s borders. Trump’s ability to broker a deal could define his administration’s energy dominance strategy and test whether economic incentives can stabilize a failed petrostate 1,200 miles from Florida’s coast. Yet three days after Maduro’s capture, oil companies remain deeply skeptical—and the numbers explain why.
The Reluctant Billionaires: Why Big Oil Is Saying “Not So Fast”
Despite Trump’s public optimism that U.S. oil companies are “ready and willing” to invest, industry sources paint a starkly different picture. Energy Secretary Chris Wright met with oil executives Wednesday at the Goldman Sachs Energy Conference in Miami, followed by a White House meeting Friday with CEOs from ExxonMobil, Chevron, and ConocoPhillips—but no companies have committed to new investments.
“The appetite for jumping into Venezuela right now is pretty low,” a senior energy executive familiar with discussions told CNN, speaking on condition of anonymity. The executive cited three insurmountable obstacles: collapsing oil prices, Venezuela’s nightmarish track record, and complete uncertainty about who actually controls the country.
The Price Problem Nobody’s Talking About
Global oil markets are drowning in oversupply. Brent crude tumbled 20% in 2025, closing the year near $60 per barrel—its worst annual performance since the pandemic. The U.S. Energy Information Administration projects Brent will average just $55 per barrel through 2026, with some analysts warning prices could dip below $50.
These depressed prices fundamentally undermine the investment case for Venezuela. Consulting firm Rystad Energy estimates that maintaining Venezuela’s current production of roughly 1 million barrels per day would require $53 billion through 2040. Returning the country to its 1990s peak of 3.5 million barrels daily demands a staggering $183 billion—nearly impossible to justify when oil hovers around $60.
“Just because there are oil reserves—even the largest in the world—doesn’t mean you’re necessarily going to produce there,” another industry source told CNN. “This isn’t like standing up a food truck operation.”
Francisco Monaldi, director of the Latin America Energy Program at Rice University’s Baker Institute, reinforced this reality: rebuilding Venezuela’s infrastructure to reach 4 million barrels per day would require more than $100 billion and take at least a decade.
What Companies Are Demanding: The Non-Negotiable Investment Protections
Behind the scenes, oil executives have outlined specific conditions they’ll need before risking capital in Venezuela. These demands reflect hard-won lessons from 2007, when President Hugo Chávez nationalized the oil sector and forced foreign companies to accept minority stakes or exit entirely.
Legal Shields Against Nationalization
At the top of every company’s list: ironclad protections against expropriation. When Chávez seized control in 2007, ExxonMobil and ConocoPhillips refused the new terms and walked away from billions in assets. International arbitration courts later ruled in their favor—ConocoPhillips won an $8.7 billion award in 2019, while ExxonMobil secured $1.6 billion—but Venezuela has paid only a fraction of these judgments.
According to CNBC’s reporting, Venezuela currently owes ConocoPhillips approximately $10 billion and ExxonMobil around $2 billion when interest is included. These unpaid debts cast a long shadow over any new investment discussions.
Industry experts say companies now want bilateral investment treaties with teeth—agreements that allow immediate recourse to international arbitration and specify compensation at full market value, not the artificially low “book value” Venezuela offered in 2007.
Sanctions Certainty and Congressional Buy-In
Oil companies fear the “sanctions whiplash” that could occur if a future administration reverses Trump’s policies. Current U.S. sanctions, expanded under both Trump and Biden, have essentially embargoed Venezuelan oil exports. Any Trump-era deal based solely on executive authority could evaporate when he leaves office.
“No one’s going to start investing on the ground in a place where there’s no legal contract and viable permission to operate or if there’s concerns about political stability and violence,” Ryan Kepes, an energy analyst, told NPR.
Companies want legislative backing—either new laws or amendments to existing sanctions frameworks—that would survive beyond Trump’s presidency. Without congressional approval, any investment represents a billion-dollar bet on political continuity that few executives are willing to make.
Operational Autonomy and Profit Repatriation
Venezuela’s state oil company, PDVSA, is effectively bankrupt. The entity that once generated 95% of Venezuela’s export earnings now struggles to maintain basic operations. Yet under current Venezuelan law, PDVSA must hold majority stakes in all oil projects.
Oil executives are demanding unprecedented operational control—the ability to hire international staff, import equipment without bureaucratic delays, and most critically, repatriate profits without Venezuela’s crushing currency controls. The country’s black market exchange rate differs so dramatically from official rates that companies fear losing billions to government-mandated conversions.
Venezuela’s Collapsing Infrastructure: A $100 Billion Problem
The physical reality on the ground makes investment even more daunting. Venezuela’s oil infrastructure has deteriorated dramatically over two decades of underinvestment, mismanagement, and sanctions.
Current production stands at approximately 950,000 barrels per day—down from 3.5 million barrels daily in the late 1990s and a peak of 3.7 million in 1970. PDVSA itself acknowledged that its pipelines haven’t been updated in 50 years, according to CNN reporting.
The technical challenges are immense. Venezuela produces predominantly “extra-heavy” crude from the Orinoco Belt—oil so dense it barely flows and requires specialized processing. This crude contains high sulfur content, making it more expensive to refine and less attractive in an era when many refiners have invested in lighter, sweeter crude infrastructure.
A World Bank analysis published late last year noted that even optimistic scenarios—assuming immediate sanctions relief and political stability—would require 18-24 months before any new production comes online. More realistic projections stretch to 3-5 years for meaningful output increases.
“Venezuela’s oil infrastructure has also been heavily degraded by decades of underinvestment and much of Venezuela’s oil is extremely heavy, making it relatively costly to extract and process,” Neal Shearing, group chief economist at Capital Economics, explained in a report.
The Geopolitical Chess Match: Why Trump Needs This Deal
For the Trump administration, success in Venezuela represents a geopolitical trifecta: undercutting Russian and Chinese influence, providing heavy crude to U.S. Gulf Coast refiners, and demonstrating American power projection in the Western Hemisphere.
The Russia-China Factor
For years, Venezuela has relied on economic lifelines from Moscow and Beijing. Russia’s state oil company Rosneft provided billions in prepayment deals, while China extended over $60 billion in loans-for-oil arrangements. Yet neither country invested the massive capital needed to reverse production declines—they simply extracted value from existing, deteriorating assets.
Trump’s intervention disrupts this model. Energy Secretary Wright emphasized at the Goldman Sachs conference that the administration will control Venezuelan oil sales “indefinitely,” redirecting barrels that previously flowed to China toward U.S. markets instead.
Marco Rubio, Trump’s Secretary of State, has been even more explicit about geopolitical objectives. The administration is pressing Venezuela’s interim government to expel all Chinese, Russian, Cuban, and Iranian intelligence operatives—a demand that reveals how deeply national security concerns drive the oil agenda.
The Refinery Economics Nobody Discusses
There’s a hidden economic logic behind Trump’s Venezuela push that rarely makes headlines: U.S. Gulf Coast refineries desperately need heavy crude.
These refineries—concentrated in Texas and Louisiana—invested billions in complex processing units specifically designed to handle heavy, high-sulfur crude. When Venezuelan supplies disappeared, they turned to Canadian oil sands and occasional Mexican imports. But Venezuela’s Orinoco crude remains uniquely suited to their equipment.
S&P Global Commodity Insights data shows that heavy crude typically trades at a $10-15 discount to lighter grades—a margin that makes these refineries highly profitable when they can source steady supplies. Restoring Venezuelan flows could lower gasoline and diesel prices along the Gulf Coast while boosting refinery margins.
Skip York, a fellow at Rice University’s Center for Energy Studies, noted that if Venezuela achieves political and economic stability, investors could expect returns of 15-20%—competitive with other global opportunities. But that’s a massive “if.”
The Historical Scar Tissue: Why 2007 Still Matters
The shadow of Hugo Chávez’s 2007 nationalization hangs over every conversation about Venezuela today. Understanding what happened then is essential to grasping why companies remain so hesitant now.
The Forced Renegotiation
In early 2007, Chávez ordered all foreign oil companies operating in the strategic Orinoco Belt to convert their projects into joint ventures with PDVSA holding at least 60% control. Companies had a stark choice: accept minority status under worse terms or exit entirely.
Chevron accepted and stayed. ExxonMobil and ConocoPhillips refused and were effectively expelled. CBC News reporting describes this as “the biggest seizure of private property in the country since Chavez took power.”
The Arbitration Marathon
What followed was a decade-long legal battle that still hasn’t concluded. ExxonMobil filed claims under bilateral investment treaties, initially seeking $16.6 billion. In 2014, an ICSID tribunal awarded $1.6 billion—far less than sought but still unpaid. The company continues pursuing additional claims.
ConocoPhillips initially won $2 billion in 2018, but a fuller ICSID decision in 2019 increased the award to $8.7 billion plus interest. Venezuela appealed unsuccessfully, with an annulment committee upholding the entire award in January 2025. Yet ConocoPhillips has collected virtually nothing.
These unpaid judgments create a unique leverage point. Trump has hinted that settling these debts might be prerequisite to new investment, telling reporters the oil companies will “take back the oil that, frankly, we should have taken back a long time ago.”
However, Energy Secretary Wright suggested old debts aren’t an immediate priority. “The huge debts that are owed Conoco and Exxon, those are very real and need to be recompensed in the future,” Wright told CNBC. “But that’s a longer-term issue. That’s not a short-term issue.”
Chevron’s Unique Position: The Only Player on the Ground
While ExxonMobil and ConocoPhillips nurse old wounds, Chevron stands alone as the only U.S. major with current Venezuelan operations—making it the most important company in any restoration scenario.
Chevron accepted Chávez’s 2007 terms and maintained a presence through two decades of sanctions, economic collapse, and political upheaval. The Biden administration granted a limited license in 2022 allowing Chevron’s PDVSA joint venture to export oil, which Trump’s administration later modified.
Kpler data shows Chevron exported approximately 140,000 barrels per day from Venezuela in Q4 2025—modest volumes but critically important for maintaining relationships and operational knowledge.
“Chevron is the best positioned among US oil companies—by far,” Francisco Monaldi, the Rice University energy expert, told CNN. The company has 3,000 employees in Venezuela, existing infrastructure, and relationships with PDVSA that could enable rapid production increases if conditions improve.
Yet even Chevron has been circumspect. In a carefully worded statement, the company said it “remains focused on the safety and well-being of our employees, as well as the integrity of our assets,” while declining to comment on expansion plans. Translation: we’re watching and waiting.
The Market Reality Check: Oversupply Kills Investment Appetite
Perhaps the most fundamental obstacle to Trump’s Venezuela vision is one he cannot control: the global oil glut.
International Energy Agency data shows the oil market has been in surplus since early 2025, with production outpacing consumption by approximately 2.5 million barrels per day in the second half of the year. The IEA projects this oversupply will reach 3.8 million barrels daily in 2026.
OPEC+ production increases, booming U.S. shale output, and rising volumes from Brazil, Guyana, and Canada have flooded markets while demand growth stalls. Chinese economic weakness and accelerating electric vehicle adoption have dampened consumption just as supply surges.
For oil companies, this creates a brutal calculation. At $60 per barrel, many U.S. shale producers remain profitable—barely. But investing tens of billions in a risky foreign venture with a 5-10 year payback period makes no economic sense when prices are falling and domestic opportunities exist.
“The bottom line is that adding Venezuelan oil makes the oversupply worse,” said Bob McNally, president of Washington-based consulting firm Rapidan Energy Group. “Companies are cutting back on drilling in the Permian Basin because of oversupply. Why would they rush to Venezuela?”
Bloomberg analysis noted that ExxonMobil, Chevron, and ConocoPhillips are collectively laying off about 14,000 employees as profits decline. These are not companies eager to embark on massive new capital projects in unstable jurisdictions.
What Happens Next: Three Scenarios for Venezuela’s Oil Future
Industry analysts and policy experts are mapping out possible paths forward, each with dramatically different implications.
Best Case: Phased Sanctions Relief With Investment Guarantees
In this scenario, the Trump administration negotiates a comprehensive framework that includes:
- Legislative sanctions modifications providing long-term certainty
- Bilateral investment treaties with international arbitration rights
- Gradual production targets tied to democratic reforms
- Settlement mechanisms for old expropriation claims
- PDVSA restructuring to allow operational autonomy
Timeline: 18-24 months to first new production; 5-7 years to reach 2 million barrels per day.
Francisco Monaldi suggests even a “trustworthy government” could boost production to 1.5-2 million barrels daily within two years by enabling existing operators like Chevron, Eni, and Repsol to increase spending within current licenses.
Most Likely: Limited Waivers With Slow Capital Deployment
This middle scenario reflects current reality: the administration grants specific licenses to particular companies under strict conditions, but comprehensive protections remain elusive.
Chevron expands modestly, perhaps doubling current output to 300,000 barrels daily over 3-4 years. ConocoPhillips and ExxonMobil secure debt settlements before committing new capital. Independent U.S. producers enter small projects in less complex areas.
Timeline: Gradual increases reaching 1.3-1.5 million barrels daily by 2030; still well below historical peaks.
The Council on Foreign Relations notes this scenario most closely matches how investments typically unfold in post-conflict petrostates—incremental, cautious, and constantly reassessed against political developments.
Worst Case: Talks Collapse, Status Quo Continues
If the Trump administration cannot provide adequate guarantees, or if Venezuela’s political situation deteriorates further, oil companies simply walk away.
Chinese and Russian state entities might deepen partnerships, but without the capital or technology to meaningfully boost production. Venezuela remains trapped producing 800,000-1 million barrels daily, with aging infrastructure continuing to decay.
Timeline: Indefinite stagnation; possible production declines to 500,000-700,000 barrels daily by 2030.
This scenario would represent a complete failure of Trump’s energy diplomacy but seems increasingly plausible given industry skepticism and adverse market conditions.
The Congressional Obstacle Course
Even if Trump convinces companies to invest, he faces a significant political problem: Congress.
Democrats immediately criticized the Venezuela operation as potentially illegal, questioning the military authority to capture a foreign head of state. Progressive members like Rep. Alexandria Ocasio-Cortez and Sen. Bernie Sanders condemned what they called “imperialism” and expressed concerns about repeating Iraq War mistakes.
But Trump’s challenges extend beyond predictable Democratic opposition. Several Republican senators, particularly those from oil-producing states, have raised questions about sanctions policy and whether Venezuela investments might undermine U.S. energy producers.
Secretary of State Marco Rubio faced skeptical lawmakers during classified briefings this week. One senator, speaking anonymously, told CNN: “There are more questions than answers, and I’m not convinced this administration has thought through the second- and third-order effects.”
The Center for Strategic and International Studies, a Washington think tank, published analysis suggesting any lasting Venezuela framework would require bipartisan legislative backing—an increasingly rare commodity in today’s polarized environment.
What Investment Guarantees Actually Mean in Practice
For readers unfamiliar with international oil contracts, understanding what companies are demanding requires explaining some technical structures.
Bilateral Investment Treaties (BITs): These government-to-government agreements establish protections for investors, including the right to international arbitration if a host country violates commitments. The U.S. has BITs with numerous countries, but Venezuela withdrew from many after Chávez’s nationalization.
Production Sharing Agreements (PSAs): Unlike traditional concessions where companies own the oil, PSAs allow governments to retain ownership while contractors receive a share of production as compensation. Iraq, Kurdistan, and other challenging markets use PSAs to attract investment while maintaining resource sovereignty.
Political Risk Insurance: Private insurers and multilateral agencies like MIGA (World Bank) offer coverage against expropriation, currency inconvertibility, and political violence. However, premiums for Venezuela would be extraordinarily high given its track record.
Sovereign Guarantee Agreements: The government issues binding commitments to compensate investors under specific conditions. These guarantees become enforceable debts if triggered—though collecting remains challenging, as ExxonMobil and ConocoPhillips can attest.
Companies want a combination of all four mechanisms, creating multiple layers of protection. Yet even this multilayered approach cannot eliminate political risk entirely, which explains the persistent hesitation.
The Bottom Line: Trump’s Energy Gambit Faces Long Odds
Six days after U.S. forces captured Nicolás Maduro, Donald Trump’s vision of American oil companies rapidly revitalizing Venezuela’s energy sector appears increasingly disconnected from commercial reality.
Oil executives want guarantees the administration cannot easily provide. Market conditions undermine investment economics. Congressional support remains uncertain. Venezuela’s physical infrastructure requires generational investment. And historical experience suggests promises made in crisis can evaporate when political winds shift.
Energy Secretary Wright has been more candid than Trump about these challenges. “We’re not going to be twisting or convincing anyone’s arms,” Wright told reporters. “We need to have that leverage and that control of those oil sales to drive the changes that simply must happen in Venezuela.”
Yet leverage alone won’t convince companies to risk billions. They need legal certainty, operational autonomy, market conditions that justify massive capital deployment, and confidence that any framework will outlast Trump’s presidency.
As of now, none of those conditions exist.
The industry’s message to Trump remains consistent: show us the guarantees, show us the profits, show us the stability—then we’ll talk about billions in investments. Until then, Venezuela’s 303 billion barrels might as well be on Mars.
Key Takeaways
For Investors: Venezuelan oil stocks and related companies will remain speculative until concrete investment frameworks emerge. Chevron has the clearest exposure, but near-term production increases appear limited.
For Energy Markets: Don’t expect Venezuelan supply to materially impact global oil balances before 2027-2028 at earliest. The current oversupply will persist regardless of Venezuela developments.
For Policy Watchers: Trump’s Venezuela strategy represents his administration’s most ambitious test of economic statecraft. Success or failure will influence how allies and adversaries view American power projection.
For Companies: The Friday White House meeting will be telling. If executives emerge with specific commitments, markets will react. More likely, they’ll offer cautious support while awaiting concrete protections.
The world’s largest proven oil reserves remain tantalizingly out of reach—not for lack of geological potential, but because history, economics, and politics create barriers that presidential bravado alone cannot overcome.


The SPDR S&P 500 ETF Trust (SPY) enters September 2026 trading around 7–14% above GuruFocus’s proprietary GF Value intrinsic-value estimate, depending on the week’s model inputs, with the index near record highs after an roughly 11–12% year-to-date gain. Unlike the rate-cut narrative that dominated markets earlier in the summer, the 10-year Treasury’s climb to 4.80% and hawkish Federal Reserve commentary now point toward markets pricing meaningful odds of a rate hike, not a cut, at this month’s FOMC meeting — a reversal that changes the valuation math for equities.
SPY Valuation Snapshot: Late August Into September 2026
| Date | SPY Price | GF Value™ (Intrinsic) | Overvaluation | GF Score™ | S&P 500 Level |
|---|---|---|---|---|---|
| Aug 6, 2026 | $768.31 | $685.35 | 12.1% | 85/100 | ~7,705 |
| Aug 10, 2026 | $773.26 | $702.96 | 10.0% | 86/100 | — |
| Aug 11, 2026 | $772.84 | $702.96 | 9.9% | 86/100 | — |
| Aug 17, 2026 | $776.34 | $705.76 | 10.0% | 86/100 | — |
| Aug 18, 2026 | $767.87 | $705.76 | 8.8% | 86/100 | — |
| Aug 19, 2026 | $769.45 | $705.76 | 9.0% | 86/100 | — |
| Aug 20, 2026 | $769.06 | $705.76 | 9.0% | 86/100 | — |
| Aug 25, 2026 | $765.67 | $715.63 | 7.0% | 86/100 | 7,665 (+11.4% YTD) |
| Aug 30, 2026 | $769.35 | $674.87 | 14.0% | 86/100 | — |
Note: GF Value estimates shift week to week as GuruFocus’s model incorporates new earnings, growth, and macro data — the fluctuation itself (from 7.0% to 14.0% overvalued within a single month) is a useful reminder that any single-day valuation snapshot is a moving target, not a fixed verdict.
| Rate/Bond Metric | Level (Sept 1, 2026) |
|---|---|
| 10-Year Treasury yield | 4.80% (highest since January 2025) |
| 30-Year Treasury yield | 5.28% |
| 2-Year Treasury yield | 4.39% |
| Market-implied odds of a Fed rate hike this month | ~68%, up from ~40% the prior week |
| SPY trailing P/E (TTM) | ~23.7x |
Sources: GuruFocus GF Value daily/weekly valuation notes (Aug 6–30, 2026); TradingEconomics, MacroMicro, and StreetStats Treasury yield data (Sept 1, 2026).
Deep Dive: A Valuation Picture Complicated by a Rate Story That Just Flipped
GF Value Says “Modestly to Meaningfully Overvalued,” But the Range Matters More Than Any Single Print
GuruFocus’s GF Value model — which blends historical trading multiples, business growth trends, and forward performance estimates into a single intrinsic-value estimate — has placed SPY anywhere from roughly 7% to 14% above fair value at various points across August 2026 alone. That’s not model inconsistency so much as it reflects genuinely volatile inputs: intrinsic value estimates move as new earnings data, Treasury yields, and macro releases feed the model, while the market price itself has been chopping in a roughly $765–$777 band.
The consistent signal across every reading, regardless of the exact overvaluation percentage: SPY’s GF Score — a composite of financial strength, profitability, growth, valuation, and momentum — has held steady in the 85–86 out of 100 range throughout the period. In plain terms, the model is saying the same thing every week: fundamentals underneath the index remain genuinely strong (profitability and growth sub-scores of 8/10), but the price paid for those fundamentals leaves a thin-to-negative margin of safety for new money entering at current levels.
The Bigger Story: The Fed Narrative Just Reversed
This is the detail most surface-level coverage of SPY valuation is missing entering September: the market’s rate-path assumption flipped over the course of late August. Earlier in the summer, a weak July jobs report and cooling CPI prints had markets leaning toward the possibility of rate cuts later in the year. By the final week of August, that had reversed. Fed Chair Warsh’s remarks at the Jackson Hole symposium reaffirmed a commitment to bringing inflation down, and Fed Governor Barr followed with comments that the central bank should be prepared to raise rates if inflation does not subside. The market reaction was immediate: odds of a 25-basis-point hike this month jumped from around 40% to roughly 68% within a single week, and the 10-year Treasury yield climbed for five consecutive sessions to reach 4.80% — its highest level since January 2025.
The proximate driver of the inflation concern is oil. Renewed geopolitical tensions have pushed crude prices higher, and rising energy costs are feeding directly into inflation expectations at a moment when the labor market — job openings edged higher in July, layoffs fell, and manufacturing expanded for an eighth straight month in August — is not showing the kind of softness that would normally take a hike off the table.
Why Rising Long-Term Yields Compress Equity Valuation Models
Every discounted-cash-flow-style valuation — including the general category of model GuruFocus’s GF Value falls into — is sensitive to the discount rate applied to future earnings. When the 10-year Treasury yield rises from a level closer to 4.3% (its trailing 12-month average) to a fresh cycle high of 4.80%, the “risk-free” comparison rate against which equity earnings yields are judged rises with it. All else equal, a higher discount rate lowers the intrinsic value estimate for the same stream of future earnings — which is part of why GF Value estimates for SPY have generally trended toward higher overvaluation readings as yields have climbed through August, even as the S&P 500 itself continued grinding higher.
The Seasonal Overlay: September’s Historical Track Record
Independent of valuation or rates, the calendar itself carries a well-documented pattern: the back half of September has historically been the weakest stretch of the trading year for the S&P 500, producing slightly negative average returns more often than any other multi-week period. That seasonal headwind, layered on top of a rate environment that just turned more hawkish and a valuation model flashing high-single to low-double-digit overvaluation, is the combination coverage of SPY heading into September 2026 should actually be weighing — not any single data point in isolation.
What a 23.7x Trailing P/E Actually Tells You
SPY’s trailing twelve-month P/E of approximately 23.7x sits meaningfully above long-run historical averages for the index (commonly cited in the high teens), though comparisons are complicated by the absence of a readily available 5-year median P/E in the underlying data used for this analysis — a data-availability gap GuruFocus itself has flagged in several of its own valuation notes. Investors should treat any single trailing-multiple comparison as one input among several (GF Value, GF Score, rate environment, seasonal pattern) rather than a standalone verdict.
Actionable Takeaways for Investors
- Don’t anchor to a single GF Value overvaluation percentage. The swing from 7.0% to 14.0% overvalued within the same month shows the model is sensitive to short-term inputs; look at the trend and the GF Score (steady at 85–86) together, not one week’s headline number.
- Track the 10-year Treasury yield as a leading valuation signal. A continued climb toward or past 4.80–5.00% would mechanically pressure equity valuation models further; a reversal back toward the 4.30% trailing average would ease that pressure.
- Reassess the “rate cut” assumption baked into your portfolio. If your equity allocation was built assuming Fed easing later in 2026, the shift toward hike odds of ~68% for this month’s meeting is a material change worth revisiting with a financial advisor.
- Respect September seasonality without overreacting to it. Historical weak-September patterns are a real, well-documented statistical tendency, not a guarantee — use it as a reason for disciplined position sizing rather than a market-timing signal on its own.
- Watch oil prices as the connective tissue between geopolitics, inflation, and equity valuation. The current inflation concern feeding into hike odds is substantially an energy-price story; a de-escalation in the geopolitical tensions driving crude higher would likely ease both bond yields and equity valuation pressure simultaneously.
Frequently Asked Questions
Is the S&P 500 overvalued right now? By GuruFocus’s GF Value metric, SPY has traded between roughly 7% and 14% above its estimated intrinsic value at various points across August 2026, with a GF Score of 85–86 out of 100 indicating strong underlying fundamentals despite the valuation premium — the honest answer is “modestly to meaningfully” overvalued depending on which week’s model reading you use, not overvalued by one fixed number.
Will the Federal Reserve raise or cut interest rates in September 2026? As of early September 2026, market pricing has shifted toward pricing in meaningful odds (around 68%) of a rate hike rather than a cut, reversing the rate-cut expectations that dominated earlier in the summer, driven by hawkish Fed commentary at Jackson Hole and rising oil-driven inflation concerns.
Why did the 10-year Treasury yield hit 4.80% in September 2026? The 10-year Treasury yield climbed for five consecutive sessions to reach 4.80% — its highest level since January 2025 — driven by rising oil prices amid renewed geopolitical tensions and hawkish signals from Federal Reserve officials suggesting a rate hike may be needed to control inflation.
How does September seasonality typically affect the S&P 500? Historically, the latter half of September has been the weakest multi-week stretch of the trading year for the S&P 500, often producing slightly negative average returns, though this is a statistical tendency rather than a reliable predictor for any specific year.
Analysis
FHS Saudi Arabia 2026 Opens in Riyadh, Drawing Investors Representing Nearly $5 Trillion in Assets
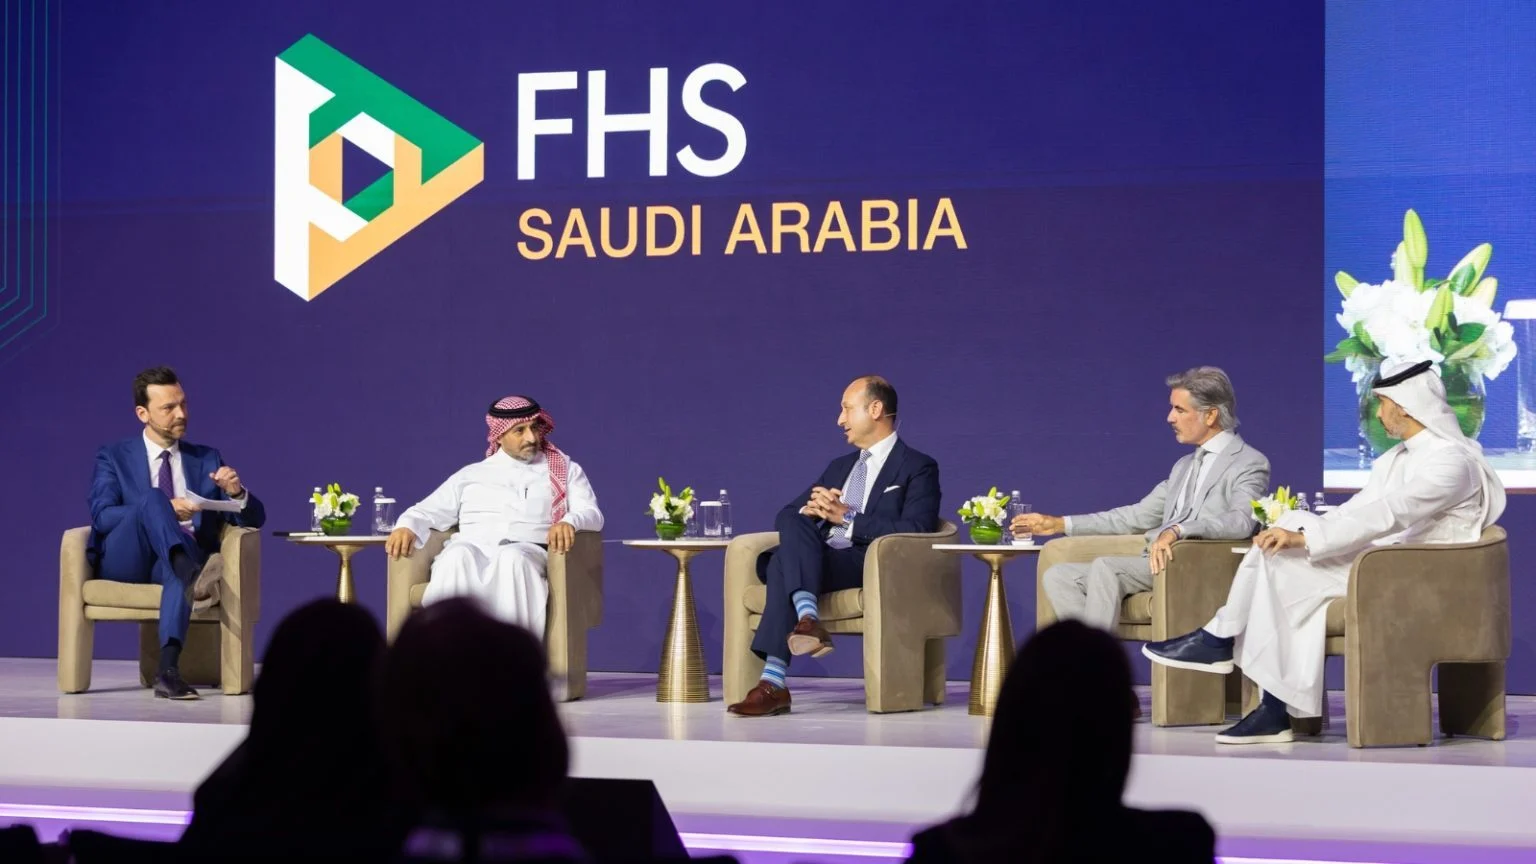
The Future Hospitality Summit (FHS) Saudi Arabia 2026 opens this week at the Mandarin Oriental Al Faisaliah in Riyadh, running June 22–24 and positioning itself as the Kingdom’s leading hospitality deal-making forum for the year. Organizers say attendees represent investors managing roughly $4.99 trillion in assets under management, underscoring the scale of capital now circling Saudi Arabia’s hospitality and tourism investment pipeline.
The timing is notable. The summit arrives even as the broader Middle East travel sector works through a difficult stretch — regional hotel occupancy and air capacity both fell sharply earlier in the year amid conflict-related disruption. Saudi Arabia’s hospitality investment push has continued largely undeterred, reflecting the Kingdom’s long-term tourism diversification strategy under Vision 2030, which has driven sustained hotel development, giga-project investment, and international brand expansion regardless of near-term regional volatility.
A Magnet for Global Capital
FHS Saudi Arabia has grown into one of the region’s most closely watched investment gatherings, bringing together hotel owners, operators, private equity investors, and sovereign capital to negotiate deals and discuss the Kingdom’s pipeline of new developments. The scale of capital represented by attendees — nearly $5 trillion — signals continued confidence among major institutional investors in Saudi Arabia’s hospitality growth story, even as some neighboring markets navigate near-term demand volatility.
Part of a Broader Investment Push
The summit’s opening coincides with a wider industry conversation about how governments can attract and retain private tourism investment. The World Travel & Tourism Council recently unveiled a seven-principle framework aimed at giving governments a practical roadmap — covering legal stability, fiscal incentives, and master planning — for courting exactly this kind of capital. Saudi Arabia’s continued ability to draw large-scale investor attendance to Riyadh suggests its approach is, for now, resonating with the institutional investment community.
What to Watch
Deal announcements, new hotel brand entries, and updates on giga-project hospitality components are expected to dominate headlines over the three-day event, with global hotel groups likely to use the summit to detail expansion plans across the Kingdom’s tourism corridors.
Investing 101
Gaming Giant’s Bold Gamble: Why Investors are Devouring Risky EA Debt Amid Geopolitical Crosscurrents
Investors are aggressively snapping up debt for Electronic Arts’ historic $55bn take-private, signaling resilient credit markets despite geopolitical tensions and AI disruption. Explore the EA LBO’s financial engineering, cost savings, and the appetite for risky video game financing in 2026.
Introduction: The Unyielding Allure of High-Yield
The world of high finance rarely pauses for breath, even as geopolitical headwinds gather and technological disruption reshapes industries. Yet, the recent $55 billion take-private of video game titan Electronic Arts (EA) has delivered a masterclass in market resilience, demonstrating an almost insatiable investor appetite for leveraged debt—even when tied to a complex, globally-infused transaction. Led by Saudi Arabia’s Public Investment Fund (PIF), Silver Lake, and Affinity Partners, this landmark deal, poised to redefine the gaming M&A landscape, has seen its $18-20 billion debt package met with overwhelming demand, proving that the pursuit of yield often eclipses lingering doubts.
This isn’t merely another private equity mega-deal; it’s a bellwether for global credit markets in early 2026. JPMorgan-led bond deals, designed to finance one of the largest leveraged buyouts in history, have drawn over $25 billion in orders, far surpassing their target size. This aggressive investor embrace of what many consider risky debt, particularly given the backdrop of Middle East tensions and concerns over AI’s impact on software, underscores a fascinating dichotomy: a cautious macroeconomic outlook juxtaposed with an audacious hunt for returns in stable, cash-generative assets. The question isn’t just how this was financed, but why investors dove in with such conviction, and what it signals for the year ahead.
The Anatomy of a Mega-Buyout: EA’s Financial Engineering
At an enterprise value of approximately $55 billion, the Electronic Arts take-private deal stands as the largest leveraged buyout on record, eclipsing the 2007 TXU Energy privatization. The financing structure is a finely tuned orchestration of equity and debt, designed to maximize returns for the acquiring consortium while appealing to a broad spectrum of debt investors.
Equity & Debt Breakdown
The EA $55bn LBO is funded through a combination of substantial equity and a significant debt tranche:
- Equity Component: Approximately $36 billion, largely comprising cash contributions from the consortium partners, including the rollover of PIF’s existing 9.9% stake in EA. PIF is set to own a substantial majority, approximately 93.4%, with Silver Lake holding 5.5% and Affinity Partners 1.1%.
- Debt Package: A substantial $18-20 billion debt package, fully committed by a JPMorgan-led syndicate of banks. This makes it the largest LBO debt financing post-Global Financial Crisis.
Unpacking the Debt Tranches: Demand & Pricing
The sheer scale of demand for this EA acquisition financing has been striking. The initial $18 billion debt offering, which included both secured and unsecured tranches, quickly swelled to over $25 billion in investor orders. This oversubscription highlights a strong market appetite for gaming-backed paper.
Key components of the debt include:
- Leveraged Loans: A cross-border loan deal totaling $5.75 billion launched on March 16, 2026, comprising a $4 billion U.S. dollar loan and a €1.531 billion ($1.75 billion) euro tranche.
- Pricing: Term Loan Bs (TLBs) were guided at 350-375 basis points over SOFR/Euribor, with a 0% floor and a 98.5 Original Issue Discount (OID). This discounted pricing suggests lenders were baking in some risk, yet the demand remained robust.
- Secured & Unsecured Bonds: The financing also features an upsized $3.25 billion term loan A, an additional $6.5 billion of other dollar and euro secured debt, and $2.5 billion of unsecured debt. While specific high-yield bond pricing hasn’t been detailed, market intelligence suggests secured debt at approximately 6.25-7.25% and unsecured north of 8.75%, reflective of the leverage profile.
The Deleveraging Path: Justifying a 6x+ Debt/EBITDA
Moody’s projects that EA’s gross debt will increase twelve-fold from $1.5 billion, pushing pro forma leverage (total debt to EBITDA) to around eight times at closing. Such high leverage ratios typically raise red flags, but the consortium’s pitch centers on EA’s robust cash flows and significant projected cost savings.
Three Pillars Justifying the Leverage
- Stable Cash Flows from Core Franchises: EA boasts an enviable portfolio of consistently profitable franchises, including FIFA (now EA Sports FC), Madden NFL, Apex Legends, and The Sims. These titles generate predictable, recurring revenue streams, particularly through live service models and annual updates, which underpin the company’s financial stability—a critical factor for debt investors.
- Strategic Cost Savings & Operational Efficiencies: The new owners have outlined an aggressive plan for $700 million in projected annual cost savings. This includes:
- R&D Optimization: $263 million from reclassifying R&D expenses for major titles like Battlefield 6 and Skate as one-time costs, now that they are live and generating revenue.
- Portfolio Review: $100 million from a strategic review of the game portfolio.
- AI Tool Integration: $100 million from leveraging AI tools for development and operations.
- Organizational Streamlining: $170 million from broader organizational efficiencies.
- Public Company Cost Removal: $30 million saved by no longer incurring costs associated with being a public entity.
These add-backs significantly bolster adjusted EBITDA figures, making the debt package appear more manageable to prospective lenders. Moody’s expects leverage to decrease to five times by 2029.
- Untapped Growth Potential in Private Ownership: Freed from quarterly earnings pressure, EA’s management can pursue longer-term strategic initiatives and R&D without the immediate scrutiny of public markets. This is particularly appealing for a company operating in an industry prone to rapid innovation and large, multi-year development cycles. The consortium’s diverse networks across gaming, entertainment, and sports are expected to create opportunities to “blend physical and digital experiences, enhance fan engagement, and drive growth on a global stage”.
Geopolitical Currents and the Appetite for Risky Debt
The influx of capital into the Electronic Arts bond deals is particularly noteworthy given the complex geopolitical backdrop of early 2026. Global markets are navigating sustained tensions in the Middle East, the specter of trade tariffs, and the disruptive force of artificial intelligence. Yet, these factors have not deterred investors from snapping up debt to finance Electronic Arts’ $55bn take-private.
The Saudi PIF Factor: Geopolitical Implications
The prominent role of Saudi Arabia’s Public Investment Fund (PIF) as the lead equity investor introduces a significant geopolitical dimension. The PIF, managing over $925 billion in assets, views this acquisition as a strategic move to establish Saudi Arabia as a global hub for games and sports, aligning with its “Vision 2030” diversification efforts. PIF’s deep pockets and long-term investment horizon offer stability often attractive to private equity deals.
However, the involvement of a sovereign wealth fund, particularly one with ties to Jared Kushner’s Affinity Partners, has not been without scrutiny. Concerns about national security risks, foreign access to consumer data, and control over American technology (including AI) have been voiced by organizations like the Communications Workers of America (CWA), who urged federal regulators to scrutinize the deal. Despite these geopolitical and regulatory considerations, the debt market demonstrated a remarkable willingness to participate. This indicates that the perceived financial stability and growth prospects of EA outweighed concerns tied to the source of equity capital.
AI Disruption and Market Confidence
The gaming industry, like many sectors, faces potential disruption from AI. Yet, EA itself projects $100 million in cost savings from AI tools, signaling a strategic embrace rather than fear of the technology. This forward-looking approach to AI, coupled with the inherent stability of established gaming franchises, likely contributed to investor confidence. In a volatile environment, proven entertainment IP acts as a relatively safe harbor.
The successful placement of this jumbo financing also suggests that while some sectors (like software) have seen “broader risk-off sentiment” due to AI uncertainty, the market distinguishes between general software and robust, content-driven interactive entertainment.
Broader Implications for Gaming M&A and Private Equity
The EA LBO is more than an isolated transaction; it’s a powerful signal for the broader M&A landscape and the future of private equity.
A Return to Mega-LBOs?
After a period where massive leveraged buyouts fell out of favor post-Global Financial Crisis, the EA deal marks a definitive comeback. It “waves the green flag on sponsors resuming mega-deal transactions,” indicating that easing borrowing costs and renewed boardroom confidence are aligning to facilitate large-cap M&A. The success of this deal, especially the oversubscription of its debt tranches, could embolden other private equity firms to pursue similar-sized targets in industries with reliable cash flows. This is crucial for private-equity debt appetite in 2026.
Creative Independence Post-Delisting
While private ownership offers freedom from public market pressures, it also introduces questions about creative independence. Historically, private equity has been associated with aggressive cost-cutting and a focus on short-term profits. For a creative industry like gaming, this can be a double-edged sword. While the stated goal is to “accelerate innovation and growth”, some within EA have expressed concern about potential workforce reductions and increased monetization post-acquisition. The challenge for the new owners will be to balance financial optimization with the nurturing of creative talent and IP development crucial for long-term success.
What it Means for 2027: Scenarios and Ripple Effects
As the EA $55bn take-private moves towards its expected close in Q1 FY27 (June 2026), its ripple effects will be closely watched by analysts and investors alike.
- Post-Deal EA Strategy: Under private ownership, expect EA to double down on its most successful franchises and potentially explore new growth vectors less scrutinized by quarterly reports. Strategic investments in areas like mobile gaming, esports, and potentially new IP development could accelerate. The projected cost savings will likely be reinvested to fuel growth or rapidly deleverage.
- Valuation Multiples: The deal itself sets a new benchmark for valuations in the gaming sector, particularly for companies with strong IP and predictable revenue streams. This could influence future M&A activities involving peers like Activision Blizzard (though now part of Microsoft) or Take-Two Interactive, raising their perceived floor valuations.
- Credit Market Confidence: The overwhelming investor demand for EA’s debt signals a powerful confidence in the leveraged finance markets, particularly for well-understood, resilient businesses. If EA successfully executes its deleveraging and growth strategy post-buyout, it will further validate the market’s willingness to finance large, complex LBOs, even amidst global uncertainty. This could pave the way for more “risky debt” deals tied to stable, high-quality assets.
- Geopolitical Influence in Tech: The PIF’s leading role solidifies the trend of sovereign wealth funds actively participating in global technology and entertainment sectors. This influence will continue to shape discussions around regulatory oversight, national interests, and the evolving landscape of global capital flows.
The investors snapping up debt to finance Electronic Arts’ $55bn take-private aren’t just betting on a video game company; they’re wagering on the enduring power of stable cash flows, strategic cost management, and a robust credit market willing to absorb risk for attractive yields. In a world grappling with uncertainty, the virtual battlefields of EA’s franchises offer a surprisingly solid ground for real-world financial gains.

Diesel Prices 2026–2027: Why Cheaper Crude May Not Mean Cheap Fuel

2027 Social Security COLA: Key Details and Dates

KSE-100 Sees Major Drop Post-SBP Rate Hike

Big Tech’s AI Spending Test: Can Revenue Catch Up With Capital Expenditure?

AI Infrastructure Investment Strategies for 2026

Pakistan Freelancers Tax 2026: Payments, Documentation and Formal Growth

Strait of Hormuz Crisis: What the Latest Tanker Attacks Mean for Oil, Shipping and Global Trade

AI Customer Service in 2026: What’s Working, What’s Failing, and What to Buy

Open a Savings Account Online: How to Actually Earn 10x the National Average Rate

Global Housing Market 2026: Where Prices Rise, Where They Don’t

PSX and KSE-100 Record Highs: An Insider’s Guide to Pakistan Stocks

So Delicious Dessert Recall: Affected Products, FDA Guidelines, and Consumer Action

Pakistan’s Current Account Deficit Narrows Sharply to $98 Million in August 2026

Japan Eyes 3.5% Defense Spending: What It Means for Bonds, Stocks, and the BOJ

Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities

Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World

Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns

China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech

What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact

15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025

How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide

Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide

Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
-
 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
 Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
 Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
 Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
 AI11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
 Exports11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025