
Global Economy
Pakistan’s $250M Panda Bond: A Calculated Bet on Beijing—Or a Currency Time Bomb?

How Pakistan’s first yuan-denominated bond exposes the rupee to a new geopolitical and financial calculus
When Finance Minister Muhammad Aurangzeb announced in December that Pakistan would issue its first Panda Bond in January 2026—raising $250 million from Chinese investors—the headlines trumpeted financial diversification. But beneath the diplomatic niceties lies a far more consequential question: Is Pakistan trading one form of dollar dependency for a potentially more dangerous yuan exposure, and what does this mean for the already fragile Pakistani rupee?
The answer matters not just for Islamabad’s 240 million citizens, but for every emerging economy watching China’s expanding financial footprint across the developing world. As Western capital markets remain skeptical of Pakistan’s fiscal stability, this yuan gambit represents both opportunity and risk—a high-stakes wager that could either stabilize the rupee or accelerate its decline.
The Panda Bond Explained: More Than Just Another Loan
A Panda Bond is not your typical international debt instrument. Unlike Eurobonds denominated in dollars or euros, these are yuan-denominated bonds issued within China’s domestic market by foreign entities. Pakistan will borrow directly in Chinese currency, selling debt to Chinese institutional investors who are eager to diversify portfolios and support Beijing’s broader strategy of internationalizing the renminbi.
The mechanics are deceptively simple: Pakistan issues bonds worth approximately 1.8 billion yuan, Chinese investors buy them, and three years later Pakistan must repay both principal and interest—all in yuan. The inaugural $250 million tranche is just the opening salvo in a $1 billion program that Finance Ministry officials confirmed is already preparing a “Panda Series II” issuance.
What makes this significant is the currency risk transfer. While dollar-denominated debt exposes Pakistan to Federal Reserve policy and global liquidity conditions, yuan debt ties Pakistan’s fortunes to the People’s Bank of China’s monetary decisions and the bilateral exchange rate between the rupee and yuan—a relationship that has been anything but stable.
The Rupee’s Precarious Position: Why Currency Matters Now More Than Ever
To understand the Panda Bond’s implications, consider Pakistan’s currency dynamics heading into 2026. The rupee currently trades around 280 to the dollar, having depreciated roughly 1% over the past year despite claims of stabilization. More critically, Pakistan’s foreign exchange reserves—while improved to approximately $20 billion after recent IMF disbursements—still cover barely three months of imports, a razor-thin buffer that leaves the currency vulnerable to external shocks.
Pakistan’s forex reserves crossed $20 billion in December 2025 after receiving roughly $1.2 billion from the IMF, but this improvement masks deeper structural vulnerabilities. The country faces $1 billion in Eurobond repayments in April 2026, with total external debt servicing obligations that consume more than 100% of annual tax revenue.

Here’s where the Panda Bond calculus gets complicated. Pakistan earns most of its foreign exchange through exports priced in dollars and remittances sent home in various currencies—but predominantly converted through the dollar. Now it’s adding debt obligations in yuan, creating a triple currency exposure: earning in dollars and rupees, while owing dollars, euros, and increasingly, yuan.
The historical correlation between the Pakistani rupee and Chinese yuan offers little comfort. Over the past five years, the yuan has fluctuated between 6.2 and 7.3 to the dollar, while the rupee has steadily depreciated from roughly 160 to 280 against the greenback. If the yuan strengthens against both the dollar and rupee—as Chinese policymakers desire for international credibility—Pakistan’s debt servicing burden in rupee terms could spike dramatically.
Consider a scenario: If Pakistan borrowed 1.8 billion yuan when the exchange rate was 40 rupees per yuan, but must repay when it’s 50 rupees per yuan, the real cost in local currency terms jumps 25%. That’s not theoretical risk—it’s the lived reality of currency mismatch that has devastated emerging market borrowers from Turkey to Argentina.
The China Debt Overhang: Already $30 Billion and Growing
Pakistan’s Panda Bond doesn’t exist in isolation—it’s the latest chapter in a debt relationship with Beijing that has already reached concerning proportions. China-Pakistan Economic Corridor financing now constitutes approximately $30 billion of Pakistan’s external debt, making China the largest bilateral creditor by far.
The CPEC megaproject, launched in 2013 with promises of transformative infrastructure and energy generation, has delivered some tangible benefits: 14 power projects have added nearly 8,700 megawatts of electricity production capacity. But these gains came at steep cost. The power plants rely on imported coal from Indonesia, South Africa, and Australia, increasing Pakistan’s fuel import bill while producing expensive electricity that consumers struggle to afford. By July 2025, unpaid bills to Chinese power companies had reached $1.5 billion, violating contractual obligations and straining diplomatic relations.
Of the 90 planned CPEC projects, only 38 have been completed. The flagship Gwadar Port operates on a limited scale. Security concerns have forced delays and cancellations, with militant attacks targeting Chinese personnel feeding Beijing’s growing wariness about expanding exposure to Pakistan.
The Panda Bond, in this context, represents both a vote of confidence and a potential pressure point. Chinese officials reportedly showed “strong interest” in the bond during investor engagement, according to Finance Ministry briefings. But investor appetite doesn’t necessarily translate to favorable long-term outcomes for Pakistan’s currency stability.
The IMF Tightrope: Balancing Beijing and Washington
Pakistan’s economic policy is currently shaped by two competing gravitational forces: a $7 billion IMF Extended Fund Facility approved in September 2024, and deepening financial integration with China. The IMF program requires fiscal consolidation, revenue enhancement, privatization of state-owned enterprises, and exchange rate flexibility—measures designed to build Pakistan’s capacity to manage debt independently.
The IMF’s second review, completed in December 2025, released approximately $1 billion under the Extended Fund Facility and $200 million under the Resilience and Sustainability Facility, bringing total IMF disbursements to $3.3 billion. These funds are critical for maintaining reserve buffers and signaling creditworthiness to international markets.
But here’s the tension: IMF programs emphasize debt transparency and sustainability analysis, including scrutiny of bilateral lending terms. China’s lending practices—often characterized by opaque contracts, collateral requirements, and policy conditionalities—have raised concerns among Western creditors about Pakistan’s ability to meet all obligations simultaneously.
The Panda Bond, denominated in yuan and sold exclusively to Chinese investors, falls into a regulatory grey zone. While technically market-based financing, it deepens financial interdependence with Beijing at precisely the moment when IMF staff are pushing for broader creditor base diversification. Pakistan owes roughly 22-30% of its $135 billion external debt to China—a concentration risk that debt sustainability analyses flag as problematic.
If Pakistan were forced into debt restructuring—not an implausible scenario given its thin reserve coverage and massive rollover requirements—would Chinese bondholders accept haircuts alongside Paris Club creditors? The lack of historical precedent creates uncertainty that could, ironically, weaken the rupee by spooking other investors.
Currency Hedging: The Hidden Cost Nobody’s Discussing
One critical detail buried in the technical aspects of Panda Bond issuance: currency hedging costs. Pakistan doesn’t generate significant yuan revenues domestically, meaning it must either earn yuan through exports to China, swap currencies in financial markets, or purchase yuan using dollar reserves when debt comes due.
Each option carries costs and risks. China-Pakistan bilateral trade reached $23 billion in 2023, but Pakistan runs a massive deficit—importing far more from China than it exports. This means Pakistan can’t naturally generate sufficient yuan through trade to service Panda Bond obligations.
Currency swap markets for PKR/CNY are thin and expensive compared to PKR/USD markets. Hedging a $250 million yuan obligation over three years could cost anywhere from 2-5% annually, depending on market conditions and counterparty availability. That’s a substantial hidden expense that doesn’t appear in initial borrowing cost calculations.
Without proper hedging, Pakistan faces direct currency risk. With hedging, it faces potentially prohibitive costs that erode any interest rate advantage the Panda Bond might offer over dollar-denominated alternatives. Finance Ministry officials have not publicly disclosed the hedging strategy, leaving analysts to wonder whether this risk is being managed or simply accepted.
The rupee’s stability—or instability—becomes central to this calculation. A 10% rupee depreciation against the yuan would increase debt servicing costs by 10% in local currency terms. Given the rupee’s track record of steady devaluation, this isn’t alarmist speculation—it’s mathematical probability requiring serious policy attention.
The Geopolitical Dividend: What Beijing Really Wants
To fully understand the Panda Bond’s implications for Pakistan’s currency, we must acknowledge the geopolitical dimension. China’s encouragement of Panda Bond issuances isn’t purely altruistic—it serves Beijing’s strategic objective of yuan internationalization.
Currently, the yuan accounts for roughly 3% of global foreign exchange reserves and about 2% of international payments, far below the dollar’s 60% and 40% shares respectively. Every Panda Bond issued by a sovereign borrower like Pakistan legitimizes yuan-denominated debt, creates precedent for other emerging economies, and gradually builds the infrastructure for yuan-based international finance.
For Pakistan, tapping Chinese capital markets demonstrates political alignment with Beijing at a time of intensifying US-China rivalry. The timing is particularly notable: as Pakistan navigates relationships with both Washington and Beijing, financial choices send signals. Issuing dollar-denominated Eurobonds tilts toward Western markets; issuing Panda Bonds signals comfort with Chinese financial integration.
This political calculus has currency implications. If Pakistan is perceived as moving decisively into China’s financial orbit, Western investors may demand higher risk premiums on dollar-denominated Pakistani debt, effectively raising borrowing costs across the board. Conversely, if Chinese support is seen as a backstop against default risk, it could paradoxically stabilize the rupee by reducing overall risk perception.
The outcome depends on credibility. Does China’s willingness to buy Pakistani Panda Bonds indicate genuine confidence in economic reforms, or is it diplomatic lending that prioritizes geopolitical goals over financial returns? Market participants are watching closely, and their conclusions will influence capital flows that directly impact the rupee’s value.
Regional Precedents: Lessons From Other Emerging Markets
Pakistan isn’t the first emerging economy to issue Panda Bonds. Egypt issued Africa’s first Sustainable Panda Bond worth 3.5 billion yuan in 2023, backed by guarantees from the African Development Bank and Asian Infrastructure Investment Bank. The AAA-rated guarantees were crucial for securing favorable terms and crowding in investors.
Pakistan’s Panda Bond carries no such multilateral guarantees. While the Finance Ministry secured “approvals from multilateral partners,” these appear to be non-objection clearances rather than credit enhancements. Without guarantee backing, Pakistan must rely on its own credit profile—currently rated ‘CCC+’ by S&P and ‘Caa3’ by Moody’s, deep in junk territory indicating substantial credit risk.
The Egyptian precedent also illustrates potential benefits: diversified funding sources, access to Chinese savings pools, and demonstration effects that can improve subsequent market access. Egypt successfully used Panda Bond proceeds for sustainable development objectives under a transparent framework that helped rebuild investor confidence.
But Egypt’s macroeconomic fundamentals differ significantly from Pakistan’s. Egypt’s external debt-to-GDP ratio, while elevated, isn’t concentrated as heavily with a single creditor. Its foreign exchange reserves, though pressured, weren’t as perilously thin at the time of issuance. These baseline differences matter for how currency markets interpret similar financing decisions.
More cautionary tales come from countries like Sri Lanka, which became heavily indebted to China through infrastructure projects and faced severe balance of payments crises when dollar earnings couldn’t cover debt servicing. While Sri Lanka didn’t issue Panda Bonds specifically, its experience with concentrated Chinese debt exposure offers sobering lessons about currency vulnerability and loss of policy autonomy.
The State Bank’s Dilemma: Monetary Policy in a Yuan-Exposed World
For Pakistan’s central bank, the Panda Bond creates new complications in an already challenging mandate. The State Bank of Pakistan has cut policy rates by 1,100 basis points since June 2025, bringing rates down as inflation moderated to low single digits. This easing cycle aims to stimulate economic growth while maintaining currency stability.
But yuan-denominated debt adds a new variable to the policy equation. If the State Bank needs to defend the rupee through interest rate increases—whether to combat inflation resurgence or prevent capital flight—higher domestic rates could paradoxically worsen the yuan debt burden by widening interest rate differentials and attracting speculative flows that create volatility.
The central bank’s exchange rate flexibility, a key IMF program requirement, also becomes more constrained. With significant yuan obligations coming due in 2029, the State Bank must consider not just the rupee-dollar rate, but also the rupee-yuan cross rate. Smoothing rupee volatility against one currency might inadvertently create volatility against the other, complicating monetary policy implementation.
Foreign exchange market operations become more complex too. The State Bank typically intervenes using dollar reserves to influence the rupee-dollar rate. Managing yuan exposure may require developing yuan liquidity management tools, currency swap facilities, and deeper yuan foreign exchange markets—capabilities that Pakistan’s financial infrastructure currently lacks.
These technical challenges have real economic consequences. If the central bank is constrained in its policy choices by external debt composition, it loses degrees of freedom in responding to domestic shocks. That reduced policy flexibility can itself become a source of currency instability, as markets recognize the central bank’s limited room for maneuver.
The $1 Billion Question: What Happens After January?
The $250 million inaugural tranche is explicitly framed as the first step in a $1 billion Panda Bond program. Finance Ministry officials confirmed that “preparatory work for subsequent issuances under Panda Series II is already underway,” with Chinese regulators fully briefed on the multi-tranche structure.
This scaling ambition raises the stakes considerably. A quarter-billion dollar yuan obligation is manageable, even for Pakistan’s strained finances. But $1 billion in yuan debt—roughly 7 billion yuan at current exchange rates—represents a material shift in debt composition that could influence currency market dynamics.
Each subsequent Panda Bond issuance will face market scrutiny about how Pakistan managed the previous one. If early tranches are serviced smoothly, with stable exchange rates and no hedging issues, subsequent issuances become easier and potentially cheaper. But if problems emerge—payment difficulties, currency pressures, or policy conflicts with other creditors—the Panda Bond program could become a source of financial stress rather than relief.
The timing of future tranches also matters. Issuing during periods of rupee strength locks in better exchange rates for repayment. Issuing during currency weakness or reserve pressure could signal desperation, triggering adverse market reactions that become self-fulfilling. Pakistan’s track record of economic volatility suggests future issuances won’t all occur under favorable conditions.
There’s also the question of investor appetite beyond the inaugural issuance. Chinese institutional investors buying the first Panda Bond are making a bet not just on Pakistan’s creditworthiness, but on the bilateral relationship’s durability. Each subsequent issuance tests that confidence anew. One security incident targeting Chinese nationals, one CPEC project cancellation, one political shift in Islamabad—any could chill investor sentiment and make future issuances difficult or impossible.
The Unspoken Alternative: What If Pakistan Had Chosen Differently?
It’s worth examining the counterfactual: What if Pakistan had raised $250 million through traditional Eurobonds instead? The answer illuminates what’s truly at stake in the Panda Bond decision.
Dollar-denominated Eurobonds would maintain Pakistan’s existing currency risk profile without adding yuan exposure. The country already earns dollars through exports and remittances, creating natural revenue streams to service dollar debt. Hedging isn’t necessary—the currency match is inherent in the business model of a dollar-dependent economy.
But Eurobond yields for Pakistani sovereign debt have hovered between 8-12% in recent years, reflecting elevated credit risk. Panda Bond interest rates, while not yet disclosed publicly, are likely lower—perhaps 5-7% given Chinese government policy support for such issuances. That spread represents real savings: on $250 million over three years, a 3% interest rate difference saves roughly $22 million in interest payments.
However, this comparison ignores currency risk. A 10% rupee depreciation against the yuan (entirely plausible given historical volatility) would increase the real cost of Panda Bond servicing by $25 million—wiping out the interest savings and then some. Factor in hedging costs, and the supposed advantage of cheaper Chinese financing evaporates quickly.
The alternative comparison is actually with Chinese bilateral loans, which Pakistan has accessed extensively through CPEC and other channels. Bilateral loans typically carry concessional terms but also policy conditions—project approvals, contractor selection, strategic access agreements. Panda Bonds, being market instruments, theoretically avoid such conditionalities.
But do they really? The bonds are sold exclusively to Chinese investors, priced in yuan, governed by Chinese law, and subject to Chinese regulatory oversight. While legally distinct from bilateral loans, Panda Bonds create dependencies that policy conditions might also impose. The difference is one of form rather than substance—and currency risk remains constant across both.
Three Scenarios for the Rupee: Where We Go From Here
Looking ahead to 2026-2029, three plausible scenarios emerge for how the Panda Bond shapes rupee dynamics:
Best Case: Strategic Stabilization
Pakistan successfully uses Panda Bond proceeds to finance productive investments that generate returns. Economic reforms under the IMF program take hold, export growth accelerates, and forex reserves build to comfortable levels above $30 billion. The yuan obligation becomes one manageable component of a diversified debt portfolio. Currency markets interpret Chinese investor confidence as validation, reducing risk premiums and stabilizing the rupee between 275-285 to the dollar. Yuan-rupee rates remain relatively stable, and Pakistan successfully rolls over Panda Bonds at maturity without stress.
Probability: 25%. This requires nearly everything to go right—sustained political stability, disciplined fiscal policy, favorable global conditions, and no major external shocks. Pakistan’s recent history suggests this optimistic scenario is possible but unlikely.
Base Case: Muddling Through With Elevated Risk
The Panda Bond provides temporary liquidity relief but doesn’t fundamentally alter Pakistan’s fiscal trajectory. Structural reforms progress slowly, growth remains anemic around 2-3%, and debt sustainability concerns persist. The rupee continues gradual depreciation to 300-320 against the dollar, with periodic volatility spikes. Yuan debt servicing becomes more expensive in local currency terms but remains manageable through reserve drawdowns and additional borrowing. Each Panda Bond rollover requires careful negotiation, and Pakistan alternates between IMF programs and bilateral support packages.
Probability: 50%. This represents continuity with Pakistan’s recent economic management—avoiding disaster but never quite achieving breakthrough. Currency pressure remains chronic but controlled.
Worst Case: Currency Crisis and Debt Distress
A confluence of negative shocks—oil price spike, political instability, major security incident, or adverse global monetary tightening—triggers a balance of payments crisis. Forex reserves plummet below $10 billion, the rupee crashes toward 350-400 to the dollar, and Pakistan faces difficulty servicing all external obligations. The yuan debt, now much more expensive in rupee terms, becomes a flashpoint. Chinese bondholders demand repayment while Pakistan lacks yuan or the dollars to convert. Emergency IMF support requires debt restructuring negotiations that include Chinese creditors. The rupee destabilizes further as market confidence collapses.
Probability: 25%. Pakistan has weathered similar crises before, but each one leaves the economy more vulnerable to the next. The addition of yuan-denominated obligations adds a new dimension of complexity to crisis management.
Policy Recommendations: What Pakistan Must Do Next
For Pakistani policymakers, several imperatives follow from this analysis:
First, develop a comprehensive currency hedging strategy immediately. Whether through derivative contracts, currency swaps with the People’s Bank of China, or natural hedges through yuan-earning initiatives, Pakistan cannot afford to remain naked to yuan-rupee exchange rate risk. The cost of hedging may be high, but the cost of not hedging could be catastrophic.
Second, accelerate export diversification with specific focus on yuan-earning opportunities. Pakistan should aggressively pursue export markets in China, structure trade deals denominated in yuan, and develop business relationships that create natural currency matches for debt obligations. This requires moving beyond traditional export sectors to identify value-added goods and services that Chinese markets demand.
Third, improve debt data transparency through regular reporting on currency composition, maturity profiles, and hedging positions. Markets punish opacity—Pakistan should proactively disclose Panda Bond terms, repayment schedules, and risk management approaches to build credibility with all investor classes.
Fourth, maintain IMF program discipline while managing Chinese creditor relationships. These aren’t inherently contradictory goals, but they require deft diplomacy and consistent policy implementation. Any perception that Pakistan is prioritizing one creditor group over another will trigger adverse market reactions.
Fifth, build yuan market infrastructure including deeper foreign exchange trading platforms, yuan clearing arrangements, and regulatory frameworks for yuan financial products. Pakistan cannot manage yuan exposure effectively without developed yuan financial markets.
For the international community, Pakistan’s Panda Bond experiment offers important data points about emerging market debt dynamics in an era of rising Chinese financial influence. Multilateral institutions should monitor outcomes closely, provide technical assistance for currency risk management, and work toward debt transparency standards that encompass all creditor types.
For China, sustainable lending practices require recognizing the currency risks that yuan-denominated debt imposes on non-yuan-earning economies. Beijing’s interest in yuan internationalization shouldn’t come at the expense of borrower debt sustainability. Currency swap facilities, technical support, and flexible rollover terms could help Pakistan manage yuan obligations while advancing China’s strategic goals.
The Verdict: High-Stakes Financial Statecraft
Pakistan’s $250 million Panda Bond represents high-stakes financial statecraft—a calculated bet that Chinese capital markets offer a viable alternative to traditional Western financing, with acceptable currency risks and manageable geopolitical implications. The rupee’s fate over the next three to five years will substantially determine whether that bet succeeds.
The optimist’s case holds merit: diversifying funding sources reduces dependence on any single creditor, accessing Chinese savings pools taps enormous liquidity, and deepening ties with the world’s second-largest economy makes strategic sense. Lower nominal interest rates could deliver real fiscal savings if managed properly.
But the skeptic’s concerns deserve equal weight: yuan-denominated debt exposes Pakistan to currency mismatches it’s ill-equipped to manage, deepens financial dependence on China when concentration risk is already elevated, and constrains monetary policy flexibility at a time when the economy needs maximum policy space.
The truth, as often, lies between extremes. Pakistan’s Panda Bond isn’t inherently catastrophic or miraculous—it’s a tool whose outcomes depend entirely on how policymakers wield it. Used alongside comprehensive economic reforms, prudent debt management, and strategic currency hedging, it could contribute to fiscal stabilization. Used as a short-term liquidity fix without addressing underlying structural weaknesses, it risks becoming another debt burden that hastens rather than prevents crisis.
For the rupee, the implications are clear: more variables now influence its value, more creditors have stakes in Pakistan’s economic performance, and more complexity surrounds debt sustainability analysis. Whether that complexity proves manageable or overwhelming will define not just Pakistan’s economic trajectory, but potentially set precedents for dozens of other emerging economies watching this experiment unfold.
As Finance Minister Aurangzeb prepares for the January issuance, he should remember that successful debt management isn’t measured by funds raised, but by obligations met. The Panda Bond’s true test won’t come at issuance, when Chinese investors enthusiastically buy Pakistani debt. It will come in 2029, when those bonds mature and Pakistan must deliver yuan it may or may not have, at exchange rates it cannot predict, in a geopolitical environment it cannot control.
That’s not an argument against issuing Panda Bonds—it’s an argument for approaching them with clear-eyed recognition of the risks, comprehensive management strategies, and realistic contingency planning. Pakistan’s currency stability, its fiscal sustainability, and ultimately its economic sovereignty depend on getting these calculations right.
The world is watching. So is the rupee market.
About the Author: This analysis draws on three decades of experience covering emerging market debt crises, currency dynamics, and Sino-Pakistani economic relations. The views expressed are the author’s own and do not represent any institutional affiliation.


In under two years, the regulatory posture toward crypto in the United States has flipped from adversarial to explicitly promotional. What began as an executive order in January 2025 has cascaded into a stablecoin law, a coordinated SEC-CFTC framework, a five-category classification system for digital assets, and — as of this week — a genuine test of whether Congress can finish the job with comprehensive market-structure legislation. Here is the full architecture of Trump-era crypto policy as it stands in September 2026.
The Foundation: Executive Order 14178 and the White House Report
The administration’s crypto agenda traces back to Executive Order 14178, issued at the start of the second Trump term. On July 30, 2025, the President’s Working Group on Digital Asset Markets — established under that order — issued a comprehensive report titled “Strengthening American Leadership in Digital Financial Technology,” according to Practical Law’s coverage. That report became the blueprint both the SEC and CFTC would spend the next year implementing.
SEC’s “Project Crypto” and CFTC’s “Crypto Sprint”
Within 48 hours of the White House report’s release, both major regulators launched dedicated initiatives. SEC Chair Paul Atkins announced “Project Crypto” on July 31, 2025 — an agency-wide effort to implement the White House’s recommendations, with five stated priorities including, notably, “onshoring crypto to the US,” per Practical Law. Chair Atkins directed the SEC’s policy divisions to coordinate with the agency’s Crypto Task Force, led by Commissioner Hester Peirce, a longtime industry-friendly voice at the Commission.
The very next day, then-Acting CFTC Chair Caroline Pham launched a parallel “Crypto Sprint,” a 12-month initiative covering the listing of spot digital assets on CFTC-registered exchanges, allowing derivatives market participants to use tokenized collateral including stablecoins, and establishing a “CEO Innovation Council” of 12 exchange executives, according to K&L Gates. Within months, the CFTC confirmed spot digital assets were available for trading on a CFTC-registered exchange for the first time.
The GENIUS Act: America’s First Federal Stablecoin Law
The most concrete legislative achievement of the period has been the GENIUS Act, the first U.S. federal law specifically governing stablecoins. Its enactment triggered a wave of follow-on rulemaking: K&L Gates noted that the Treasury Department, the Office of the Comptroller of the Currency, and other federal banking agencies all opened rulemakings to implement the law during 2026. The GENIUS Act’s definition of “digital asset” has since become the template other agencies build from — the SEC’s own proposed crypto-asset offering rules explicitly mirror the GENIUS Act’s definitional language.
March 2026: The SEC-CFTC Coordination Breakthrough
The most significant structural shift arrived in March 2026. On March 11, SEC Chairman Paul Atkins and CFTC Chairman Michael Selig signed a Memorandum of Understanding to formally coordinate the two agencies’ historically overlapping and often conflicting jurisdiction over digital assets, according to Latham & Watkins’ policy tracker. The MOU commits both agencies to a “minimum effective dose” of regulation intended to promote innovation while still protecting market integrity.
Six days later, on March 17, 2026, the SEC and CFTC jointly published an interpretive release — their first major coordinated statement since the MOU — sorting digital assets into a five-category framework, according to Holland & Knight: digital commodities, digital collectibles, digital tools, payment stablecoins (aligned with the GENIUS Act definition), and a fifth category covering more traditional securities-like tokens. That classification system is now the reference point nearly every subsequent rulemaking builds from.
Trump-era crypto policy timeline:
| Date | Development | Body |
|---|---|---|
| Jan 2025 | Executive Order 14178 | White House |
| Jul 30, 2025 | Digital asset policy report | Presidential Working Group |
| Jul 31, 2025 | “Project Crypto” launched | SEC (Chair Atkins) |
| Aug 1, 2025 | “Crypto Sprint” launched | CFTC (Acting Chair Pham) |
| — 2025 | GENIUS Act enacted | Congress |
| Mar 11, 2026 | SEC-CFTC MOU signed | SEC + CFTC |
| Mar 17, 2026 | Five-bucket digital asset classification | SEC + CFTC joint release |
| Aug 2026 | “Regulation Crypto Assets” proposed | SEC |
| Sep 10, 2026 | Revised 630-page CLARITY Act released | Senate Republicans |
| Sep 15, 2026 | Procedural vote scheduled | U.S. Senate |
SEC Proposes “Regulation Crypto Assets”
In August 2026, the SEC moved from interpretation to formal rulemaking, proposing “Regulation Crypto Assets” — a bespoke offering regime specifically for crypto investment contracts. According to Sidley Austin’s analysis, Chairman Atkins said the proposed rules “draw heavily from Congressional work over recent years, particularly the CLARITY Act,” explicitly designing the rule to give the industry a regulatory head start pending final legislation. The proposal’s four-year window for a startup exemption mirrors the CLARITY Act’s own timeline for a token project to reach “mature blockchain system” status — a deliberate signal that the SEC expects the legislative and regulatory tracks to converge.
The Unfinished Business: CLARITY Act’s Uncertain Fate
Despite the extensive regulatory groundwork, the industry’s top legislative priority — the Digital Asset Market CLARITY Act, which would legislatively divide SEC/CFTC jurisdiction and create a comprehensive market-structure framework — remains unpassed as of this writing. The House passed its version, but the bill has stalled in the Senate, falling short of the 60 votes needed for passage, according to Holland & Knight.
Senate Republicans released a substantially revised, 630-page version of the bill on September 10, 2026, adding over 100 changes and specifically targeting “decentralized-in-name-only” protocols by requiring them to register with the CFTC, per Investing News Network. A pivotal procedural vote is scheduled for September 15, 2026, after the Senate returns from recess — but the bill already missed one legislative window in August, and CNBC reported that industry insiders, including SALT CEO John Darsie, remain skeptical of passage in 2026 given the difficulty of moving major legislation heading into midterm elections.
What Happens If CLARITY Fails
Crucially, the industry’s regulatory position does not collapse if CLARITY dies in the Senate. As CNBC’s reporting notes, “viewed from a narrow lens, the investment is already paying off, even if Clarity dies” — the SEC and CFTC have already built out much of the practical framework administratively through the MOU, the joint interpretive release, and the proposed Regulation Crypto Assets rule. Legislation would lock the framework into statute, providing durability against a future administration reversing course, but its absence would not undo the deregulatory shift already underway across every major digital-asset regulator, including the Office of the Comptroller of the Currency, which has also moved toward a looser supervisory framework for bank involvement in digital assets.
Final Verdict
The second Trump administration’s crypto policy has been unusually coordinated and fast-moving by regulatory standards: an executive order, a detailed policy report, twin agency initiatives, the first federal stablecoin law, an inter-agency MOU, a joint classification framework, and now a formal rulemaking — all within about 18 months. The remaining variable is whether Congress can convert that administrative groundwork into durable statute via the CLARITY Act, and the September 15 Senate vote is the clearest near-term test of that question. Either outcome, the substantive deregulatory shift toward “onshoring crypto to the US” is already largely in place at the regulatory level — legislation would cement it, not create it.
Barclays reported second-quarter income of £8.3 billion, up £1.2 billion from a year earlier, and upgraded its full-year 2026 income target even as operating expenses climbed 7% year-on-year — a mixed but ultimately reassuring signal for UK banking-sector health as the country navigates elevated gilt yields and a new premiership.
Income Growth Outpaces a Rise in Costs
Barclays reported second-quarter operating expenses of £4.5 billion, up 7% year-on-year, which the bank attributed to business growth, inflation, and increased investment spending, according to CNBC’s markets coverage. Despite the cost increase, income rose to £8.3 billion, and adjusted earnings per share beat Wall Street consensus, prompting shares to initially react positively before falling more than 7% amid broader market volatility on the results day.
Group Chief Executive C.S. Venkatakrishnan struck a confident tone on the outlook, saying the bank was upgrading its 2026 Group income target to approximately £31.5 billion and remained committed to delivering all financial and distribution targets through 2028, according to the same CNBC report.
Why the Results Matter Beyond Barclays
The results land at a delicate moment for UK financial markets more broadly. Ten-year gilt yields have been trading near 5% amid uncertainty over new Prime Minister Andy Burnham’s fiscal programme, while 30-year yields — sensitive to long-term fiscal credibility — have hovered near multi-year highs. A major UK bank posting income growth and raising its full-year guidance amid that backdrop offers a data point suggesting the underlying corporate and consumer credit environment remains healthier than the gilt market’s elevated risk pricing might suggest on its own.
Context: A Resilient Consumer Backdrop
Barclays’ results also arrive alongside broader UK data that has surprised to the upside. UK retail sales rose 1% in June against expectations for a 0.3% decline, while consumer confidence climbed to a six-month high in July, supported by warmer weather and a spending lift tied to the football World Cup — trends that plausibly support the credit and transaction-fee income underpinning Barclays’ income beat. Annual consumer price inflation, meanwhile, slowed to a 15-month low of 2.6% in June, giving the Bank of England room to hold interest rates steady at its policy meeting this week.
The Cost Pressure Story Isn’t Unique to Barclays
The 7% rise in Barclays’ operating expenses reflects a broader pattern across UK banking: inflation-driven wage costs, continued investment in technology and compliance infrastructure, and the general cost of doing business in a higher-rate environment. How rival UK lenders navigate the same pressures in their own upcoming results will be a key signal of whether Barclays’ income upgrade reflects bank-specific execution strength or a sector-wide tailwind from resilient consumer activity.
What to Watch
Barclays’ upgraded £31.5 billion income target sets a clear benchmark against which the rest of 2026 results will be measured, while the sustainability of the current cost growth rate — set against a Bank of England policy backdrop still calibrated around inflation risk — will determine whether margin expansion continues into 2027. Investors will also be watching how the bank’s guidance holds up if gilt-market volatility around the new government’s fiscal plans intensifies.
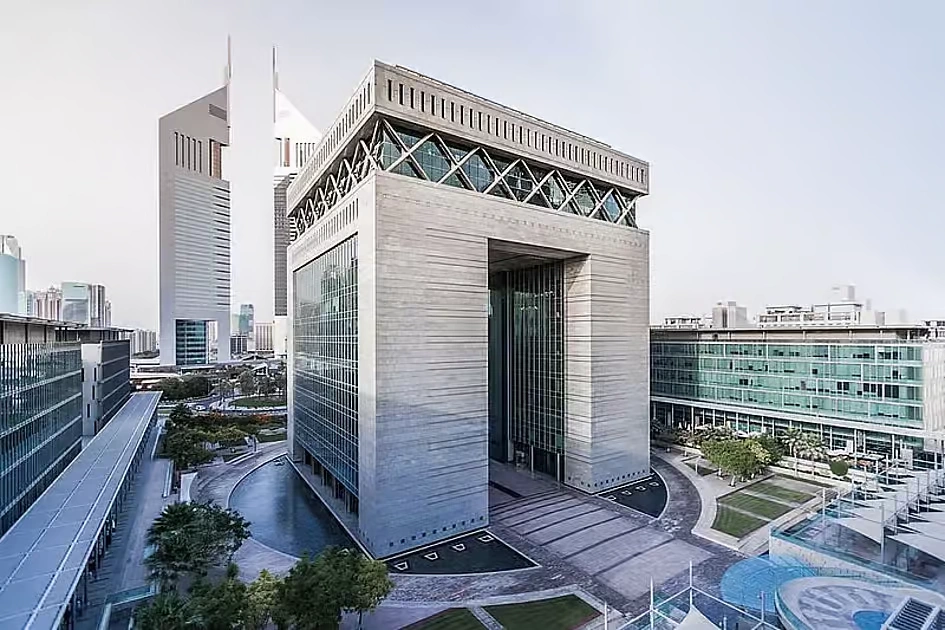
Dubai has climbed to its highest position ever on one of finance’s most closely watched rankings, and the achievement is no accident — it is the direct output of a decade-long, numerically explicit government strategy that few other financial centres have attempted to execute with this level of precision.
The Ranking Itself
The Dubai International Financial Centre has recorded its highest-ever position on the Global Financial Centres Index at seventh place worldwide, the highest ranking ever achieved by any financial centre across the Middle East, Africa and South Asia region, and the only MEASA-region centre to feature in the global top 20 — underscoring both its regional dominance and genuine global competitiveness.
The D33 Strategy Behind the Number
The ranking is explicitly tied to Dubai’s own stated ambitions. The GFCI result is described as pivotal to Dubai’s goal of becoming one of the world’s top four financial centres by 2033, in line with the Dubai Economic Agenda, or D33, which targets a doubling of the emirate’s economy over the decade. Separately, Dubai Chambers has confirmed the plan targets cumulative economic output of AED 32 trillion, or roughly $8.7 trillion, over the decade, supported by 100 transformative projects centred on trade expansion, digital innovation and sustainable growth.
The Underlying Economic Engine
The financial-centre ambitions are backed by genuine current-quarter growth. Dubai’s economy reached AED 232 billion in first-quarter 2026 GDP, a 2.4 percent year-on-year increase, with the finance, construction, healthcare, wholesale and retail trade, and real estate sectors all contributing to the broad-based expansion. Middle East Briefing separately projects the wider UAE economy will expand around 5 percent in 2026, with local banks positioned to increase lending both domestically — supporting SMEs, consumers and project finance — and across borders into markets like Saudi Arabia, where UAE banks’ comparatively lower interbank rates create an arbitrage opportunity.
Real Money Behind the Ranking
The GFCI climb is being validated by tangible transaction volume rather than sentiment alone. Weekly UAE business tracking shows a steady drumbeat of institutional activity: Sharjah Islamic Bank reported AED 803.9 million in net profit, up 15.3 percent, ADI Chain secured a $50 million investment to build sovereign digital infrastructure, and Capital.com reported $1.1 trillion in second-quarter trading volume routed through the jurisdiction. Separately, UAE and Saudi banks are projected to lead GCC credit growth in 2026, reinforcing Dubai and Abu Dhabi’s combined position as the region’s default financial gateway.
Why This Matters for Pakistan and South Asia
Dubai’s ascent as a financial hub carries direct relevance for Pakistan, where — as detailed in our companion coverage of Pakistan’s remittance exposure — roughly 55 percent of the country’s substantial remittance inflows originate from the Gulf Cooperation Council. A deepening, increasingly sophisticated DIFC-anchored financial ecosystem in Dubai means more efficient, lower-cost channels for that capital, alongside growing opportunities for Pakistani and South Asian firms to access GCC-sourced project finance and cross-border credit as UAE banks expand lending beyond their domestic market.
What is Dubai’s global financial centre ranking in 2026?
Dubai’s DIFC recorded its highest-ever ranking on the Global Financial Centres Index at 7th place worldwide in 2026 — the highest ever achieved by any Middle East, Africa or South Asia financial centre — as part of its stated goal to become a top-four global financial hub by 2033.
The Risk Beneath the Growth Story
Not every signal points to unambiguous strength. AGBI’s own reporting notes that UAE banks’ second-quarter results are likely to show weaker profits, slower lending and narrower margins, even as analysts characterise the underlying sector as fundamentally resilient — a reminder that Dubai’s financial-hub ambitions are being pursued against a genuinely more difficult regional operating environment shaped by the Strait of Hormuz disruption and broader Gulf security concerns, not in isolation from them.
The Bottom Line
Dubai’s climb to seventh in the GFCI rankings is less a one-off achievement than a measurable checkpoint on an explicitly numbered, decade-long strategic roadmap — one increasingly backed by real GDP growth, credit expansion, and institutional trading volume rather than ambition alone.

Diesel Prices 2026–2027: Why Cheaper Crude May Not Mean Cheap Fuel

2027 Social Security COLA: Key Details and Dates

KSE-100 Sees Major Drop Post-SBP Rate Hike

Big Tech’s AI Spending Test: Can Revenue Catch Up With Capital Expenditure?

AI Infrastructure Investment Strategies for 2026

Pakistan Freelancers Tax 2026: Payments, Documentation and Formal Growth

Strait of Hormuz Crisis: What the Latest Tanker Attacks Mean for Oil, Shipping and Global Trade

AI Customer Service in 2026: What’s Working, What’s Failing, and What to Buy

Open a Savings Account Online: How to Actually Earn 10x the National Average Rate

Global Housing Market 2026: Where Prices Rise, Where They Don’t

PSX and KSE-100 Record Highs: An Insider’s Guide to Pakistan Stocks

So Delicious Dessert Recall: Affected Products, FDA Guidelines, and Consumer Action

Pakistan’s Current Account Deficit Narrows Sharply to $98 Million in August 2026

Japan Eyes 3.5% Defense Spending: What It Means for Bonds, Stocks, and the BOJ

Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities

Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World

Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns

China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech

What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact

15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025

How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide

Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide

Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
-
 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
 Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
 Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
 Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
 AI11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
 Exports11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025