
Analysis
Meezan Bank: Pakistan’s Premier Islamic Bank – A Deep Dive into Profits, Services, and Market Dominance in 2026

Meezan Bank, the country’s first and largest Islamic bank, has transformed from a pioneering experiment in Shariah-compliant finance into a dominant force commanding over one-fifth of Pakistan’s Islamic banking sector. As the country accelerates toward a fully interest-free banking system by 2027–2028, Meezan stands at the vanguard of this historic transition—not merely as a participant, but as the architect of what Islamic banking Pakistan can achieve at scale.
The bank’s financial performance through 2025 tells a story of remarkable resilience amid turbulent economic conditions. For the nine months ending September 30, 2025, Meezan Bank posted a profit after tax approaching Rs 70 billion, marking substantial year-on-year growth despite Pakistan’s macroeconomic headwinds. This achievement positions Meezan not just as the premier Islamic bank Pakistan relies upon, but as a case study in how Shariah-compliant financial institutions can outperform conventional competitors while adhering to ethical financing principles. For investors, policymakers, and financial analysts seeking to understand the future of Islamic finance, Meezan Bank represents both a bellwether and a blueprint.
Meezan Bank’s Record-Breaking Profits in 2025: Dissecting the Financial Performance
The financial year 2025 has proven transformational for Meezan Bank, with third-quarter results revealing the depth of its competitive advantages. According to the bank’s official financial disclosures, profit after tax for the nine months ended September 30, 2025, reached approximately Rs 67–70 billion, representing a robust increase from the corresponding period in 2024. This growth trajectory becomes even more impressive when contextualized against Pakistan’s challenging economic backdrop—elevated inflation, currency depreciation, and policy rate volatility that compressed margins across the banking sector.
Breaking down the quarterly performance, Meezan demonstrated accelerating momentum through 2025. Third-quarter profits alone contributed a substantial portion of the nine-month total, suggesting operational efficiency improvements and successful asset repricing strategies. The bank’s annualized earnings per share (EPS) tracked toward historic highs, rewarding shareholders who bet on Islamic banking’s structural growth in Pakistan.

Key performance indicators paint a picture of comprehensive institutional strength. Return on equity (ROE) remained elevated in the 16–18% range, significantly outpacing many conventional banks struggling with asset quality concerns. Return on assets (ROA), while naturally lower given the asset-heavy nature of Islamic financing modes, held steady above 1.5%—a testament to deployment efficiency. The cost-to-income ratio, a critical measure of operational discipline, improved year-over-year as digital transformation initiatives reduced branch transaction costs while mobile banking adoption surged.
Asset expansion tells another compelling story. Meezan Bank’s total assets crossed Rs 2.5 trillion during 2025, solidifying its position as Pakistan’s largest Islamic bank by a substantial margin. This growth was driven by healthy customer financing expansion—particularly in retail segments like housing and automotive—alongside strategic investments in government securities structured through Shariah-compliant mechanisms. Deposit growth kept pace, with the bank’s customer deposit base exceeding Rs 2.2 trillion, reflecting deep trust in Meezan’s brand and the broadening appeal of halal financing options.
The net markup income (NMI) spread, Islamic banking’s equivalent to net interest margin, widened strategically as Meezan capitalized on its lower-cost deposit base. Current and savings accounts (CASA) represented over 80% of total deposits, an extraordinarily favorable mix that provides cheap funding for higher-yielding Islamic financing products. This structural advantage—built through decades of customer acquisition and brand loyalty—creates a competitive moat difficult for smaller Islamic competitors to replicate.
Comparing year-on-year performance, 2025’s results represented approximately 25–30% growth over the same period in 2024, significantly outstripping Pakistan’s nominal GDP growth and inflation rates. This outperformance reflects both market share gains from conventional banks and the expansion of Pakistan’s overall Islamic banking penetration, which reached 22% of total banking assets according to the State Bank of Pakistan’s Islamic Banking Bulletin.
Key Services That Set Meezan Apart: Product Innovation and Customer-Centric Solutions
Meezan Bank’s market dominance stems not from legacy advantages alone, but from a comprehensive product suite that addresses Pakistani consumers’ diverse financial needs through Shariah-compliant structures. The bank has masterfully translated Islamic finance principles—prohibition of riba (interest), maisir (speculation), and gharar (excessive uncertainty)—into practical banking products that compete effectively with conventional offerings.
Easy Home Islamic: Redefining House Financing
Perhaps no product better exemplifies Meezan’s innovation than Easy Home Islamic, the bank’s flagship residential property financing solution. Unlike conventional mortgages that charge interest, Easy Home operates through diminishing musharaka—a co-ownership structure where the bank and customer jointly purchase property, with the customer gradually buying out the bank’s share through rental payments. This arrangement satisfies both Shariah requirements and customer preferences for homeownership.
The product’s competitive pricing, flexible tenures extending up to 20 years, and financing amounts reaching Rs 150 million for premium properties have made it Pakistan’s most popular Islamic home finance solution. Meezan’s processing efficiency, with approvals often completed within 48–72 hours for qualified applicants, contrasts sharply with the bureaucratic delays plaguing many conventional banks. The bank’s 2025 housing finance portfolio grew by over 35% year-on-year, capturing substantial market share from both Islamic competitors and conventional banks whose interest-based products face increasing public scrutiny.
Car Ijarah: Automotive Financing Done Right
Meezan’s Car Ijarah product demonstrates how Islamic finance can simplify rather than complicate consumer transactions. Built on the ijarah (leasing) structure, the bank purchases vehicles on behalf of customers and leases them for a fixed period, with ownership transferring at lease end. This approach eliminates interest charges while providing transparent, fixed-payment schedules that customers appreciate in inflationary environments.
The product covers new and used vehicles across all price ranges, from economy sedans to luxury SUVs, with financing tenures up to five years. Meezan’s partnerships with major automotive manufacturers and dealers ensure competitive pricing and streamlined processing. The bank’s automotive portfolio expanded by approximately 40% in 2025, reflecting both Pakistan’s recovering automobile market and consumer preference for Shariah-compliant financing options.
Roshan Digital Account: Banking for the Pakistani Diaspora
Few products better illustrate Meezan’s forward-thinking approach than the Roshan Digital Account (RDA), developed in partnership with the State Bank of Pakistan to facilitate overseas Pakistanis’ banking needs. Launched in 2020 and significantly expanded since, the RDA allows non-resident Pakistanis to open accounts remotely, transfer funds, and invest in Pakistan through a fully digital, Shariah-compliant platform.
Meezan’s RDA offering includes multiple Islamic savings products with competitive profit rates, investment options in government securities and equities, and seamless repatriation facilities. The bank has captured a substantial share of the RDA market, with billions of dollars in deposits from overseas Pakistanis seeking both financial returns and Shariah compliance. This product generates stable foreign currency deposits while strengthening Pakistan’s external account—a win-win that exemplifies strategic innovation.
Premium Banking and Wealth Management
Recognizing the growing wealth among Pakistan’s upper-middle class and affluent segments, Meezan has invested heavily in premium banking services. Meezan Privilege Banking offers high-net-worth clients dedicated relationship managers, priority services, preferential profit rates, and exclusive access to Shariah-compliant investment products including Islamic mutual funds, sukuk (Islamic bonds), and structured deposits.
The bank’s wealth management advisory goes beyond transactional banking to provide holistic financial planning—estate planning through Islamic inheritance structures, zakat calculation assistance, and investment portfolio management aligned with Islamic ethical principles. This comprehensive approach differentiates Meezan from competitors who treat wealthy clients as merely larger deposit holders.
SME and Agricultural Financing: Beyond Retail Banking
Meezan’s commitment to Pakistan’s economic development extends through substantial small and medium enterprise (SME) and agricultural financing programs. The bank structures working capital, trade financing, and equipment leasing through Islamic modes like murabaha (cost-plus financing), salam (advance purchase), and istisna (manufacturing finance).
Agricultural financing represents a particular focus area, with products tailored to Pakistan’s farming communities—often underserved by conventional banks wary of rural credit risk. Meezan’s Islamic financing structures, which emphasize partnership and shared risk rather than pure debt, align well with agricultural cycles and provide flexibility during crop failures or market downturns.
Digital Banking Transformation
Meezan has aggressively digitized its service delivery, recognizing that Pakistan’s young, tech-savvy population demands mobile-first banking. The Meezan Mobile app offers comprehensive functionality—account management, fund transfers, bill payments, Islamic investment purchases, and even instant Car Ijarah applications. The platform’s user experience rivals international fintech apps while maintaining complete Shariah compliance.
Biometric ATM access, QR code payments, and instant account opening via NADRA e-verification have reduced physical branch dependency. This digital transformation not only improves customer experience but also controls costs—digital transactions cost fractions of branch-based services, directly benefiting profitability.
How Meezan Outperforms Competitors: Market Leadership in Islamic Banking Pakistan
To appreciate Meezan Bank’s dominance requires comparing it against key competitors in Pakistan’s Islamic banking landscape. The competitive set includes both pure Islamic banks and Islamic banking windows of conventional banks, each vying for market share in a sector growing faster than conventional banking.
Market Share and Scale Advantages
According to the latest State Bank of Pakistan data, Meezan Bank commands approximately 21–22% of Pakistan’s total Islamic banking sector assets—nearly double its nearest pure Islamic competitor. This market share translates into substantial scale advantages: negotiating power with vendors, investment in technology platforms, brand recognition, and access to capital markets that smaller players cannot match.
The bank operates over 900 branches across Pakistan, including substantial presence in underserved regions where Islamic banking options were historically limited. This distribution network, built systematically over two decades, represents a competitive moat—replicating it would require billions in capital expenditure and years of local relationship building.
Comparative Analysis: Meezan vs. Key Islamic Banking Competitors
BankIslami Pakistan, the second-largest standalone Islamic bank, operates at roughly half Meezan’s scale with assets near Rs 1.2 trillion. While BankIslami has grown aggressively and demonstrated improving profitability, it lacks Meezan’s operational efficiency and product breadth. BankIslami’s ROE and ROA consistently trail Meezan’s, suggesting higher operational costs and less effective asset deployment. The bank’s CASA ratio, while respectable, remains below Meezan’s, translating to higher funding costs that compress margins.
Dubai Islamic Bank Pakistan, backed by its UAE parent’s global expertise, represents a formidable competitor particularly in corporate and investment banking segments. However, DIBP’s retail penetration and branch network lag Meezan substantially. The bank’s profit contribution to Pakistan’s Islamic banking sector remains single-digit percentage-wise, reflecting its more specialized, less mass-market positioning.
Al Baraka Bank Pakistan, affiliated with the international Al Baraka Banking Group, operates at smaller scale with focus on niche segments. While the bank demonstrates solid Shariah credentials and international connectivity, its limited branch network constrains deposit mobilization and retail growth. Al Baraka’s profitability has been volatile, contrasting with Meezan’s consistent upward trajectory.
MCB Islamic Banking, the Islamic window of MCB Bank Limited (one of Pakistan’s largest conventional banks), represents the primary threat from conventional banks’ Islamic subsidiaries. MCB Islamic benefits from its parent’s infrastructure, distribution network, and technology platforms. However, the subsidiary model creates perception challenges—customers seeking Islamic banking often prefer standalone Islamic banks viewed as more authentically committed to Shariah principles. MCB Islamic’s growth, while substantial, has not eroded Meezan’s leadership position.
Profitability and Efficiency Metrics
Comparing profitability across Islamic banks reveals Meezan’s operational superiority. While precise competitor data varies, industry analysis suggests Meezan’s ROE of 16–18% exceeds most Islamic competitors by 200–400 basis points. Cost-to-income ratios follow similar patterns—Meezan’s improved ratio below 45% compares favorably to competitors in the 50–60% range, reflecting superior operational efficiency.
This efficiency stems from multiple factors: larger scale spreading fixed costs, earlier technology investments now yielding dividends, superior talent acquisition and retention, and management excellence accumulated over two decades of focused Islamic banking experience.
Innovation and First-Mover Advantages
Meezan’s consistent product innovation creates difficult-to-match competitive advantages. Being first to market with Roshan Digital Accounts, pioneering Islamic credit cards, launching Pakistan’s first Islamic banking mobile app, and introducing innovative corporate sukuk structures establishes market leadership that competitors struggle to overcome. First-movers build brand associations—”Meezan” has become nearly synonymous with Islamic banking in Pakistan, much as “Kleenex” represents tissue paper.
The bank’s thought leadership extends beyond products. Meezan executives regularly contribute to global Islamic finance conferences, its research publications inform policy debates, and its Shariah board includes internationally respected scholars whose rulings carry weight across the industry. This intellectual capital reinforces market positioning.
The Future of Islamic Banking in Pakistan: Meezan’s Role in Systemic Transformation
Meezan Bank’s trajectory cannot be separated from Pakistan’s broader Islamic banking evolution. The sector’s growth from negligible market share in 2000 to over 22% of total banking assets by 2025 represents one of Islamic finance’s global success stories. Understanding this context illuminates both opportunities and challenges ahead.
Regulatory Momentum Toward Interest-Free Banking
Pakistan’s journey toward a fully Shariah-compliant financial system received substantial momentum from landmark court decisions and regulatory initiatives. The Federal Shariat Court’s 2022 ruling declaring interest-based banking un-Islamic, while subject to appeals and implementation complexities, accelerated government and central bank efforts to facilitate Islamic banking expansion.
The State Bank of Pakistan has set ambitious targets for Islamic banking penetration—approaching 30–35% of total banking assets by 2027–2028. Regulatory reforms supporting this goal include: simplified Islamic banking licensing, standardized Shariah governance frameworks, Islamic liquidity management instruments, and dedicated Islamic banking windows at all conventional banks. Meezan, as the sector’s largest player, naturally benefits from this supportive regulatory environment.
Economic Resilience and Structural Advantages
Islamic banking’s performance through Pakistan’s recent economic challenges—currency crises, inflation spikes, political uncertainty—demonstrated structural resilience that attracts customers and investors. The equity-based nature of Islamic finance, where banks and customers share risk rather than banks simply lending at fixed interest, theoretically creates more stable banking systems.
Meezan’s deposit stability during periods when conventional banks faced liquidity pressures validates this thesis. Customers perceive Islamic banking as ethically superior—less extractive, more partnership-oriented—which translates into stickier relationships and lower attrition even when profit rates temporarily lag conventional interest rates.
Demographic Tailwinds
Pakistan’s demographics strongly favor Islamic banking growth. A young population (median age below 23 years) with increasing religious awareness prefers Shariah-compliant financial services. Rising education levels and digital literacy make sophisticated Islamic finance products accessible to broader audiences. Urbanization concentrates populations in areas where Islamic banking infrastructure exists or can be efficiently deployed.
The 200-million-plus population remains significantly underbanked—less than 30% have formal bank accounts. As financial inclusion progresses, Islamic banks capturing disproportionate shares of newly banked customers could accelerate their market share gains. Meezan’s strong brand among younger Pakistanis positions it ideally for this demographic wave.
Challenges and Headwinds
Balanced analysis requires acknowledging challenges facing Meezan and Islamic banking broadly. Product pricing remains contentious—while Islamic banks avoid “interest,” their profit rates often track closely with conventional interest rates, raising questions about substantive versus formal differences. Critics argue that some Islamic banking products represent financial engineering that achieves conventional outcomes through Shariah-compliant structures.
Operational complexity presents ongoing challenges. Maintaining Shariah compliance requires extensive governance structures—dedicated Shariah boards, product vetting, transaction audits—that add costs. Training staff in Islamic finance principles beyond conventional banking requires sustained investment. Liquidity management in Islamic banking remains more complex than conventional banking due to limited Shariah-compliant instruments.
Competition is intensifying. As Islamic banking’s success becomes apparent, conventional banks’ Islamic windows are being resourced more aggressively. International Islamic banks eye Pakistan’s large market. Fintech companies are developing digital-first Islamic finance solutions that could disrupt traditional banking models.
Meezan’s Strategic Positioning for 2026 and Beyond
Meezan Bank’s leadership position heading into 2026 reflects strategic decisions that compound over time. The bank’s continued investment in digital infrastructure—artificial intelligence for credit assessment, blockchain for trade finance, mobile-first product design—positions it for the next generation of banking competition.
Geographic expansion remains a priority, with plans to reach 1,000+ branches and extend into Pakistan’s remotest areas where banking access remains limited. Partnerships with fintech companies, telecommunications providers, and retail chains will extend Meezan’s reach beyond traditional banking channels.
Product innovation continues, with forthcoming launches including: Islamic wealth management robo-advisory, supply chain finance for SMEs, green sukuk for environmentally sustainable projects, and enhanced Islamic credit card features. International expansion, particularly targeting Pakistani diaspora communities in Gulf countries, UK, and North America through digital channels, represents another growth vector.
The bank’s commitment to financial inclusion through initiatives like no-frills Islamic savings accounts, microfinance partnerships, and agricultural extension services demonstrates that profitability and social impact need not conflict. This positioning strengthens Meezan’s reputation and may provide regulatory goodwill as banking sector oversight intensifies.
Conclusion: The Premier Islamic Bank Pakistan Deserves
Meezan Bank’s journey from pioneering startup to Pakistan’s premier Islamic bank encapsulates broader themes in contemporary finance: the viability of ethical banking models, the power of sustained strategic execution, and the importance of aligning institutional values with customer aspirations. The bank’s impressive 2025 financial performance—approaching Rs 70 billion in nine-month profit, expanding market share, and demonstrating operational excellence—validates its business model while establishing benchmarks for Islamic banking globally.
For investors, Meezan represents exposure to multiple growth drivers: Pakistan’s Islamic banking structural expansion, financial inclusion megatrends, and a best-in-class management team with proven execution capabilities. The bank’s valuation metrics, while not inexpensive, reflect quality deserving of premiums.
For customers, Meezan offers comprehensive Shariah-compliant banking without compromising on service quality, technological sophistication, or product breadth. From Easy Home Islamic housing finance to Roshan Digital Accounts serving overseas Pakistanis, the bank demonstrates that Islamic banking can match or exceed conventional banking on customer experience.
For the broader financial community, Meezan Bank proves that Islamic finance transcends niche markets. With over Rs 2.5 trillion in assets, 900+ branches, and profitability rivaling Pakistan’s largest conventional banks, Meezan has achieved systemic importance. Its continued success or setbacks will shape Islamic banking’s trajectory not just in Pakistan but across the Muslim world.
As Pakistan accelerates toward its vision of a predominantly Islamic financial system by 2027–2028, Meezan Bank stands positioned not merely to participate in this transformation but to lead it. The bank’s combination of scale, profitability, innovation, and unwavering commitment to Shariah principles makes it the premier Islamic bank Pakistan requires for its next chapter of economic development. In an industry where trust, expertise, and values alignment matter enormously, Meezan has earned its leadership position one customer, one transaction, one quarter of impressive financial results at a time.


Quick answer: The Social Security Administration has confirmed a 3.6% cost-of-living adjustment (COLA) for 2027. Retirement, survivor and disability benefit increases generally appear in January 2027 payments, while the higher federal Supplemental Security Income (SSI) amount first becomes payable on December 31, 2026 because January 1 is a holiday. The SSA’s October 14 announcement and official 2027 calendar hub are the authoritative starting points.
People searching for the 2027 Social Security calendar usually have two distinct questions: When will the money arrive? and How much will I receive? The payment schedule is mainly determined by program and birth-date rules. The amount depends on the individual’s existing benefit, the COLA, deductions and other adjustments. A national chart cannot predict an individual’s net bank deposit.
The 2027 second, third and fourth Wednesday calendar
For most people receiving Social Security retirement, survivor or disability benefits, the payment day depends on the birth date attached to the benefit record. The second Wednesday generally covers dates from the 1st–10th, the third covers 11th–20th, and the fourth covers 21st–31st. The SSA scheduling FAQ explains the standard rule and groups that use a different cycle.
| Benefit month | Birth date 1–10: 2nd Wednesday | Birth date 11–20: 3rd Wednesday | Birth date 21–31: 4th Wednesday |
|---|---|---|---|
| January 2027 | Jan. 13 | Jan. 20 | Jan. 27 |
| February 2027 | Feb. 10 | Feb. 17 | Feb. 24 |
| March 2027 | Mar. 10 | Mar. 17 | Mar. 24 |
| April 2027 | Apr. 14 | Apr. 21 | Apr. 28 |
| May 2027 | May 12 | May 19 | May 26 |
| June 2027 | Jun. 9 | Jun. 16 | Jun. 23 |
| July 2027 | Jul. 14 | Jul. 21 | Jul. 28 |
| August 2027 | Aug. 11 | Aug. 18 | Aug. 25 |
| September 2027 | Sep. 8 | Sep. 15 | Sep. 22 |
| October 2027 | Oct. 13 | Oct. 20 | Oct. 27 |
| November 2027 | Nov. 10 | Nov. 17 | Nov. 24 |
| December 2027 | Dec. 8 | Dec. 15 | Dec. 22 |
Important: This table is a calendar computation of the ordinary Wednesday cycle, not a substitute for SSA’s official published payment calendar. Holidays can shift issuance to a preceding business day, and several beneficiary categories use different payment dates. For example, some people who began benefits before May 1997 or receive both SSI and Social Security use the third-of-the-month cycle. Check the official SSA calendar for 2027 before setting a direct debit or making a payment commitment.
How the 2027 COLA changes benefits
The SSA’s official press release says the 3.6% COLA will increase benefits for nearly 72 million Social Security recipients starting with payments in January 2027; about 7.3 million SSI recipients will start seeing higher payments on December 31, 2026. Some individuals belong to both groups, so the two populations should not simply be added to estimate unique recipients.
On average, Social Security retirement benefits are expected to rise by about $75 a month, according to the same announcement. An average increase is not a universal raise. Someone with a $1,000 monthly gross benefit would see an arithmetic 3.6% rise of about $36 before other adjustments, while someone with $2,500 would see about $90. Actual notices and statutory rounding rules determine each beneficiary’s individual amount.
| SSA published indicator | Before 2027 COLA | After 2027 COLA |
|---|---|---|
| Estimated average retired worker benefit | $2,095 | $2,170 |
| Estimated average disabled worker benefit | $1,642 | $1,701 |
| Federal SSI maximum, individual | $994 | $1,029 |
| Federal SSI maximum, eligible couple | $1,491 | $1,544 |
Source: SSA’s 2027 COLA fact sheet. The retirement and disability figures are estimated averages, while the SSI figures are federal maximum standards; they are not interchangeable with an individual’s award notice.
Why some 2027 benefits start arriving in December 2026
The agency explains that January SSI payments are advanced to the last business day of December when January 1 is a federal holiday. For the 2027 adjustment, that date is Thursday, December 31, 2026. Beneficiaries should not treat an SSI deposit appearing in December as an extra 2026 benefit or an omitted January payment. It is the payment for the next benefit month, issued early.
The SSA’s COLA FAQ explicitly distinguishes the start of higher SSI payments from the first increased regular Social Security checks. This is an important budgeting detail for people receiving both programs. Receiving a single account deposit on December 31 does not mean every category of benefit has the same schedule.
An additional complication occurs for recipients in special payment groups that use the third of the month rather than Wednesday birth-date rules. The third of January 2027 falls on a Sunday, close to the January 1 holiday. Consult the official agency calendar for the adjusted date rather than mechanically assuming payment occurs Sunday, January 3. The precise date of a bank’s posting can also vary from SSA’s issuance date.
The 2027 SSI standards and why your deposit may be lower
The federal maximum SSI payment for 2027 is $1,029 per month for an eligible individual and $1,544 for an eligible couple, according to SSA’s SSI payment-amount schedule. Those figures are ceilings for specified eligibility situations, not guaranteed deposits for everyone receiving SSI.
SSI is a means-tested program. Countable income and other eligibility factors can reduce the federal payment. Some states supplement SSI, and their rules differ. A beneficiary who receives $650 monthly in 2026 cannot simply assume the 2027 bank deposit will become $1,029. The payment may also be affected by living arrangements and other circumstances.
SSA’s 2027 fact sheet also shows SSI federal resource limits still at $2,000 for an individual and $3,000 for a couple. The fact that payment standards increase with inflation does not mean every other eligibility threshold rises by the same percentage. People applying for SSI should review the entire set of rules rather than focusing only on the maximum award.
Does a 3.6% COLA mean 3.6% more money in your bank account?
Not necessarily. The COLA applies to the relevant gross benefit calculation. A person’s net deposit can also reflect Medicare premiums, tax withholding, recovery of overpayments, garnishments in permitted cases and other statutory adjustments. Consequently, a 3.6% gross increase can translate into a different percentage change in the deposited amount.
For budget planning, first compare the 2026 and 2027 gross Social Security benefit on the award or COLA notice, then inspect deductions separately. If the net amount surprises you, do not assume a processing error without checking whether a premium or withholding item changed. Use the my Social Security portal to review official personal notices rather than trusting a generic calculator that cannot see your account.
Inflation also varies by household. The 3.6% COLA is calculated under a statutory method using the CPI-W, not a custom estimate of each retiree’s expenses. A person with unusually high housing, medical or utility costs might experience a greater price increase than the official adjustment compensates for; another may experience less. The COLA is intended to help benefits keep pace with measured prices, not guarantee unchanged purchasing power for every household.
How much can you earn while collecting benefits?
Some Social Security recipients work while collecting retirement or disability benefits. The rules vary by benefit category and age. The SSA 2027 COLA fact sheet lists an earnings-test limit of $25,560 for workers under full retirement age and $67,920 for the year someone reaches full retirement age, applicable to earnings in months before reaching that age. These limits are different from SSI income rules and disability work-incentive thresholds.
The earnings test can withhold some benefits above limits, but it does not mean wages are simply confiscated or that all working retirees lose benefits permanently. Social Security later adjusts for certain months in which benefits were withheld under retirement earnings rules. The best answer for a particular worker depends on age, retirement entitlement and other circumstances.
For disability beneficiaries, separate substantial-gainful-activity and trial-work-period rules may apply. The fact sheet shows different thresholds for 2027. Anyone considering additional work while receiving disability or SSI benefits should check the precise applicable program with SSA, because using a retirement earnings limit for disability can produce harmful errors.
How to find your personal 2027 COLA notice
SSA says most people with a my Social Security account can view their COLA notices online when they become available, and paper notices arrive later for other recipients. The SSA FAQ describes the notice rollout and says that a person whose letter has not arrived immediately should not assume something is wrong. A secured official account is preferable to links in unsolicited emails that ask for credentials.
A useful checklist is to confirm your name, benefit type, 2026 amount, 2027 amount, deductions and bank account information. If anything appears inconsistent, contact SSA through a verified channel. Do not provide a Social Security number or login code to a caller claiming a higher payment can be ‘activated’ for a processing fee. COLA adjustments are part of the statutory benefit system; they do not require paying someone for enrollment.
Frequently asked questions
What is the Social Security COLA for 2027?
3.6%, formally announced by the Social Security Administration on October 14, 2026.
When is the first increased Social Security check in 2027?
The increase appears in January 2027 regular Social Security payments, following each recipient’s applicable payment schedule. Higher SSI payments first arrive December 31, 2026.
Is the average increase really $75?
SSA estimates the average monthly benefit of retired workers will rise by about $75, from approximately $2,095 to $2,170. Individual increases vary.
Does everyone receive Social Security on the second Wednesday?
No. Second, third and fourth Wednesdays apply to the major birth-date groups; special categories and holiday adjustments use other dates.
How much is the 2027 federal SSI maximum?
SSA lists $1,029 for an eligible individual and $1,544 for an eligible couple. Actual payments depend on eligibility, income and other rules.
Should I budget the whole year from this chart alone?
Use it as an orientation, then download the official 2027 payment calendar from SSA and check individual benefit notices. Dates and net deposits should be confirmed before scheduling automatic withdrawals.
Bottom line
The two verified anchors for 2027 are a 3.6% COLA and an official SSA calendar that differentiates regular Social Security, SSI and exception groups. Generic Wednesday charts are useful, but the safest budgeting approach combines the published schedule with your own notice. A slightly earlier payment can be a calendar adjustment—not an extra benefit—and a larger gross award need not mean an identical net increase.
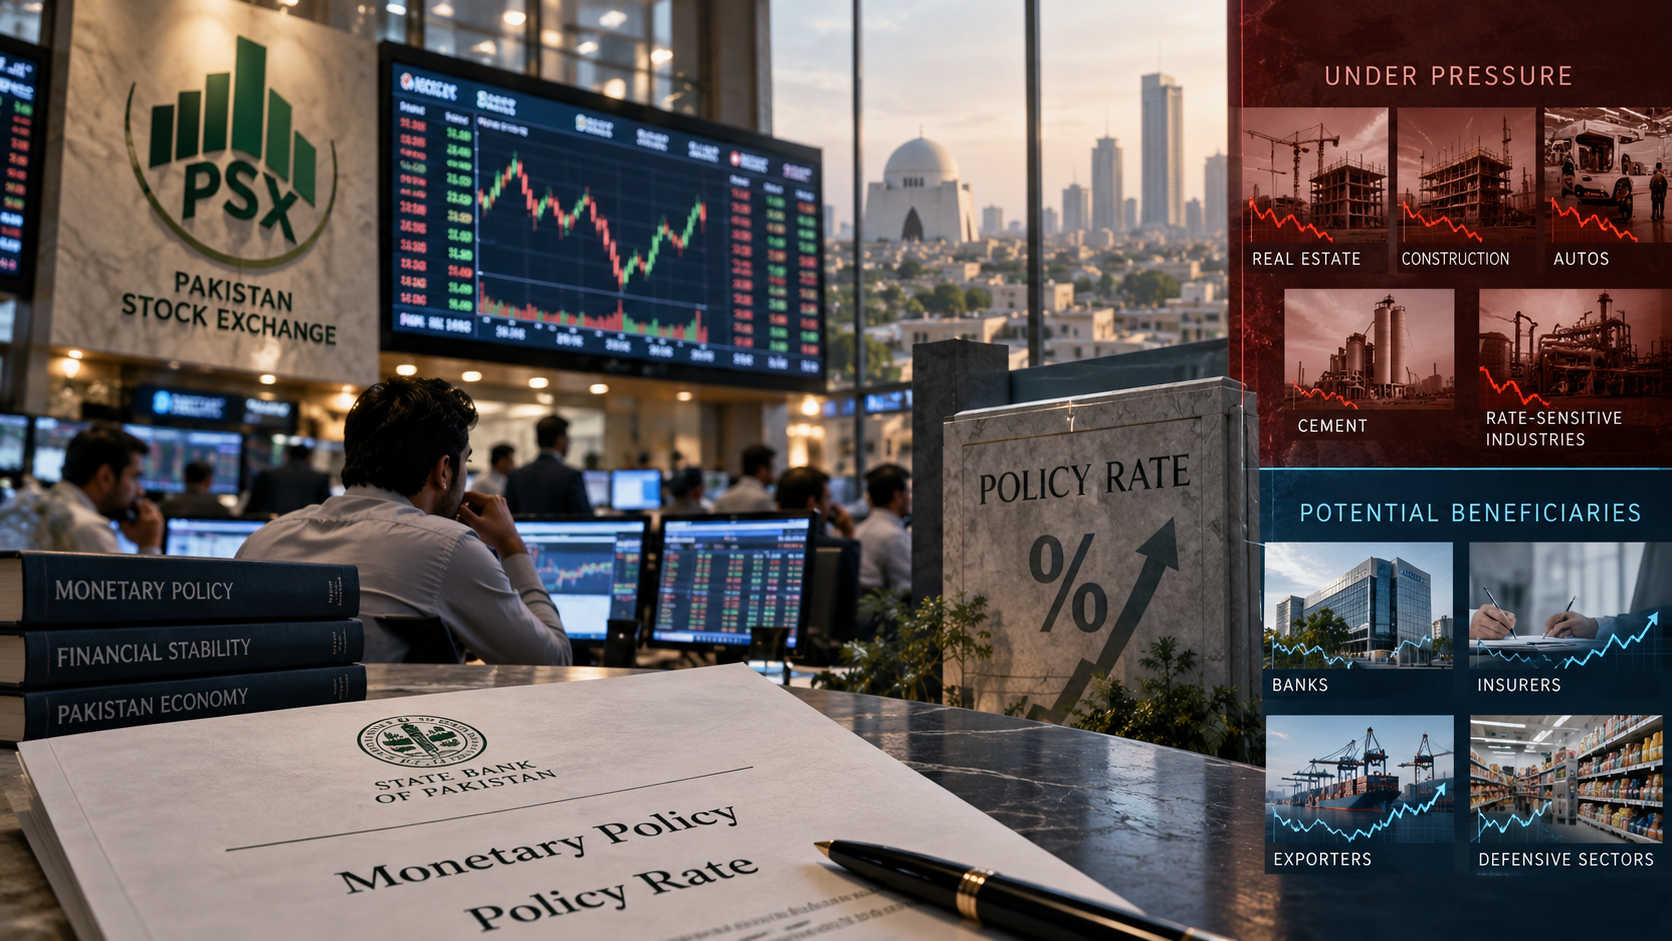
The KSE-100 was weak in the days around the SBP’s 26 October decision. Business Recorder reported the index down more than 800 points in the opening minutes of Monday, at about 161,542, and Tribune had it near 161,660 by midday, an intraday range of roughly 161,250 to 162,488. The Friday before, the index had lost more than 1,300 points as fighting between Saudi Arabia and the Houthis intensified and oil rose. Arif Habib’s head of research, Sana Tawfik, attributed the selling to two things: global weakness on higher oil and caution ahead of the rate decision.
The sectors named in reports were broad: automobile assemblers, cement, commercial banks, oil and gas explorers, oil marketing companies, power generation and refineries. Index heavyweights such as HUBCO, OGDC, MARI, PPL, HBL, MEBL and NBP traded lower at the opening.
The SBP then raised the policy rate by 50 bps to 12%, the first rise since April’s 100 bps move. The post-decision close was not retrieved; check it before publishing.
Why Sectors React Differently
Cement and autos (leveraged, demand-sensitive). Higher borrowing costs raise financing expenses for companies and can dampen private credit and investment. After April’s hike, analysts reported in Tribune that cyclicals such as cement would carry the weight of higher rates.
Commercial banks (mixed). The same April analysis suggested banks could see relative support over the medium term, as higher rates typically widen margins on assets. But banks also sold off in recent sessions, reflecting broader risk-off sentiment and sensitivity to government borrowing costs, so the benefit is not automatic.
Oil and gas explorers and oil marketers (oil-linked). These trade on the oil price and on circular-debt and pricing-policy questions as much as on rates. With Brent near $115, the oil story can outweigh the rate story.
Power producers and refineries. Sensitive to financing costs, energy-pricing decisions and the IMF’s push for timely tariff adjustments.
Fertiliser. Reported among the sectors with selling pressure after April’s hike; gas pricing and input costs matter alongside rates.
What the Hike Means for Valuations
Higher policy rates raise the return investors can earn on risk-free assets, which pushes down the price they will pay for equities. With inflation at 10.26% in September and a policy rate of 12%, the real return on fixed income is modestly positive. That competes with equities for capital, particularly after a strong multi-year run in the index.
Scenarios for the Next Few Weeks
- Oil retreats on a Qatari deal: inflation fears ease, and the market could recover some of the loss. The reply from Iran is due by the end of the week.
- Stalemate: headline-driven trading with sector rotation based on oil sensitivity.
- Escalation or another hike on 14 December: pressure on cyclicals and leveraged names.
These are scenarios, not forecasts.
What Investors Should Check
- Company debt levels and interest coverage (leveraged names are most exposed).
- Exposure to oil prices and government pricing policy.
- Dividend yield versus T-bill and deposit rates.
- Upcoming earnings season commentary on financing costs.
The PSX sold off ahead of a hike that was widely expected. What matters now is whether oil and the Iran talks ease or worsen the inflation outlook, because that, not Monday’s 50 bps, will decide the 14 December MPC and the market’s direction.
The artificial-intelligence revolution has a rather old-fashioned problem: someone must pay for the buildings, chips, cooling systems and electricity before the promised productivity gains arrive. For Big Tech, the crucial question this earnings season is no longer whether AI is exciting. It is whether the economics of building capacity can satisfy the owners of public companies.
A Reuters examination of hyperscaler spending found that rising AI infrastructure commitments were putting free cash flow under pressure even as cloud and AI revenues expanded. With Alphabet, Microsoft, Amazon and other major businesses due to face further investor scrutiny during the late-October reporting period, the argument is shifting from technological capability to return on invested capital.
Capex is not the same as an expense
Capital expenditure includes spending on long-lived assets such as data centres, servers and network infrastructure. Its accounting cost is generally spread over time through depreciation. The cash often leaves sooner. A company can therefore report healthy operating profit while its free cash flow weakens because it is building capacity at extraordinary speed.
The gap matters because shares are valued on future economic benefits, not just on the volume of equipment a company can buy. High capex can be an intelligent competitive strategy if that infrastructure becomes heavily utilised and generates attractive cash returns. It can also be a costly mistake if expected demand fails to materialise or hardware becomes outdated sooner than planned.
Five questions earnings calls must answer
Is utilisation improving? A data centre that has been built but not fully used represents tied-up capital. Investors need insight into workloads, capacity commitments and the timing of revenue recognition.
Are AI customers paying enough? Generative AI applications can have meaningful inference costs. Growth in usage is less impressive if each additional request barely covers variable expense.
Will depreciation rise faster than sales? Rapid investment today can depress future reported margins as expensive equipment enters service. Hardware useful lives and replacement cycles deserve scrutiny.
Who funds the power and network expansion? Electricity procurement, cooling and grid upgrades are not trivial afterthoughts. Constraints outside the chip market could delay cash generation.
What happens to shareholder returns? Repurchases and dividends can coexist with investment, but they become harder to sustain if capex consumes a growing share of operating cash flow.
Why this is more than a Silicon Valley story
The AI boom has implications for countries positioned to supply power equipment, semiconductors, engineering and enterprise software. Yet the IMF’s October World Economic Outlook warns that economies outside the technology-investment value chain—especially energy importers—face a difficult global environment. This is a reminder that spectacular capital spending in one sector does not mean broad prosperity everywhere.
Even within successful technology markets, concentration can be a risk. Data-centre demand benefits cloud providers, landlords, utilities and chipmakers, but these businesses occupy different points in the value chain. One company’s purchase is another’s revenue; it is not necessarily proof that the final customer has achieved a worthwhile return.
An earnings dashboard worth publishing
| Metric | Bullish interpretation | Caution sign |
|---|---|---|
| Cloud revenue growth | Customers expand workloads | Growth relies on aggressive discounts |
| Capex as share of operating cash flow | Disciplined build-out | Spending consumes most available cash |
| AI contract backlog | Visibility into future demand | Backlog fails to convert to recognised revenue |
| Gross and operating margins | Pricing power survives cost growth | Inference/depreciation erodes economics |
| Data-centre power availability | Capacity arrives on schedule | Grid constraints delay utilisation |
Investors should watch change rather than one quarter’s absolute number. Management promises can be sincerely made and still prove wrong because of shifts in model architecture, regulation or competition.
The comparison with earlier infrastructure booms
New technology frequently requires substantial upfront investment. Railroads, telecommunications networks and the internet all created enormous social value; not every infrastructure owner earned equally attractive returns. AI may follow a similar pattern: productivity benefits can be large while the firms funding initial construction achieve uneven shareholder outcomes.
That possibility is not an argument against AI. It is an argument against confusing technology adoption with investment profitability. The latter requires credible unit economics, durable customer demand and disciplined financing. Rising bond yields raise the hurdle further by making the cost of capital less forgiving.
The return-on-capital test
A business that spends billions on new servers should eventually earn returns exceeding the economic cost of tying up that capital. To assess this, investors can compare incremental operating profit with the capital added to the business, allowing for taxes, depreciation and replacement spending. The exercise is imperfect because companies rarely disclose every cost of a specific AI product, but it is more meaningful than comparing investment announcements alone.
Training and inference also have different economics. Training large systems demands concentrated computing resources, while inference costs recur as customers use the service. Falling computing cost per query can make AI applications more attractive, but intense competition may pass those savings to customers rather than to the company providing the model. Revenue growth can therefore outpace profit growth.
Long-term contracts deserve close reading. A headline backlog may offer visibility but not guarantee immediate cash receipts or eliminate counterparty risk. Construction delays and power shortages can further separate announced spending from commercially available capacity.
The decisive quarterly question is whether management can demonstrate improving monetisation per unit of infrastructure. Without that evidence, investors are being asked to capitalise promised future demand at a time when the cost of financing that promise is significant.
Does rising AI spending prove that demand is strong?
It signals corporate confidence about future demand, not guaranteed utilisation or profits.
What matters more: earnings or free cash flow?
Both. Earnings capture business performance under accounting rules; free cash flow helps judge capacity to finance spending without additional borrowing or dilution.
Could AI still transform the economy if stocks disappoint?
Yes. Economic benefits to consumers and businesses need not be captured by every investor funding the technology.
The thesis for this earnings season: the market already knows that the machines are powerful. What it wants to know now is whether owning those machines is a profitable business.

Diesel Prices 2026–2027: Why Cheaper Crude May Not Mean Cheap Fuel

2027 Social Security COLA: Key Details and Dates

KSE-100 Sees Major Drop Post-SBP Rate Hike

Big Tech’s AI Spending Test: Can Revenue Catch Up With Capital Expenditure?

AI Infrastructure Investment Strategies for 2026

Pakistan Freelancers Tax 2026: Payments, Documentation and Formal Growth

Strait of Hormuz Crisis: What the Latest Tanker Attacks Mean for Oil, Shipping and Global Trade

AI Customer Service in 2026: What’s Working, What’s Failing, and What to Buy

Open a Savings Account Online: How to Actually Earn 10x the National Average Rate

Global Housing Market 2026: Where Prices Rise, Where They Don’t

PSX and KSE-100 Record Highs: An Insider’s Guide to Pakistan Stocks

So Delicious Dessert Recall: Affected Products, FDA Guidelines, and Consumer Action

Pakistan’s Current Account Deficit Narrows Sharply to $98 Million in August 2026

Japan Eyes 3.5% Defense Spending: What It Means for Bonds, Stocks, and the BOJ

Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities

Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World

Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns

China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech

What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact

15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025

How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide

Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide

Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
-
 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
 Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
 Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
 Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
 AI11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
 Exports11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025