
Investment
Consumer Discretionary Stocks Face Q4 Reckoning: Winners, Losers, and Where Smart Money Is Flowing

Consumer discretionary stocks enter Q4 earnings with stark divergence. Our expert analysis reveals top-rated winners, struggling laggards, and actionable investment strategies for this pivotal earnings season.
The consumer discretionary sector stands at a crossroads that most retail investors aren’t seeing clearly.
As Q4 earnings season accelerates, I’m watching a fascinating divergence unfold—one that separates the companies genuinely thriving from those merely surviving on borrowed time and hopeful press releases. After fifteen years analyzing market cycles and political-economic intersections, I can tell you this: the current setup in consumer discretionary stocks represents one of the most asymmetric risk-reward environments I’ve witnessed since the post-pandemic reopening trade.
Here’s what’s keeping me up at night—and what’s got me genuinely excited.
The Consumer Discretionary Select Sector SPDR Fund (XLY) has delivered impressive returns, yet beneath that headline number lies a tale of two markets. A handful of mega-cap names have dragged the index higher while dozens of mid-cap retailers and leisure companies struggle with margin compression, inventory gluts, and a consumer who’s growing increasingly selective about where discretionary dollars flow.
According to FactSet’s latest earnings analysis, Q4 earnings growth expectations for the consumer discretionary sector hover around 13%—notably above the S&P 500’s blended estimate. But averages deceive. The spread between winners and losers in this sector has widened to levels that demand your attention.
Let me walk you through exactly where I see opportunity, where I see danger, and how I’m thinking about positioning for what comes next.
The Macroeconomic Landscape: Reading the Consumer’s Mind
Before diving into individual stocks, we need to understand the economic backdrop shaping consumer behavior. And frankly, the picture is more nuanced than the bulls or bears want to admit.
The U.S. economy has demonstrated remarkable resilience. Bureau of Economic Analysis data shows GDP growth maintaining momentum, defying the recession predictions that dominated headlines throughout 2023 and much of 2024. Consumer spending—which drives roughly 70% of economic output—has remained robust, though the composition of that spending tells a more complex story.
Here’s what I find particularly telling: consumers are spending, but they’re trading down within categories and becoming ruthlessly value-conscious. The Conference Board’s Consumer Confidence Index has stabilized, yet the “present situation” component consistently outperforms the “expectations” component. Translation? People feel okay about today but harbor genuine concerns about tomorrow.
The Federal Reserve’s policy trajectory adds another layer of complexity. After the aggressive rate-hiking cycle, the central bank has pivoted toward a more accommodative stance, with rate cuts providing tailwinds for consumer credit and big-ticket purchases. Federal Reserve economic projections suggest a continued easing bias, which historically benefits consumer discretionary stocks—particularly those in housing-adjacent categories and durable goods.
But here’s where my political economy lens becomes crucial: we’re navigating a post-election environment with significant policy uncertainty. Trade policy, tax policy, and regulatory frameworks remain in flux. Companies with domestic supply chains and pricing power hold structural advantages over those dependent on complex international logistics or razor-thin margins.
Unemployment remains historically low, but the labor market has cooled from its white-hot 2022-2023 levels. Wage growth has moderated, and while that’s disinflationary (positive for Fed policy), it also suggests consumers face constraints that weren’t present eighteen months ago.
The net effect? A bifurcated consumer. High-income households continue spending on experiences, luxury goods, and premium products. Middle and lower-income consumers are stretching budgets, hunting for deals, and deferring discretionary purchases when possible. The companies positioned to serve both segments—or dominating one definitively—will outperform. Those stuck in the middle face brutal margin pressure.
Top-Rated Consumer Discretionary Stocks: Where Strength Meets Opportunity
After analyzing earnings estimates, analyst revisions, fundamental metrics, and qualitative competitive positioning, these consumer discretionary stocks stand out as Q4 winners with continued upside potential.
Amazon (AMZN): The Undisputed Category Killer
I’ll start with the obvious one because ignoring Amazon in any consumer discretionary analysis would be analytical malpractice.
Amazon’s Q4 setup looks exceptionally strong. Bloomberg Intelligence estimates project AWS revenue growth reaccelerating, while the core e-commerce business benefits from holiday seasonality and improved fulfillment efficiency. The advertising segment—often overlooked—has become a high-margin cash machine that subsidizes competitive pricing in retail.
What excites me most isn’t the headline numbers but the margin trajectory. Amazon’s North American retail segment has swung to consistent profitability after years of investment-phase losses. Operating leverage is finally materializing, and Q4’s volume surge should amplify this dynamic.
Current analyst consensus shows overwhelming buy ratings, with price targets suggesting 15-25% upside. At roughly 35x forward earnings, Amazon isn’t cheap by traditional metrics—but traditional metrics miss the AWS optionality and advertising growth runway.
My Take: Amazon remains a core holding for any growth-oriented investor. Q4 earnings should catalyze the next leg higher. I’m particularly watching management commentary on AI infrastructure spending and international profitability improvements.
Costco Wholesale (COST): The Recession-Proof Compounder
Costco defies easy categorization. Yes, it’s a consumer staples business at its core. But the discretionary upside from membership fees, ancillary services, and big-ticket items like electronics and furniture warrants inclusion here.
The membership model creates one of the most durable competitive moats in retail. Morningstar analysis highlights Costco’s 93% membership renewal rate—a staggering figure that speaks to genuine customer loyalty rather than mere convenience.
Q4 typically delivers Costco’s strongest comparable sales growth, driven by holiday entertaining, gift purchases, and seasonal merchandise. The company’s treasure-hunt shopping experience generates the kind of excitement that drives traffic even when consumers claim they’re cutting back.
Valuation gives me pause—Costco trades at a premium that prices in considerable future growth. But premium businesses deserve premium valuations, and Costco’s execution consistency justifies investor confidence.
My Take: Costco belongs in portfolios as a quality compounder. Don’t expect explosive upside, but do expect steady outperformance and downside protection during market turbulence.
Royal Caribbean Group (RCL): The Experience Economy Winner
Here’s where I break from consensus caution.
Cruise lines remain under-owned by institutional investors scarred by pandemic-era balance sheet destruction. But Royal Caribbean’s transformation has been remarkable. CNBC reported record booking levels and yield growth that’s exceeding pre-pandemic peaks on a real basis.
The demand story is simple: consumers—especially affluent Boomers—are prioritizing experiences over things. Cruising offers exceptional value compared to land-based vacations, with all-inclusive pricing that resonates in an inflationary environment. Royal Caribbean’s private island investments and fleet modernization have elevated the product while competitors struggle with older ships and weaker balance sheets.
Q4 earnings should reflect strong Wave Season booking momentum (the January-March period when cruise lines book 60%+ of annual capacity). Management’s pricing power commentary will be closely watched.
My Take: Royal Caribbean offers compelling risk-reward at current levels. The stock has run significantly, but earnings power continues expanding. I’m overweight cruise lines generally and RCL specifically.
Chipotle Mexican Grill (CMG): Fast-Casual Excellence
Chipotle has become the template for fast-casual success, and Q4 should demonstrate why.
Traffic growth—not just price increases—drives Chipotle’s comparable restaurant sales. That’s rare in the current environment and speaks to genuine brand strength. Wall Street Journal coverage noted Chipotle’s successful navigation of ingredient cost inflation while maintaining quality—a balancing act most competitors failed.
The Chipotlane drive-through format expansion addresses the convenience gap that historically limited occasion growth. Digital sales penetration remains elevated post-pandemic, improving order accuracy and labor efficiency.
New unit growth provides the compounding engine: each new restaurant generates returns on invested capital that justify aggressive expansion. Management’s guidance suggests sustained 8-10% annual unit growth, with newer formats delivering improved economics.
My Take: Chipotle deserves its premium multiple. Q4 should reinforce the thesis. My only concern is valuation—at 45x+ forward earnings, execution must remain flawless. Any comparable sales miss would punish the stock severely.
Home Depot (HD): Housing Recovery Beneficiary
Home Depot’s Q4 setup reflects a sector rotation opportunity.
The housing market is stirring. Mortgage rates have declined from cycle highs, and Reuters reported improving homebuilder sentiment and existing home sales stabilization. Every housing transaction generates thousands of dollars in home improvement spending—and Home Depot captures disproportionate share.
The professional contractor segment provides stability through housing cycles, while the DIY consumer responds to interest rate relief and accumulated home equity wealth. Home Depot’s supply chain investments during the pandemic created competitive advantages that persist.
Analyst estimates have begun revising higher after extended negativity. The stock has outperformed in anticipation, but earnings confirmation could drive continued rerating.
My Take: Home Depot represents a quality cyclical at reasonable valuations. I prefer it over Lowe’s given superior execution and professional segment strength. Accumulate on pullbacks.
Lowest-Rated Consumer Discretionary Stocks: Where Caution Is Warranted
Not every consumer discretionary stock deserves your capital. These companies face structural challenges that Q4 earnings are unlikely to resolve.
Nike (NKE): The Fallen Giant
It pains me to write this. Nike is an iconic American brand—and a stock I owned for years. But the company’s competitive position has deteriorated in ways that demand acknowledgment.
Yahoo Finance analyst coverage highlights Nike’s market share losses to upstarts like On Running, Hoka, and resurgent competitors like New Balance and Adidas. The direct-to-consumer pivot, initially celebrated, has alienated wholesale partners without delivering promised margin benefits.
China exposure compounds problems. The Chinese consumer discretionary market has struggled with property sector contagion and youth unemployment, pressuring a region that historically delivered outsized growth.
Innovation has stalled. When was Nike’s last genuinely exciting product launch? The running community has largely abandoned the brand, and basketball—Nike’s heritage sport—increasingly features athletes in competitor footwear.
Q4 earnings may stabilize sentiment temporarily, but the fundamental challenges require years of reinvestment and cultural change to address.
My Take: Nike is a value trap until proven otherwise. The dividend provides modest support, but capital appreciation potential appears limited. I’m avoiding the stock despite apparent valuation support.
Dollar General (DG): Structural Deterioration
Dollar General’s challenges transcend cyclical weakness.
The thesis was simple: inflation-pressured consumers would trade down to dollar stores. Reality proved more complicated. Seeking Alpha analysis documented comparable sales weakness, inventory management failures, and execution stumbles that forced management turnover.
Shrinkage (theft) has become an existential issue for discount retailers operating in urban and semi-urban locations. Dollar General’s store count growth—previously a competitive advantage—now looks like overexpansion into marginal locations.
Competition from Walmart’s aggressive everyday low pricing and Amazon’s expanding household essentials presence squeezes Dollar General from above and below simultaneously.
My Take: Dollar General requires a proven turnaround before warranting investment. The stock appears cheap, but cheap can become cheaper when fundamental trends deteriorate. There are better places to hunt for value.
Tesla (TSLA): Volatility Without Commensurate Reward
I’ll catch criticism for this one. Tesla inspires passionate devotion among shareholders who view any skepticism as blasphemy.
But let’s examine the consumer discretionary fundamentals objectively.
Tesla’s automotive gross margins have compressed significantly as price cuts defend market share against Chinese EV manufacturers and legacy automakers’ accelerating electrification efforts. MarketWatch noted the company’s sequential delivery growth has decelerated, raising questions about demand elasticity.
Elon Musk’s distraction with other ventures creates governance concerns that institutional investors increasingly acknowledge. The robotaxi narrative, while potentially transformative, remains speculative with uncertain timelines.
Valuation assumes perfection. Any execution stumble—demand weakness, production issues, competitive pressure—punishes the stock disproportionately given elevated expectations embedded in the current price.
My Take: Tesla is a trading vehicle, not an investment for most portfolios. The risk-reward at current valuations skews negatively for Q4 and beyond. I’m neutral-to-bearish and would consider short exposure on rallies.
Starbucks (SBUX): Identity Crisis Brewing
Starbucks faces a problem money can’t easily solve: brand perception decay.
The new CEO inherits a company that has lost its way. Is Starbucks a premium experience or a convenient caffeine dispensary? The mobile order surge transformed stores into chaotic pickup locations that alienate the customers willing to pay premium prices for ambiance.
China, which was supposed to become Starbucks’ largest market, has disappointed consistently. Local competitors offer comparable quality at lower prices, and nationalism has created headwinds for American brands broadly.
Labor relations have become contentious, with unionization efforts creating operational uncertainty and potential cost pressures. Financial Times coverage documented the extent of worker grievances and their potential impact on store-level execution.
My Take: Starbucks requires patience I’m not prepared to exercise. The turnaround thesis depends on execution from a management team still defining its strategy. Better opportunities exist elsewhere.
Peloton (PTON): The Cautionary Tale Continues
Peloton serves as a reminder that pandemic beneficiaries weren’t necessarily good businesses—just temporary demand surges mistaken for sustainable competitive advantages.
The connected fitness company continues bleeding cash, losing subscribers, and searching for a viable path forward. Various strategic alternatives have been explored and abandoned. The hardware business faces commoditization while the subscription content competes with free YouTube workouts and lower-cost alternatives.
Recent quarters have shown stabilization, but stabilization at depressed levels isn’t victory. Investopedia analysis questioned whether Peloton can generate sustainable profitability even under optimistic scenarios.
My Take: Peloton is uninvestable for anyone focused on fundamental value. Speculative short-covering rallies create short opportunities rather than buying opportunities. Avoid.
Sector Comparison Table
| Stock | Ticker | Rating | P/E (Fwd) | Q4 EPS Est. | Analyst Target | Risk Level |
|---|---|---|---|---|---|---|
| Amazon | AMZN | Strong Buy | 35x | $1.82 | $230 | Moderate |
| Costco | COST | Buy | 52x | $3.79 | $1,050 | Low |
| Royal Caribbean | RCL | Buy | 14x | $1.45 | $250 | Moderate-High |
| Chipotle | CMG | Buy | 47x | $0.28* | $70 | Moderate |
| Home Depot | HD | Buy | 24x | $3.02 | $425 | Low-Moderate |
| Nike | NKE | Hold | 27x | $0.85 | $82 | Moderate |
| Dollar General | DG | Hold | 14x | $1.58 | $95 | High |
| Tesla | TSLA | Hold | 85x | $0.75 | $285 | Very High |
| Starbucks | SBUX | Hold | 25x | $0.80 | $105 | Moderate-High |
| Peloton | PTON | Sell | N/A | -$0.28 | $5 | Very High |
*Post-split adjusted
Investment Strategy and Outlook: Positioning for What Comes Next
Let me synthesize these individual assessments into an actionable framework.
The consumer discretionary sector offers genuine opportunity—but selection matters enormously. The days of rising-tide-lifts-all-boats sector allocation ended when easy monetary policy gave way to higher rates and discriminating consumers.
Quality Over Value: This isn’t the environment to bottom-fish in struggling retailers hoping for mean reversion. Companies with pricing power, strong balance sheets, and differentiated offerings will capture share from weakened competitors. Pay up for quality and sleep better.
Barbell Your Exposure: I’m simultaneously overweight premium experiences (cruises, travel) and defensive growth (Costco, Amazon). The middle—moderately priced discretionary goods without brand differentiation—faces the most competitive pressure.
Watch the Consumer Credit Data: Consumer credit card delinquencies have ticked higher, though from low bases. If this trend accelerates, discretionary spending will compress faster than optimistic Q4 estimates assume. Federal Reserve consumer credit data deserves monthly monitoring.
Respect Earnings Season Volatility: Individual stock moves of 10-15% post-earnings are common in this environment. Size positions appropriately, and consider using options strategies to define risk around binary events.
Think Beyond Q4: The most compelling opportunities emerge when short-term challenges create long-term entry points. I’m building watchlists of quality companies that might stumble—not because their businesses are impaired, but because expectations grew excessive.
My twelve-month outlook for consumer discretionary remains constructive but selective. The sector offers alpha generation potential for active investors willing to do the work distinguishing winners from losers. Passive XLY exposure captures the sector beta but misses the dispersion opportunity.
Conclusion: The Earnings Season That Separates Pretenders From Contenders
Q4 earnings season will reveal truths that year-to-date performance has obscured.
Some consumer discretionary stocks trading at premium valuations will justify those multiples with blowout results and confident guidance. Others will stumble, exposing the fragility beneath headline numbers. The gap between expectations and reality drives stock prices—and that gap appears wider in consumer discretionary than any other sector I’m tracking.
I’ve shared my highest-conviction ideas: Amazon and Costco for foundational quality, Royal Caribbean and Home Depot for cyclical exposure, Chipotle for growth. I’ve flagged my concerns: Nike’s competitive erosion, Tesla’s valuation risk, Dollar General’s execution failures, Starbucks’ identity crisis, Peloton’s existential uncertainty.
Your job now is to stress-test these conclusions against your own research, risk tolerance, and portfolio construction needs. No analyst gets every call right—humility about uncertainty is essential to long-term investing success.
What I know with confidence: the consumer discretionary stocks that emerge from Q4 earnings season as winners will compound that advantage through 2025 and beyond. Those that disappoint will face extended periods of multiple compression and investor skepticism.
Choose wisely. The market is offering a clarifying moment—don’t waste it chasing yesterday’s winners or averaging down into deteriorating businesses.
The consumer is speaking through their spending choices. Are you listening?
Frequently Asked Questions (FAQ)
What are consumer discretionary stocks?
Consumer discretionary stocks represent companies selling non-essential goods and services that consumers purchase when they have disposable income. This sector includes retailers, restaurants, hotels, automakers, entertainment companies, and luxury goods manufacturers. Performance typically correlates with economic cycles and consumer confidence levels.
Which consumer discretionary stocks are best for Q4 earnings?
Based on current analyst ratings, earnings revisions, and fundamental strength, Amazon (AMZN), Costco (COST), Royal Caribbean (RCL), Chipotle (CMG), and Home Depot (HD) appear best-positioned for Q4 earnings outperformance. Each demonstrates pricing power, strong execution, and favorable demand trends heading into the holiday quarter.
Why do consumer discretionary stocks perform differently in Q4?
Q4 represents peak seasonality for consumer discretionary stocks due to holiday shopping, travel, and entertainment spending. Companies generate disproportionate revenue and earnings during this quarter, making year-over-year comparisons particularly meaningful. Weather, consumer confidence, and promotional intensity all influence Q4 performance variance.
What economic factors affect consumer discretionary stocks?
Consumer discretionary stocks respond to employment levels, wage growth, consumer confidence, interest rates, inflation, housing market conditions, and overall GDP growth. Federal Reserve policy significantly impacts financing costs for big-ticket purchases. Political and trade policy uncertainty can also influence consumer and business spending decisions.
Should I buy consumer discretionary stocks before earnings?
Buying before earnings introduces binary event risk—stocks can move sharply in either direction regardless of fundamental quality. Consider building positions gradually, using limit orders on pullbacks, or employing options strategies to define risk. Long-term investors focused on quality companies can use earnings volatility as entry opportunities rather than timing events.


The SPDR S&P 500 ETF Trust (SPY) enters September 2026 trading around 7–14% above GuruFocus’s proprietary GF Value intrinsic-value estimate, depending on the week’s model inputs, with the index near record highs after an roughly 11–12% year-to-date gain. Unlike the rate-cut narrative that dominated markets earlier in the summer, the 10-year Treasury’s climb to 4.80% and hawkish Federal Reserve commentary now point toward markets pricing meaningful odds of a rate hike, not a cut, at this month’s FOMC meeting — a reversal that changes the valuation math for equities.
SPY Valuation Snapshot: Late August Into September 2026
| Date | SPY Price | GF Value™ (Intrinsic) | Overvaluation | GF Score™ | S&P 500 Level |
|---|---|---|---|---|---|
| Aug 6, 2026 | $768.31 | $685.35 | 12.1% | 85/100 | ~7,705 |
| Aug 10, 2026 | $773.26 | $702.96 | 10.0% | 86/100 | — |
| Aug 11, 2026 | $772.84 | $702.96 | 9.9% | 86/100 | — |
| Aug 17, 2026 | $776.34 | $705.76 | 10.0% | 86/100 | — |
| Aug 18, 2026 | $767.87 | $705.76 | 8.8% | 86/100 | — |
| Aug 19, 2026 | $769.45 | $705.76 | 9.0% | 86/100 | — |
| Aug 20, 2026 | $769.06 | $705.76 | 9.0% | 86/100 | — |
| Aug 25, 2026 | $765.67 | $715.63 | 7.0% | 86/100 | 7,665 (+11.4% YTD) |
| Aug 30, 2026 | $769.35 | $674.87 | 14.0% | 86/100 | — |
Note: GF Value estimates shift week to week as GuruFocus’s model incorporates new earnings, growth, and macro data — the fluctuation itself (from 7.0% to 14.0% overvalued within a single month) is a useful reminder that any single-day valuation snapshot is a moving target, not a fixed verdict.
| Rate/Bond Metric | Level (Sept 1, 2026) |
|---|---|
| 10-Year Treasury yield | 4.80% (highest since January 2025) |
| 30-Year Treasury yield | 5.28% |
| 2-Year Treasury yield | 4.39% |
| Market-implied odds of a Fed rate hike this month | ~68%, up from ~40% the prior week |
| SPY trailing P/E (TTM) | ~23.7x |
Sources: GuruFocus GF Value daily/weekly valuation notes (Aug 6–30, 2026); TradingEconomics, MacroMicro, and StreetStats Treasury yield data (Sept 1, 2026).
Deep Dive: A Valuation Picture Complicated by a Rate Story That Just Flipped
GF Value Says “Modestly to Meaningfully Overvalued,” But the Range Matters More Than Any Single Print
GuruFocus’s GF Value model — which blends historical trading multiples, business growth trends, and forward performance estimates into a single intrinsic-value estimate — has placed SPY anywhere from roughly 7% to 14% above fair value at various points across August 2026 alone. That’s not model inconsistency so much as it reflects genuinely volatile inputs: intrinsic value estimates move as new earnings data, Treasury yields, and macro releases feed the model, while the market price itself has been chopping in a roughly $765–$777 band.
The consistent signal across every reading, regardless of the exact overvaluation percentage: SPY’s GF Score — a composite of financial strength, profitability, growth, valuation, and momentum — has held steady in the 85–86 out of 100 range throughout the period. In plain terms, the model is saying the same thing every week: fundamentals underneath the index remain genuinely strong (profitability and growth sub-scores of 8/10), but the price paid for those fundamentals leaves a thin-to-negative margin of safety for new money entering at current levels.
The Bigger Story: The Fed Narrative Just Reversed
This is the detail most surface-level coverage of SPY valuation is missing entering September: the market’s rate-path assumption flipped over the course of late August. Earlier in the summer, a weak July jobs report and cooling CPI prints had markets leaning toward the possibility of rate cuts later in the year. By the final week of August, that had reversed. Fed Chair Warsh’s remarks at the Jackson Hole symposium reaffirmed a commitment to bringing inflation down, and Fed Governor Barr followed with comments that the central bank should be prepared to raise rates if inflation does not subside. The market reaction was immediate: odds of a 25-basis-point hike this month jumped from around 40% to roughly 68% within a single week, and the 10-year Treasury yield climbed for five consecutive sessions to reach 4.80% — its highest level since January 2025.
The proximate driver of the inflation concern is oil. Renewed geopolitical tensions have pushed crude prices higher, and rising energy costs are feeding directly into inflation expectations at a moment when the labor market — job openings edged higher in July, layoffs fell, and manufacturing expanded for an eighth straight month in August — is not showing the kind of softness that would normally take a hike off the table.
Why Rising Long-Term Yields Compress Equity Valuation Models
Every discounted-cash-flow-style valuation — including the general category of model GuruFocus’s GF Value falls into — is sensitive to the discount rate applied to future earnings. When the 10-year Treasury yield rises from a level closer to 4.3% (its trailing 12-month average) to a fresh cycle high of 4.80%, the “risk-free” comparison rate against which equity earnings yields are judged rises with it. All else equal, a higher discount rate lowers the intrinsic value estimate for the same stream of future earnings — which is part of why GF Value estimates for SPY have generally trended toward higher overvaluation readings as yields have climbed through August, even as the S&P 500 itself continued grinding higher.
The Seasonal Overlay: September’s Historical Track Record
Independent of valuation or rates, the calendar itself carries a well-documented pattern: the back half of September has historically been the weakest stretch of the trading year for the S&P 500, producing slightly negative average returns more often than any other multi-week period. That seasonal headwind, layered on top of a rate environment that just turned more hawkish and a valuation model flashing high-single to low-double-digit overvaluation, is the combination coverage of SPY heading into September 2026 should actually be weighing — not any single data point in isolation.
What a 23.7x Trailing P/E Actually Tells You
SPY’s trailing twelve-month P/E of approximately 23.7x sits meaningfully above long-run historical averages for the index (commonly cited in the high teens), though comparisons are complicated by the absence of a readily available 5-year median P/E in the underlying data used for this analysis — a data-availability gap GuruFocus itself has flagged in several of its own valuation notes. Investors should treat any single trailing-multiple comparison as one input among several (GF Value, GF Score, rate environment, seasonal pattern) rather than a standalone verdict.
Actionable Takeaways for Investors
- Don’t anchor to a single GF Value overvaluation percentage. The swing from 7.0% to 14.0% overvalued within the same month shows the model is sensitive to short-term inputs; look at the trend and the GF Score (steady at 85–86) together, not one week’s headline number.
- Track the 10-year Treasury yield as a leading valuation signal. A continued climb toward or past 4.80–5.00% would mechanically pressure equity valuation models further; a reversal back toward the 4.30% trailing average would ease that pressure.
- Reassess the “rate cut” assumption baked into your portfolio. If your equity allocation was built assuming Fed easing later in 2026, the shift toward hike odds of ~68% for this month’s meeting is a material change worth revisiting with a financial advisor.
- Respect September seasonality without overreacting to it. Historical weak-September patterns are a real, well-documented statistical tendency, not a guarantee — use it as a reason for disciplined position sizing rather than a market-timing signal on its own.
- Watch oil prices as the connective tissue between geopolitics, inflation, and equity valuation. The current inflation concern feeding into hike odds is substantially an energy-price story; a de-escalation in the geopolitical tensions driving crude higher would likely ease both bond yields and equity valuation pressure simultaneously.
Frequently Asked Questions
Is the S&P 500 overvalued right now? By GuruFocus’s GF Value metric, SPY has traded between roughly 7% and 14% above its estimated intrinsic value at various points across August 2026, with a GF Score of 85–86 out of 100 indicating strong underlying fundamentals despite the valuation premium — the honest answer is “modestly to meaningfully” overvalued depending on which week’s model reading you use, not overvalued by one fixed number.
Will the Federal Reserve raise or cut interest rates in September 2026? As of early September 2026, market pricing has shifted toward pricing in meaningful odds (around 68%) of a rate hike rather than a cut, reversing the rate-cut expectations that dominated earlier in the summer, driven by hawkish Fed commentary at Jackson Hole and rising oil-driven inflation concerns.
Why did the 10-year Treasury yield hit 4.80% in September 2026? The 10-year Treasury yield climbed for five consecutive sessions to reach 4.80% — its highest level since January 2025 — driven by rising oil prices amid renewed geopolitical tensions and hawkish signals from Federal Reserve officials suggesting a rate hike may be needed to control inflation.
How does September seasonality typically affect the S&P 500? Historically, the latter half of September has been the weakest multi-week stretch of the trading year for the S&P 500, often producing slightly negative average returns, though this is a statistical tendency rather than a reliable predictor for any specific year.
Analysis
FHS Saudi Arabia 2026 Opens in Riyadh, Drawing Investors Representing Nearly $5 Trillion in Assets
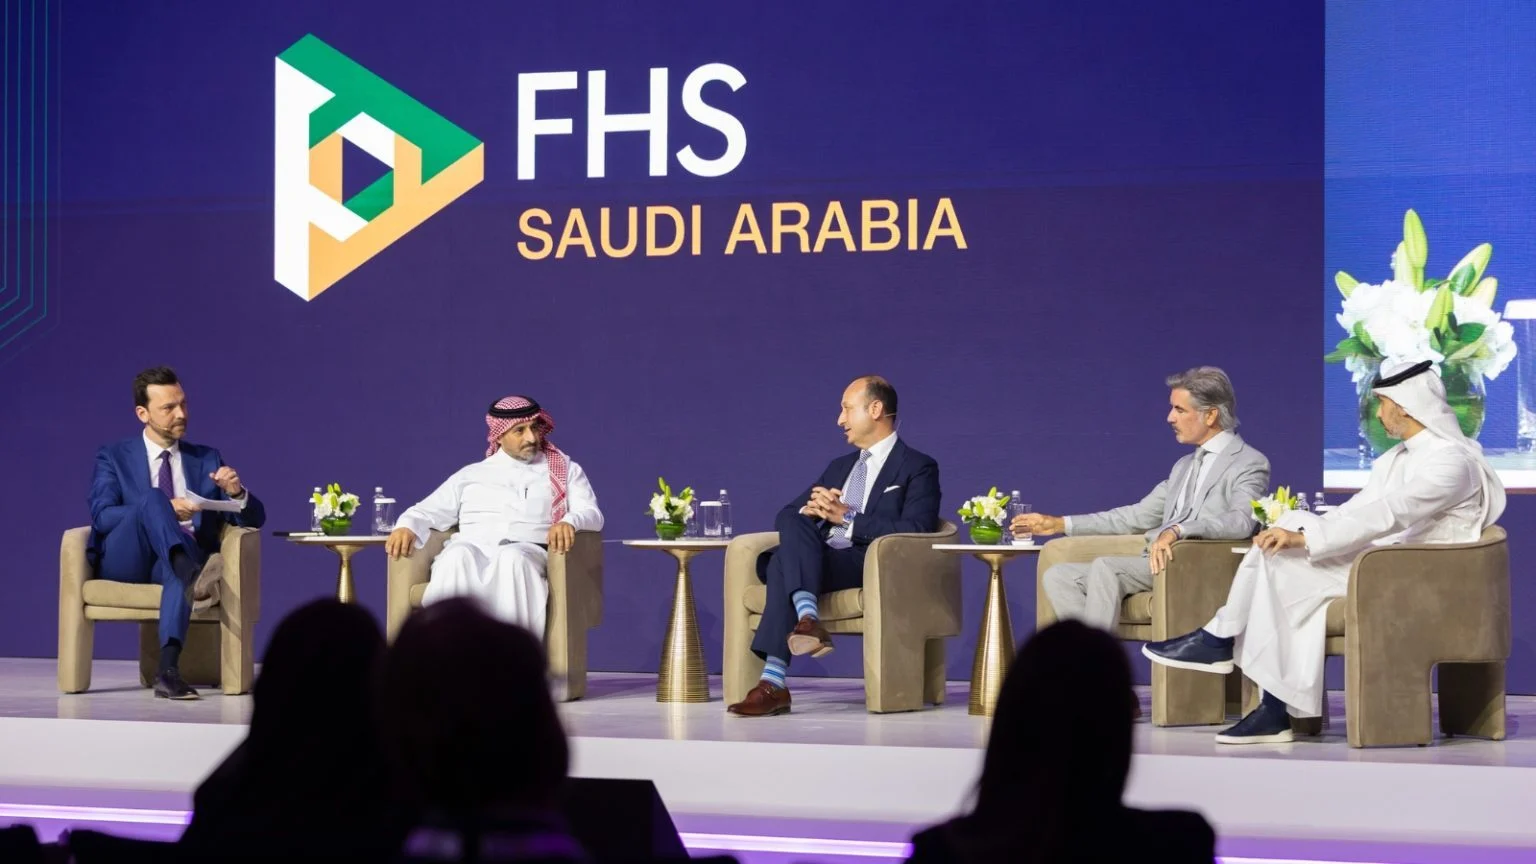
The Future Hospitality Summit (FHS) Saudi Arabia 2026 opens this week at the Mandarin Oriental Al Faisaliah in Riyadh, running June 22–24 and positioning itself as the Kingdom’s leading hospitality deal-making forum for the year. Organizers say attendees represent investors managing roughly $4.99 trillion in assets under management, underscoring the scale of capital now circling Saudi Arabia’s hospitality and tourism investment pipeline.
The timing is notable. The summit arrives even as the broader Middle East travel sector works through a difficult stretch — regional hotel occupancy and air capacity both fell sharply earlier in the year amid conflict-related disruption. Saudi Arabia’s hospitality investment push has continued largely undeterred, reflecting the Kingdom’s long-term tourism diversification strategy under Vision 2030, which has driven sustained hotel development, giga-project investment, and international brand expansion regardless of near-term regional volatility.
A Magnet for Global Capital
FHS Saudi Arabia has grown into one of the region’s most closely watched investment gatherings, bringing together hotel owners, operators, private equity investors, and sovereign capital to negotiate deals and discuss the Kingdom’s pipeline of new developments. The scale of capital represented by attendees — nearly $5 trillion — signals continued confidence among major institutional investors in Saudi Arabia’s hospitality growth story, even as some neighboring markets navigate near-term demand volatility.
Part of a Broader Investment Push
The summit’s opening coincides with a wider industry conversation about how governments can attract and retain private tourism investment. The World Travel & Tourism Council recently unveiled a seven-principle framework aimed at giving governments a practical roadmap — covering legal stability, fiscal incentives, and master planning — for courting exactly this kind of capital. Saudi Arabia’s continued ability to draw large-scale investor attendance to Riyadh suggests its approach is, for now, resonating with the institutional investment community.
What to Watch
Deal announcements, new hotel brand entries, and updates on giga-project hospitality components are expected to dominate headlines over the three-day event, with global hotel groups likely to use the summit to detail expansion plans across the Kingdom’s tourism corridors.
Investing 101
Gaming Giant’s Bold Gamble: Why Investors are Devouring Risky EA Debt Amid Geopolitical Crosscurrents
Investors are aggressively snapping up debt for Electronic Arts’ historic $55bn take-private, signaling resilient credit markets despite geopolitical tensions and AI disruption. Explore the EA LBO’s financial engineering, cost savings, and the appetite for risky video game financing in 2026.
Introduction: The Unyielding Allure of High-Yield
The world of high finance rarely pauses for breath, even as geopolitical headwinds gather and technological disruption reshapes industries. Yet, the recent $55 billion take-private of video game titan Electronic Arts (EA) has delivered a masterclass in market resilience, demonstrating an almost insatiable investor appetite for leveraged debt—even when tied to a complex, globally-infused transaction. Led by Saudi Arabia’s Public Investment Fund (PIF), Silver Lake, and Affinity Partners, this landmark deal, poised to redefine the gaming M&A landscape, has seen its $18-20 billion debt package met with overwhelming demand, proving that the pursuit of yield often eclipses lingering doubts.
This isn’t merely another private equity mega-deal; it’s a bellwether for global credit markets in early 2026. JPMorgan-led bond deals, designed to finance one of the largest leveraged buyouts in history, have drawn over $25 billion in orders, far surpassing their target size. This aggressive investor embrace of what many consider risky debt, particularly given the backdrop of Middle East tensions and concerns over AI’s impact on software, underscores a fascinating dichotomy: a cautious macroeconomic outlook juxtaposed with an audacious hunt for returns in stable, cash-generative assets. The question isn’t just how this was financed, but why investors dove in with such conviction, and what it signals for the year ahead.
The Anatomy of a Mega-Buyout: EA’s Financial Engineering
At an enterprise value of approximately $55 billion, the Electronic Arts take-private deal stands as the largest leveraged buyout on record, eclipsing the 2007 TXU Energy privatization. The financing structure is a finely tuned orchestration of equity and debt, designed to maximize returns for the acquiring consortium while appealing to a broad spectrum of debt investors.
Equity & Debt Breakdown
The EA $55bn LBO is funded through a combination of substantial equity and a significant debt tranche:
- Equity Component: Approximately $36 billion, largely comprising cash contributions from the consortium partners, including the rollover of PIF’s existing 9.9% stake in EA. PIF is set to own a substantial majority, approximately 93.4%, with Silver Lake holding 5.5% and Affinity Partners 1.1%.
- Debt Package: A substantial $18-20 billion debt package, fully committed by a JPMorgan-led syndicate of banks. This makes it the largest LBO debt financing post-Global Financial Crisis.
Unpacking the Debt Tranches: Demand & Pricing
The sheer scale of demand for this EA acquisition financing has been striking. The initial $18 billion debt offering, which included both secured and unsecured tranches, quickly swelled to over $25 billion in investor orders. This oversubscription highlights a strong market appetite for gaming-backed paper.
Key components of the debt include:
- Leveraged Loans: A cross-border loan deal totaling $5.75 billion launched on March 16, 2026, comprising a $4 billion U.S. dollar loan and a €1.531 billion ($1.75 billion) euro tranche.
- Pricing: Term Loan Bs (TLBs) were guided at 350-375 basis points over SOFR/Euribor, with a 0% floor and a 98.5 Original Issue Discount (OID). This discounted pricing suggests lenders were baking in some risk, yet the demand remained robust.
- Secured & Unsecured Bonds: The financing also features an upsized $3.25 billion term loan A, an additional $6.5 billion of other dollar and euro secured debt, and $2.5 billion of unsecured debt. While specific high-yield bond pricing hasn’t been detailed, market intelligence suggests secured debt at approximately 6.25-7.25% and unsecured north of 8.75%, reflective of the leverage profile.
The Deleveraging Path: Justifying a 6x+ Debt/EBITDA
Moody’s projects that EA’s gross debt will increase twelve-fold from $1.5 billion, pushing pro forma leverage (total debt to EBITDA) to around eight times at closing. Such high leverage ratios typically raise red flags, but the consortium’s pitch centers on EA’s robust cash flows and significant projected cost savings.
Three Pillars Justifying the Leverage
- Stable Cash Flows from Core Franchises: EA boasts an enviable portfolio of consistently profitable franchises, including FIFA (now EA Sports FC), Madden NFL, Apex Legends, and The Sims. These titles generate predictable, recurring revenue streams, particularly through live service models and annual updates, which underpin the company’s financial stability—a critical factor for debt investors.
- Strategic Cost Savings & Operational Efficiencies: The new owners have outlined an aggressive plan for $700 million in projected annual cost savings. This includes:
- R&D Optimization: $263 million from reclassifying R&D expenses for major titles like Battlefield 6 and Skate as one-time costs, now that they are live and generating revenue.
- Portfolio Review: $100 million from a strategic review of the game portfolio.
- AI Tool Integration: $100 million from leveraging AI tools for development and operations.
- Organizational Streamlining: $170 million from broader organizational efficiencies.
- Public Company Cost Removal: $30 million saved by no longer incurring costs associated with being a public entity.
These add-backs significantly bolster adjusted EBITDA figures, making the debt package appear more manageable to prospective lenders. Moody’s expects leverage to decrease to five times by 2029.
- Untapped Growth Potential in Private Ownership: Freed from quarterly earnings pressure, EA’s management can pursue longer-term strategic initiatives and R&D without the immediate scrutiny of public markets. This is particularly appealing for a company operating in an industry prone to rapid innovation and large, multi-year development cycles. The consortium’s diverse networks across gaming, entertainment, and sports are expected to create opportunities to “blend physical and digital experiences, enhance fan engagement, and drive growth on a global stage”.
Geopolitical Currents and the Appetite for Risky Debt
The influx of capital into the Electronic Arts bond deals is particularly noteworthy given the complex geopolitical backdrop of early 2026. Global markets are navigating sustained tensions in the Middle East, the specter of trade tariffs, and the disruptive force of artificial intelligence. Yet, these factors have not deterred investors from snapping up debt to finance Electronic Arts’ $55bn take-private.
The Saudi PIF Factor: Geopolitical Implications
The prominent role of Saudi Arabia’s Public Investment Fund (PIF) as the lead equity investor introduces a significant geopolitical dimension. The PIF, managing over $925 billion in assets, views this acquisition as a strategic move to establish Saudi Arabia as a global hub for games and sports, aligning with its “Vision 2030” diversification efforts. PIF’s deep pockets and long-term investment horizon offer stability often attractive to private equity deals.
However, the involvement of a sovereign wealth fund, particularly one with ties to Jared Kushner’s Affinity Partners, has not been without scrutiny. Concerns about national security risks, foreign access to consumer data, and control over American technology (including AI) have been voiced by organizations like the Communications Workers of America (CWA), who urged federal regulators to scrutinize the deal. Despite these geopolitical and regulatory considerations, the debt market demonstrated a remarkable willingness to participate. This indicates that the perceived financial stability and growth prospects of EA outweighed concerns tied to the source of equity capital.
AI Disruption and Market Confidence
The gaming industry, like many sectors, faces potential disruption from AI. Yet, EA itself projects $100 million in cost savings from AI tools, signaling a strategic embrace rather than fear of the technology. This forward-looking approach to AI, coupled with the inherent stability of established gaming franchises, likely contributed to investor confidence. In a volatile environment, proven entertainment IP acts as a relatively safe harbor.
The successful placement of this jumbo financing also suggests that while some sectors (like software) have seen “broader risk-off sentiment” due to AI uncertainty, the market distinguishes between general software and robust, content-driven interactive entertainment.
Broader Implications for Gaming M&A and Private Equity
The EA LBO is more than an isolated transaction; it’s a powerful signal for the broader M&A landscape and the future of private equity.
A Return to Mega-LBOs?
After a period where massive leveraged buyouts fell out of favor post-Global Financial Crisis, the EA deal marks a definitive comeback. It “waves the green flag on sponsors resuming mega-deal transactions,” indicating that easing borrowing costs and renewed boardroom confidence are aligning to facilitate large-cap M&A. The success of this deal, especially the oversubscription of its debt tranches, could embolden other private equity firms to pursue similar-sized targets in industries with reliable cash flows. This is crucial for private-equity debt appetite in 2026.
Creative Independence Post-Delisting
While private ownership offers freedom from public market pressures, it also introduces questions about creative independence. Historically, private equity has been associated with aggressive cost-cutting and a focus on short-term profits. For a creative industry like gaming, this can be a double-edged sword. While the stated goal is to “accelerate innovation and growth”, some within EA have expressed concern about potential workforce reductions and increased monetization post-acquisition. The challenge for the new owners will be to balance financial optimization with the nurturing of creative talent and IP development crucial for long-term success.
What it Means for 2027: Scenarios and Ripple Effects
As the EA $55bn take-private moves towards its expected close in Q1 FY27 (June 2026), its ripple effects will be closely watched by analysts and investors alike.
- Post-Deal EA Strategy: Under private ownership, expect EA to double down on its most successful franchises and potentially explore new growth vectors less scrutinized by quarterly reports. Strategic investments in areas like mobile gaming, esports, and potentially new IP development could accelerate. The projected cost savings will likely be reinvested to fuel growth or rapidly deleverage.
- Valuation Multiples: The deal itself sets a new benchmark for valuations in the gaming sector, particularly for companies with strong IP and predictable revenue streams. This could influence future M&A activities involving peers like Activision Blizzard (though now part of Microsoft) or Take-Two Interactive, raising their perceived floor valuations.
- Credit Market Confidence: The overwhelming investor demand for EA’s debt signals a powerful confidence in the leveraged finance markets, particularly for well-understood, resilient businesses. If EA successfully executes its deleveraging and growth strategy post-buyout, it will further validate the market’s willingness to finance large, complex LBOs, even amidst global uncertainty. This could pave the way for more “risky debt” deals tied to stable, high-quality assets.
- Geopolitical Influence in Tech: The PIF’s leading role solidifies the trend of sovereign wealth funds actively participating in global technology and entertainment sectors. This influence will continue to shape discussions around regulatory oversight, national interests, and the evolving landscape of global capital flows.
The investors snapping up debt to finance Electronic Arts’ $55bn take-private aren’t just betting on a video game company; they’re wagering on the enduring power of stable cash flows, strategic cost management, and a robust credit market willing to absorb risk for attractive yields. In a world grappling with uncertainty, the virtual battlefields of EA’s franchises offer a surprisingly solid ground for real-world financial gains.

Diesel Prices 2026–2027: Why Cheaper Crude May Not Mean Cheap Fuel

2027 Social Security COLA: Key Details and Dates

KSE-100 Sees Major Drop Post-SBP Rate Hike

Big Tech’s AI Spending Test: Can Revenue Catch Up With Capital Expenditure?

AI Infrastructure Investment Strategies for 2026

Pakistan Freelancers Tax 2026: Payments, Documentation and Formal Growth

Strait of Hormuz Crisis: What the Latest Tanker Attacks Mean for Oil, Shipping and Global Trade

AI Customer Service in 2026: What’s Working, What’s Failing, and What to Buy

Open a Savings Account Online: How to Actually Earn 10x the National Average Rate

Global Housing Market 2026: Where Prices Rise, Where They Don’t

PSX and KSE-100 Record Highs: An Insider’s Guide to Pakistan Stocks

So Delicious Dessert Recall: Affected Products, FDA Guidelines, and Consumer Action

Pakistan’s Current Account Deficit Narrows Sharply to $98 Million in August 2026

Japan Eyes 3.5% Defense Spending: What It Means for Bonds, Stocks, and the BOJ

Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities

Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World

Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns

China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech

What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact

15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025

How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide

Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide

Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
-
 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
 Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
 Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
 Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
 AI11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
 Exports11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025