
China Economy
China’s Record $1.2 Trillion Trade Surplus in 2025 Defies Trump Tariffs — And Signals a New Global Order


Beijing’s strategic pivot to Southeast Asia, Africa, and Latin America pays dividends as Chinese exporters outmaneuver US trade barriers
On a humid January morning at Shenzhen’s Yantian Port, one of the world’s busiest container terminals, the rhythmic clang of cranes loading shipping containers tells a story that Washington policymakers didn’t anticipate. Despite President Donald Trump’s aggressive tariff regime, which slashed Chinese exports to the United States by roughly 20% in 2025, the port’s traffic has surged. The destination tags reveal the plot twist: Lagos, Jakarta, São Paulo, Ho Chi Minh City—everywhere, it seems, except American shores.
This scene encapsulates China’s remarkable trade performance in 2025. The country closed the year with a record-breaking trade surplus of approximately $1.19 trillion—a 20% jump from 2024’s $992 billion—according to data released January 14, 2026, by China’s General Administration of Customs. The figures represent not just a numerical milestone but a fundamental recalibration of global trade flows, one that challenges assumptions about America’s economic leverage and heralds what some analysts are calling a “post-Atlantic” trading order.
The Numbers: A Surplus Built on Strategic Diversification
China’s 2025 trade data reveals an economy executing a carefully orchestrated pivot. Total exports climbed 5.5% to $3.77 trillion, while imports remained virtually flat at $2.58 trillion, expanding the trade imbalance to unprecedented levels. December alone saw exports surge 6.6% year-over-year—faster than any economist predicted—defying concerns about front-loading effects from 2024’s rush to beat anticipated tariffs.

The composition of this growth tells the real story. While shipments to the United States plummeted—declining in nine consecutive months and dropping 30% in December alone, for a full-year decline of approximately 20%—Chinese exporters found eager customers elsewhere. According to customs spokesperson Lv Daliang, growth rates to emerging markets “all surpassed the overall rate,” revealing Beijing’s successful execution of what trade analysts call the most significant export diversification campaign by a major economy in modern history.
Africa led the charge with a stunning 26% increase in Chinese exports, followed by ASEAN nations at 13%, Latin America at 7%, and the European Union at 8%. These aren’t marginal markets absorbing overflow; they represent a structural reorientation. In absolute terms, China’s trade with ASEAN countries alone is projected to have exceeded $1.05 trillion in 2025, cementing the bloc’s position as Beijing’s largest trading partner—surpassing both the United States and European Union.
The product mix has also evolved. Higher-value exports—semiconductors, automobiles, and ships—all recorded gains exceeding 20%, while lower-end products like toys, shoes, and clothing contracted. Auto exports alone surged 21% to more than 7 million units, driven by electric vehicles and plug-in hybrids that are reshaping global automotive supply chains.
The Tariff Jolt and Beijing’s Long Game
The Trump administration’s tariff offensive, which escalated throughout 2025 with duties approaching 60% on some Chinese goods, was designed to bring Beijing to heel. Instead, it accelerated trends that Chinese policymakers had been cultivating since the first trade war began in 2018. The difference this time was both the scale of US measures and the sophistication of China’s response.
Beijing’s playbook drew heavily from its Dual Circulation strategy, articulated in 2020 but turbocharged after Trump’s 2024 election victory signaled renewed trade hostilities. As described by the World Economic Forum, this framework emphasized reducing vulnerability to Western pressure through trade diversification, industrial upgrading, and domestic resilience—precisely the pillars that bore fruit in 2025.
“The authorities have been preparing for this moment since at least 2017,” notes Markus Herrmann Chen, founder of China Macro Group. Trade with Belt and Road Initiative participating countries reached RMB 11.6 trillion ($1.6 trillion) by 2021, according to the Atlantic Council—far surpassing trade with the EU or United States. By 2025, this diversification had reached critical mass.
The policy infrastructure supporting this shift included export financing facilities, expedited customs clearance for emerging market destinations, upgraded free trade agreements (including the newly enhanced China-ASEAN FTA finalized in May 2025), and diplomatic campaigns that paired infrastructure investments with market access. Meanwhile, a weakening yuan—reflecting domestic deflationary pressures—made Chinese goods even more price-competitive globally, with export prices declining for their third consecutive year.
Diversification in Action: Three Theaters of Expansion
Southeast Asia: The Manufacturing Nexus
Vietnam, Indonesia, Thailand, and Malaysia have become the frontline states in China’s geographic pivot. Chinese exports to ASEAN grew 13% in 2025, but the relationship runs deeper than simple trade flows. As Rhodium Group documents, Chinese manufacturing FDI into ASEAN averaged $10 billion over the past three years—nearly four times the 2014-2017 average—with Indonesia and Vietnam together attracting 56% of investment value.
This isn’t merely about circumventing tariffs through “transshipment”—though that certainly occurs and has triggered US scrutiny. Chinese firms are establishing genuine production capacity, particularly in electric vehicles, solar panels, electronics, and steel. BYD’s multi-billion-dollar EV plants in Thailand, CATL’s battery facilities across the region, and countless component manufacturers represent a reconfiguration of supply chains that will outlast any tariff regime.
The integration is symbiotic but asymmetric. ASEAN countries rely heavily on Chinese intermediate inputs—averaging one-third of their imported materials, according to East Asia Forum—meaning Chinese value-added content in “ASEAN-made” exports remains substantial. Vietnam’s exports to the US surged 30% in 2025, powered by electronics and textiles, but many incorporate Chinese components assembled by Chinese-invested factories employing Chinese supply chain management.
Yet this dependence cuts both ways. As Asia Society research warns, the flood of finished Chinese goods—particularly EVs, solar panels, and consumer electronics—is displacing local production. Indonesia’s textile sector shed 80,000 jobs in 2024, with 280,000 more at risk in 2025. Thailand has seen Japanese automakers like Subaru, Suzuki, and Nissan close factories as Chinese EVs capture market share. The challenge for ASEAN is navigating between benefiting from Chinese investment and protecting nascent industries from predatory pricing.
Africa: The Consumption Frontier
China’s 26% export surge to Africa in 2025 marks a qualitative shift in the relationship. While infrastructure projects and resource extraction have long defined China-Africa ties, 2025 saw Beijing pivot decisively toward consumer markets. Chinese exports to the continent in the first three quarters rose 28% year-over-year to approximately $122 billion, according to Bloomberg analysis, driven by construction machinery, passenger cars, steel, electronics, and solar panels (which jumped 60%).
Nigeria led African imports, accounting for 11% of the total at approximately 4.66 trillion naira, followed by South Africa (10%), Egypt (9%), and others. The CNBC investigation of social media posts and business registrations reveals thousands of Chinese entrepreneurs establishing small businesses across African cities—selling electronics, bubble tea, furniture, press-on nails—targeting Africa’s emerging middle class of 350 million consumers.
This expansion comes as profit margins narrow at home amid deflation and intense competition. “Africa benefits from cheap consumer goods,” observes Capital Economics, “but risks undermining local manufacturing and deepening trade imbalances.” Indeed, Africa’s trade deficit with China ballooned to nearly $60 billion through August 2025, perpetuating colonial-era patterns: raw materials (oil, minerals, cobalt, copper) flow to China while manufactured goods flow back.
Kenya exemplifies both opportunity and vulnerability. Chinese construction machinery and solar panels support infrastructure development, while Chinese EVs offer affordable transport options. Yet as ISS Africa notes, much of Africa’s exports to China are controlled by Chinese-owned firms operating on the continent, with earnings flowing back to foreign investors rather than stimulating local value chains. Without aggressive local content requirements and industrial policy, the $200 billion projected for China-Africa trade in 2025 may reinforce dependency rather than catalyze development.
Latin America: The EV Battleground
Latin America absorbed approximately $276 billion in Chinese exports by November 2025—up nearly 8% despite the ongoing US-China trade conflict. Brazil emerged as China’s prize market, with exports soaring over 25% to reach $30 billion in the first five months alone, according to Americas Market Intelligence. The star attraction: electric vehicles.
Brazil imported approximately 130,000 Chinese EVs in just the first five months of 2025—a tenfold increase from 2024—making it China’s largest EV export market globally. BYD is investing heavily in Brazilian production facilities, planning to manufacture 10,000 units in 2025 and 20,000 by end-2026. American Century Investments reports similar dynamics in Mexico, where Chinese auto exports rose 36%, and Argentina, where imports of Chinese goods nearly doubled amid bilateral RMB payment agreements that eased dollar shortages.
Beyond autos, Chinese exports span industrial machinery, telecommunications equipment, steel, and construction materials supporting infrastructure development. Peru’s Chancay megaport, a Chinese-funded deep-water facility designed to service ultra-large container ships, symbolizes Beijing’s long-term regional ambitions—creating logistics infrastructure that will funnel South American commodities to Asia while providing entry points for Chinese manufactured goods.
Yet geopolitical tensions simmer beneath the commerce. Mexico faces intense US pressure to impose tariffs on Chinese goods and guard against “transshipment” of China-made products bound for American markets. In December 2025, Mexico approved a sweeping overhaul of import taxes affecting 1,463 tariff lines across 17 strategic sectors, targeting China and other nations. The Trump administration has explicitly warned Mexico that failure to curb Chinese imports could trigger US tariffs on Mexican exports—a pressure campaign that reveals Washington’s anxieties about losing influence in its own hemisphere.
Domestic Drivers: Deflation as Export Engine
The paradox of China’s export boom is that it reflects economic weakness as much as strength. Behind the record surplus lies a structural malady: anemic domestic consumption and persistent deflation that has forced Chinese manufacturers to seek markets abroad rather than building demand at home.
China’s consumer prices remained flat in 2025, missing the official 2% target, while the GDP deflator—a broad price gauge—declined for ten consecutive quarters through late 2025. Factory-gate prices have been in deflationary territory since October 2022. This isn’t a statistical quirk; it reflects weak household demand, a property sector that has contracted by half since its 2021 peak, and local government fiscal crises that constrain public spending.
“No economy has recorded 5% real GDP growth while facing years of persistent deflation,” argues Logan Wright of Rhodium Group in a December 2025 analysis. He estimates China’s actual 2025 growth fell short of 3%, far below the official 5% target, with domestic demand “anemic and confined to modest household consumption expansion.”
The International Monetary Fund’s December 2025 assessment is blunt: “The prolonged property sector adjustment, spillovers to local government finances, and subdued consumer confidence have led to weak domestic demand and deflationary pressures.” IMF Managing Director Kristalina Georgieva called for “more forceful and urgent” policies to transition to consumption-led growth, warning that “reliance on exports is less viable for sustaining robust growth” given China’s massive economic size and heightened global trade tensions.
The feedback loop is pernicious. Deflation encourages households to delay purchases and increase savings (China’s household savings rate remains among the world’s highest). Weak domestic demand forces manufacturers to cut prices, triggering brutal price wars—particularly in automotive, solar, and steel—that further erode profitability and investment. Unable to earn returns domestically, companies dump products abroad at marginal cost, creating the export surge that manifests as a trade surplus.
“The swelling surplus underscores the imbalance between China’s manufacturing strength and stubbornly weak domestic consumption,” observes Business Standard. It’s a symptom, not a sign of health—akin to Germany’s persistent surpluses during its “sick man of Europe” phase or Japan’s export dependence during lost decades of deflation.
Global Ripples: Winners, Losers, and Backlash
China’s export offensive creates ripple effects across the global economy, producing both opportunities and tensions that will shape trade policy for years.
Emerging market pressures: While developing nations benefit from affordable Chinese capital goods, consumer electronics, and infrastructure inputs, they face mounting risks. Local manufacturers struggle against subsidized competition. Capital Economics warns that “governments in Nigeria, South Africa, and Kenya may seek to defend respective industries,” but most commodity-dependent African nations “are likely to prioritize trade ties with China over industrialization ambitions.” The trade-off between cheap imports and industrial development presents a Faustian bargain.
Currency effects and financial flows: China’s deflationary pressures have driven real exchange rate depreciation, making exports even more competitive. The current account surplus reached 3.7% of GDP in Q1 2025, but this was offset by significant capital outflows as Chinese investors sought returns abroad and hedged against domestic uncertainties. The World Bank’s December 2025 update notes that “larger net capital outflows outweighed the current account surplus,” reflecting private-sector concerns about China’s economic trajectory.
Protectionist backlash: The flood of Chinese goods is triggering defensive measures globally. The European Union faces growing political pressure to counter what officials describe as unfair competition from state-subsidized Chinese manufacturers, particularly in EVs, solar panels, and steel. Preliminary EU tariffs on Chinese EVs reached as high as 45%, while solar panel duties from Southeast Asian countries (themselves hosting Chinese production) range from 21% to 271%. Brazil, Turkey, and India have imposed automotive tariffs. Even Russia—China’s largest auto export market in 2023-2024—recently enacted non-tariff barriers to protect domestic production.
US strategic concerns: Washington’s anxieties extend beyond economics. The Trump administration’s “transshipment” provisions, which threaten 40% tariffs on goods deemed to have been illegally rerouted through third countries, aim squarely at Chinese supply chain strategies in ASEAN and Mexico. S&P Global analysis warns that strict rules-of-origin enforcement could “adversely affect export competitiveness” of Malaysia, Singapore, Thailand, and Vietnam—countries with low domestic value content but high Chinese integration.
The geopolitical subtext is unmistakable. As Americas Quarterly notes, China’s infrastructure investments and manufacturing presence in Latin America represent “a direct challenge to US dominance in the region.” Chinese space facilities in Argentina, ports in Peru, and 5G networks across the hemisphere trigger national security debates in Washington, revealing that trade battles mask deeper great-power competition.
What Comes Next: Risks and Rebalancing
The sustainability of China’s export-driven model faces mounting challenges that will test Beijing’s economic management in 2026 and beyond.
Overcapacity and market saturation: China’s manufacturers expanded production capacity dramatically during the pandemic, anticipating continued growth. As domestic demand faltered, this capacity became stranded, forcing companies to export at unsustainably low prices. The risk, as Rhodium Group observes, is that “overcapacity flooding” will provoke coordinated international responses—tariffs, anti-dumping duties, investment restrictions—that close off markets faster than Beijing can diversify.
Lynn Song, chief economist for Greater China at ING Groep, warns China faces “some pushback” as its higher-end products become globally competitive. The more successfully Chinese firms move up the value chain—competing in EVs, semiconductors, renewable energy—the more likely they are to trigger defensive industrial policies from advanced economies protecting strategic sectors.
Geopolitical fragmentation: The rules-based trading system that facilitated China’s rise is fracturing. As emerging markets become battlegrounds between Chinese commercial interests and Western political pressure, countries face increasingly binary choices. The US is weaponizing market access, conditioning trade relationships on partners’ willingness to limit Chinese participation. Mexico’s tariff reforms exemplify this squeeze—economic logic suggests embracing Chinese investment, but geopolitical realities demand demonstrating alignment with Washington.
Domestic rebalancing imperatives: Every major international institution—the IMF, World Bank, OECD—agrees that China must transition to consumption-driven growth. Yet 2025 demonstrated how difficult this transformation is. Retail sales growth barely exceeded 1% by year-end, despite trade-in subsidies and consumption vouchers. The property crisis shows no signs of resolution, local government debt problems worsen, and deflationary psychology becomes more entrenched with each passing quarter.
The IMF’s December 2025 assessment projects China’s growth will moderate to 4.5% in 2026 (down from 5% in 2025) as “it would take time for domestic sources of growth to kick in.” Sonali Jain-Chandra, the IMF’s China Mission Chief, argues that “macro policies need to focus forcefully on boosting domestic demand” to “reflate the economy, lift inflation, and lead to real exchange rate appreciation”—precisely the medicine Beijing has been reluctant to administer.
The 2026 outlook: Natixis economist Gary Ng forecasts Chinese exports will grow about 3% in 2026, down from 5.5% in 2025, but with slow import growth, he expects the trade surplus to remain above $1 trillion. This would represent a third consecutive year of record surpluses—unprecedented for an economy of China’s scale and development level.
The comparison to historical precedents is instructive. Germany ran persistent current account surpluses approaching 8% of GDP in the 2010s, triggering criticism but ultimately reflecting structural savings-investment imbalances. Japan’s export dominance in the 1980s provoked “voluntary” export restraints and contributed to asset bubbles when yen appreciation finally arrived. China’s $1.2 trillion surplus in 2025 represented roughly 6-7% of GDP—a figure that would be unsustainable indefinitely without either forced adjustment through currency appreciation or external pressure through coordinated tariffs.
Conclusion: A Pyrrhic Victory?
China’s record $1.2 trillion trade surplus in 2025 demonstrates the resilience and adaptability of the world’s manufacturing superpower. Against expectations, Chinese exporters not only survived the Trump administration’s tariff assault but thrived, finding eager customers from Lagos to Jakarta to São Paulo. The successful execution of trade diversification—years in planning, accelerated by necessity—has reduced China’s vulnerability to any single market and cemented commercial relationships across the Global South.
Yet this triumph carries hidden costs and uncertain longevity. The surplus reflects not vibrant economic health but the malaise of a economy unable to generate sufficient domestic demand to absorb its own productive capacity. Deflation, property crisis, and weak consumer confidence reveal structural imbalances that export growth merely postpones addressing rather than resolving. Every major international economic institution warns that export-led growth is reaching its natural limits for an economy of China’s scale.
Geopolitically, China’s export offensive is hardening Western resolve to reduce dependencies and rebuild domestic industrial capacity—the very “decoupling” Beijing sought to avoid. The more successful Chinese manufacturers become at penetrating global markets, the more protectionist the response grows. We are witnessing not the end of US-China trade conflict but its globalization, as secondary markets become contested terrain and supply chains fragment along geopolitical lines.
For global policymakers, 2025’s trade data poses a fundamental question: Can the international economy accommodate a manufacturing superpower running trillion-dollar surpluses year after year? History suggests not without significant adjustment—through currency appreciation, domestic rebalancing, or external pressure. The lesson of 2025 is that Chinese firms are extraordinarily capable of adapting to barriers and finding new markets. The lesson of 2026 may be that even the most successful export diversification cannot indefinitely substitute for robust domestic demand.
As containers continue loading at Shenzhen’s ports, bound for an ever-widening array of destinations, the numbers tell a story of tactical success masking strategic vulnerability. China has won the battle against Trump’s tariffs. The war for sustainable economic growth, however, requires victories on the home front that remain frustratingly elusive.


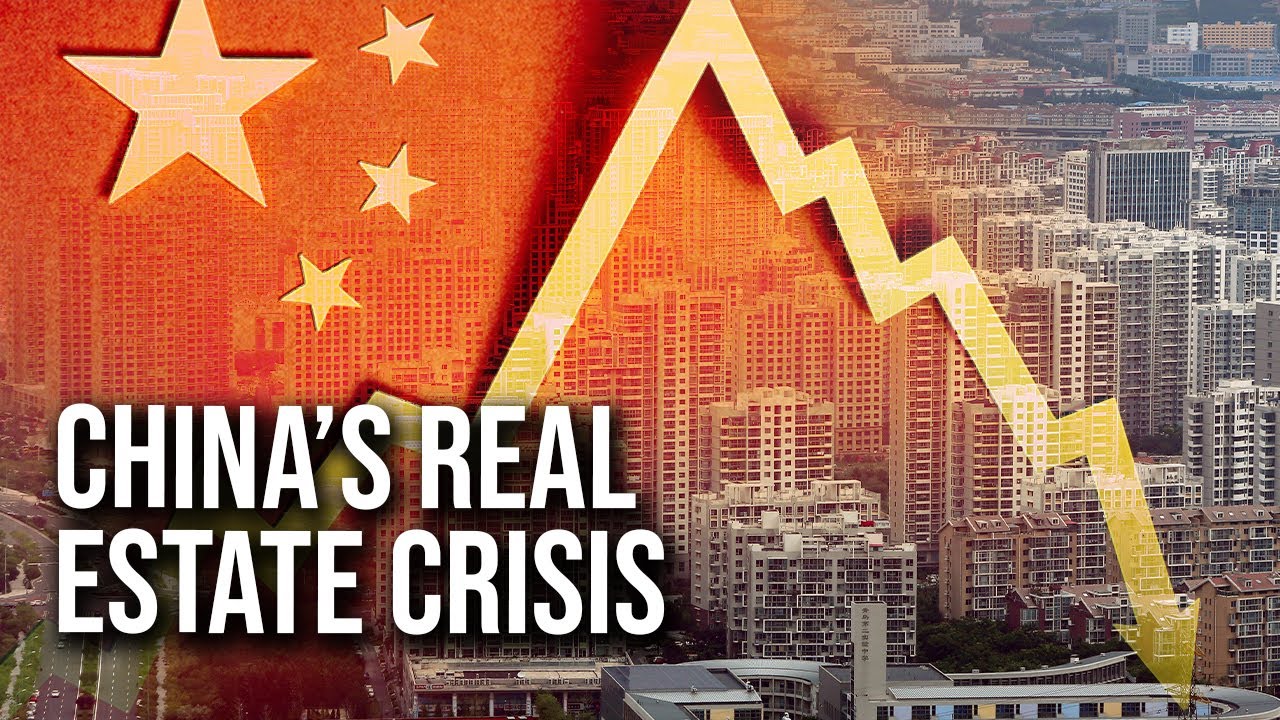
China’s economy in 2026 is a study in contradiction. In its largest cities — Shanghai, Beijing, Guangzhou, Shenzhen — new-home prices have risen for three consecutive months, driven by targeted policy support that is beginning to show traction. Across the remaining hundreds of cities, prices are still falling at a pace that is accelerating, not slowing.
National property investment fell 16.2% year-over-year in the first five months of 2026 — a staggering contraction in a sector that once accounted for roughly a quarter of Chinese GDP. At the same time, China’s technology sector is attracting record capital flows, its export machine is running at full throttle despite global trade tensions, and the People’s Bank of China (PBOC) is quietly implementing some of the most significant monetary architecture reforms in a generation.
China is, in effect, running two economies simultaneously. Understanding which one dominates the other will determine the trajectory of global markets for the next several years.
The Property Sector: A Structural Wound, Not a Cyclical Dip
China’s real estate crisis is entering its fifth year. What began with the 2021 Evergrande collapse has evolved into a sustained structural contraction that is fundamentally reshaping the economic role of property in China’s growth model.
National home prices declined at a faster pace in May 2026 than in April, a sign that market conditions are deteriorating rather than stabilising at the aggregate level. The OECD inventory of unsold homes across China’s lower-tier cities remains enormous — a structural supply overhang that cannot be resolved by demand-side stimulus alone.
The policy response has been asymmetric by design. The central government’s support measures are concentrated in Tier 1 and select Tier 2 cities, where local governments have more fiscal capacity to implement purchase subsidies, down-payment reductions, and mortgage rate cuts. In these markets, the policy appears to be working: new-home prices in China’s first-tier cities rose for the third consecutive month in May.
But first-tier cities account for a small fraction of China’s total housing stock. The vast majority of property — and the vast majority of household wealth — is concentrated in smaller cities where policy support is less effective and price declines are continuing.
The macro consequence is a negative wealth effect that is suppressing consumer confidence and retail spending precisely at the moment China needs domestic demand to compensate for a structurally lower export environment.
The PBOC’s Quiet Revolution
While the property sector weighs on growth, the People’s Bank of China has been implementing a series of significant monetary policy reforms. PBOC Governor Pan Gongsheng announced measures in June 2026 that include:
- Increased use of overnight reverse repo operations, a technical adjustment that improves the PBOC’s ability to manage short-term liquidity conditions with precision
- Narrowing the short-term interest rate corridor, reducing volatility in interbank lending rates and improving monetary policy transmission
- Steps to support the offshore use of the renminbi, accelerating the internationalisation of the Chinese currency as part of China’s longer-term strategy to reduce dependency on the US dollar in global trade and finance
These announcements are significant, but should not be misread as a broad-based monetary stimulus package. The PBOC is reforming its operational framework and improving financial market infrastructure — not firing an economic bazooka. The distinction matters for investors who might expect a China stimulus surge analogous to 2009 or 2015.
For investors, the PBOC’s focus on financial market development and liquidity management signals that policymakers are prioritising long-term stability over short-term growth stimulus. This implies a more gradual recovery trajectory than markets have sometimes assumed.
China’s Export Machine: A Source of Strength and Tension
Against the backdrop of the property slump, China’s export sector is performing exceptionally well. China’s trade surplus has expanded significantly in 2026, driven by:
- Industrial overcapacity in sectors including steel, solar panels, electric vehicles, chemicals, and lithium-ion batteries
- A weaker renminbi that has improved price competitiveness for Chinese exporters in global markets
- Continued strong demand for Chinese manufactured goods from Southeast Asia, Latin America, and Africa — markets that have deepened trade ties with China as US-China trade friction has redirected some Western procurement
China’s strong export growth has sparked significant international pushback. Policymakers across the European Union, the United States, and major emerging markets have expressed concerns about industrial overcapacity and the impact of low-cost Chinese exports on domestic manufacturing industries. The EU has implemented additional tariffs on Chinese electric vehicles, and US tariffs on a broad range of Chinese goods remain elevated following the Trump administration’s tariff regime.
The structural tension: China needs export growth to compensate for weak domestic demand, but its export success is generating the geopolitical friction that could ultimately constrain market access.
China’s AI Pivot: From Property Developer to Tech Powerhouse
The most significant transformation in China’s economic structure in 2026 is not occurring in housing — it is occurring in technology. China’s leadership has made a deliberate and well-resourced pivot toward artificial intelligence, semiconductors, and advanced manufacturing as the new engines of economic growth.
Chinese technology companies including Huawei, Baidu, Alibaba, and ByteDance are investing at scale in AI model development, AI chip design, and AI-integrated enterprise applications. The Chinese government’s industrial policy support for these sectors — through subsidies, preferential financing, and regulatory facilitation — is mobilising capital at a pace that rivals the hyperscaler buildout in the United States.
The strategic motivation is clear: reduce dependency on US semiconductor technology (particularly following US export controls on advanced chips), build sovereign AI capability across defence, governance, and commercial applications, and position Chinese technology companies as global AI leaders in markets outside the Western sphere.
This pivot is creating investment opportunities in Chinese technology equities — though geopolitical risk, regulatory uncertainty, and the US export control regime create complex risk factors that must be weighed carefully by international investors.
The Global Market Implications
China’s two-speed economy creates distinct implications for different asset classes and geographic markets:
Commodities: The property sector contraction is the dominant factor for commodity demand. Steel, copper, cement, and glass — all deeply tied to construction activity — face sustained headwinds from Chinese property weakness. Iron ore prices reflect this dynamic. In contrast, Chinese demand for technology-related commodities (lithium, cobalt, rare earths) remains robust as the EV and battery supply chain continues to scale.
Asian equities: The MSCI Emerging Markets index has significant China weighting, and China’s two-speed dynamics are creating divergence between technology-oriented Chinese equities (performing well) and property/financial sector stocks (underperforming). Country selection and sector allocation matter enormously in the current Chinese equity environment.
Currency markets: The PBOC’s renminbi internationalisation measures represent a long-duration effort to reduce dollar dependence. In the near term, currency management remains a key PBOC tool — managed depreciation to support exporters, with intervention to prevent disorderly moves that could trigger capital outflows.
European and US corporates: Companies with significant China exposure face a bifurcated operating environment — strong demand in technology-related end markets, weak demand in consumer and construction-related segments. Luxury goods, industrials, and materials companies are disproportionately affected by the property sector contraction.
The Policy Outlook: What Comes Next
The Chinese government faces a genuinely difficult policy dilemma. Aggressive fiscal or monetary stimulus risks reigniting the debt dynamics that made the property crisis inevitable in the first place. Insufficient support risks a deeper consumer confidence collapse that could turn a structural slowdown into a sharper cyclical downturn.
The current policy approach — targeted support for Tier 1 property markets, incremental PBOC reforms, and aggressive industrial policy investment in technology sectors — represents a careful balancing act. It is not the big bang stimulus that some investors have anticipated, but it is also not the hands-off approach that would allow a disorderly collapse.
The most likely trajectory: China grows at 4.0%–4.5% in 2026, below its historical average but ahead of the IMF’s revised global growth forecast of 3.1%. The property sector continues to weigh on domestic demand, while exports and technology investment provide partial offsets. The renminbi remains managed, and the PBOC avoids large-scale interest rate cuts that would widen the US-China rate differential and accelerate capital outflows.
The Bottom Line
China’s economy in 2026 is not in crisis, but it is in transition — and the transition is proving slower and more painful than the optimists predicted. The property sector wound is structural, not cyclical. The technology pivot is real but will take years to fully offset the economic weight that property once carried.
For global investors, China remains the world’s second-largest economy and a critical driver of commodity, trade, and technology markets. Ignoring it is not an option. But the analytical frameworks from the 2010s — property-led, infrastructure-driven, credit-fuelled growth — are no longer the right lens through which to assess Chinese economic dynamics in 2026.
The new China story is being written in data centres, EV factories, and AI labs — not in unfinished apartment towers.
FAQs
Q: What is happening with China’s economy in 2026?
A: China is running a two-speed economy. The property sector is contracting sharply — investment fell 16.2% year-over-year in early 2026 — while technology investment, AI spending, and exports are growing. The PBOC is implementing monetary reforms without large-scale stimulus.
Q: Is China’s property market recovering in 2026?
A: Partially and unevenly. New home prices in Tier 1 cities rose for three consecutive months through May 2026, suggesting policy support is gaining traction in the largest markets. Nationally, however, prices declined at a faster pace in May than April, and the recovery remains uneven across regions.
Q: What is China’s GDP growth forecast for 2026?
A: Most forecasters project China’s GDP growth at approximately 4.0%–4.5% in 2026 — below historical averages but above the IMF’s global average of 3.1%. The property sector contraction is the primary drag, partially offset by technology investment and export growth.
Q: How is China’s AI investment affecting global markets?
A: China’s AI and technology pivot is creating strong demand for technology-related commodities (lithium, rare earths), boosting Chinese technology equities, and intensifying competition with US and European AI companies — particularly in markets outside the Western sphere.
When silver prices cratered by a historic 27% on January 30, 2026—wiping out $150 billion in market value within hours—most traders scrambled to stanch the bleeding. Yet one firm turned catastrophe into windfall. Zhongcai Futures, the proprietary trading house controlled by reclusive Chinese entrepreneur Bian Ximing, banked over $500 million by betting against the very rally that entranced global speculators, according to reports from the Financial Times and market observers.
The profit haul marks another stunning victory for the 61-year-old plastics magnate turned commodities oracle, whose contrarian instincts have repeatedly outmaneuvered Wall Street’s conventional wisdom. After pocketing $1.5 billion from prescient gold futures trades between 2022 and 2024, Bian’s Shanghai-based brokerage executed short positions on silver just as the white metal approached its dizzying peak above $121 per ounce in late January—a record that would prove ephemeral.
The Silver Supercycle That Wasn’t
Silver’s ascent in late 2025 and early 2026 resembled nothing witnessed since the Hunt Brothers’ infamous squeeze four decades prior. Fueled by a confluence of factors—Chinese retail speculation, artificial intelligence’s voracious appetite for the metal’s thermal properties, and mounting concerns over currency debasement—prices rocketed from approximately $32 per ounce in early 2025 to an intraday high near $121 by late January 2026, representing a staggering 276% surge.
The narrative captivating markets was compelling: silver’s unrivaled electrical and thermal conductivity had become indispensable for next-generation AI chip manufacturing. Data center construction exploded as Large Language Models demanded increasingly sophisticated cooling systems, with silver-sintered thermal pastes emerging as the industry standard. Industrial demand appeared insatiable.
Yet beneath the euphoria lurked structural fragilities. As Bloomberg chronicled, speculative fever gripped Shanghai trading floors, where individual investors and equity funds venturing into commodities drove prices divorced from supply-demand fundamentals. Trend-following commodity trading advisers amplified the momentum, creating what analysts later termed a “speculative bubble” rather than a durable industrial squeeze.
By mid-January, the iShares Silver Trust (SLV) recorded unprecedented call option volumes exceeding those of the Nasdaq 100 ETF—a harbinger of the volatility to come. When silver futures surged past $110 per ounce, the CME Group implemented emergency measures, transitioning to percentage-based margin requirements that hiked maintenance margins to 15% for standard positions. The Shanghai Futures Exchange followed suit with multiple rounds of restrictions throughout January.
These administrative interventions would prove decisive. As reported across financial media, the margin hikes forced leveraged speculators who had controlled 5,000-ounce contracts with minimal collateral into a “margin trap,” triggering cascading liquidations that accelerated the selloff.
Zhongcai’s Contrarian Gambit
While retail investors queued for hours outside European bullion dealers and Chinese traders posted thousand-percent gains on social media, Bian Ximing’s team pursued a different calculus. Operating from Gibraltar—where Bian conducts business largely via video calls, maintaining his characteristic distance from Shanghai’s trading floors—Zhongcai Futures established short positions on the Shanghai Futures Exchange as silver approached its zenith.
The timing proved exquisite. On January 30, silver commenced its historic plunge around 10:30 AM Eastern Time, declining to $119 before President Trump’s announcement of Kevin Warsh as Federal Reserve chair nominee at 1:45 PM—a development widely cited as the crash catalyst, though the selloff had already eliminated 27% of silver’s value by that point. By session’s end, spot silver settled near $84 per ounce, representing a $37 per ounce drop in under 20 hours.
The mechanics behind Zhongcai’s profits illuminate Bian’s investment philosophy. Rather than chasing parabolic moves, he focuses on identifying structural imbalances and positioning for mean reversion. His sporadic blog posts—parsed religiously by Chinese traders seeking to emulate his hedge fund-style approach—emphasize “letting go of ego,” choosing targets based on trends, and maintaining discipline on costs. “Investment is essentially a game of survival capability,” Bian wrote in a January reflection, weeks before silver’s collapse.
Market observers note that Zhongcai’s short positions likely concentrated on Shanghai contracts rather than COMEX, providing natural hedges as Chinese markets remained closed during Lunar New Year holidays that shielded domestic traders from the worst intraday volatility when global prices briefly tumbled. The firm’s $500 million gain reflects not merely directional conviction but sophisticated execution across timing, venue selection, and risk management.
Anatomy of the Rout: Why Silver Crashed
The January 30 selloff represented multiple failures converging simultaneously. First, the paper silver market—ETFs and futures trading many multiples of physical metal volume—had disconnected dangerously from underlying supply. The 28% single-day drop in SLV, its worst session since inception, exposed how financialized commodity instruments can gap violently when speculation reaches fever pitch.
Second, exchange-mandated margin increases forced deleveraging precisely when positions were most extended. With silver at $120, a standard 5,000-ounce contract carried $600,000 in notional exposure; CME’s 15% maintenance requirement meant traders suddenly needed $90,000 versus previous minimums around $25,000. Those unable to meet calls faced automatic liquidation, creating self-reinforcing downward pressure.
Third, high-frequency trading dynamics amplified the cascade. Chinese authorities’ early-2026 moves to remove servers from exchange data centers and halt subscriptions in certain commodity fund products—including the UBS SDIC Silver Futures Fund—mechanically reduced marginal demand just as volatility peaked. When algorithms detected price deterioration, automated selling intensified the rout.
Current silver prices hovering around $90 per ounce as of February 4, 2026, reflect partial recovery from the lows but remain dramatically below late January peaks. The metal has stabilized approximately 176% above year-ago levels, though technical analysts identify the $75-$80 range as critical support—the consolidation zone before silver’s final parabolic surge.
Bian Ximing: The Invisible King of Futures
Born in 1963 in Zhuji, Zhejiang Province, during China’s tumultuous Cultural Revolution, Bian Ximing’s trajectory from vocational school graduate to billionaire commodities trader embodies calculated risk-taking married to macroeconomic foresight. After founding a high-end plastic tubes factory in 1995, he diversified into real estate, finance, and media, acquiring the brokerage that became Zhongcai Futures in 2003.
His reputation crystallized through his 2022-2024 gold play. Anticipating global efforts to reduce dollar reliance amid inflation fears, Bian established long positions at gold’s mid-2022 lows and scaled holdings through 2023, ultimately exiting near bullion’s 2024 peaks with an estimated $1.5 billion profit. The success earned him comparisons to Warren Buffett for his patient, fundamentals-driven approach—a rarity among China’s more speculative trading culture.
Yet Bian’s latest copper bet demonstrates his agility. As of May 2025 reports, Zhongcai held the largest net long copper position on the Shanghai Futures Exchange—nearly 90,000 tons worth approximately $1 billion—wagering on the metal’s centrality to electrification and China’s high-tech industrial transition. That position has generated roughly $200 million in profits to date, per Bloomberg calculations.
The silver short, however, marks a tactical pivot. While maintaining copper longs, Zhongcai recognized silver’s speculative excess and positioned accordingly—illustrating Bian’s capacity to hold seemingly contradictory views on related assets when fundamentals diverge. His lieutenants occasionally post “reflections” on the company site, offering glimpses into a trading operation that blends Western institutional discipline with shrewd navigation of China’s distinct market structure.
Market Implications: What Comes Next for Precious Metals
The silver crash holds sobering lessons for commodity markets increasingly dominated by momentum strategies and retail speculation. First, even genuine industrial demand stories—silver’s role in AI infrastructure is legitimate—can be overwhelmed by speculative excess. When paper markets far exceed physical volumes, financialization creates vulnerabilities to sharp corrections.
Second, regulatory interventions matter. Exchange margin adjustments, while prudent for systemic stability, can trigger violent moves when implemented amid extended positioning. Traders operating with maximum leverage learned painfully that exchanges prioritize clearinghouse solvency over individual P&L.
Third, the episode underscores China’s growing influence on global commodity prices. Chinese retail and institutional flows drove silver’s rally and contributed to its collapse, with domestic regulatory actions—HFT crackdowns, fund redemption halts—rippling across international markets. As geopolitical tensions persist, understanding China’s market structure becomes essential for commodity investors worldwide.
Looking ahead, analysts divide on silver’s trajectory. Citigroup analysts maintain $150 targets, citing structural supply deficits and AI-driven demand as justifying a new $65-$70 floor even after the correction. Bears counter that January’s crash revealed demand isn’t as inelastic as bulls assumed; at $100-plus per ounce, industrial substitution and demand destruction become economic imperatives.
Gold faces similar crosscurrents, having plunged 12% on January 30 to below $5,000 per ounce after touching $5,602 earlier that week. While central bank purchases and geopolitical risk support longer-term bullion strength, the correction demonstrates that even traditional safe havens aren’t immune to sentiment reversals when positioning grows extreme.
For copper, Bian’s continued conviction through recent trade-war volatility signals confidence in China’s economic resilience and secular electrification trends. Major players like Mercuria forecast $12,000-$13,000 per ton, well above current $9,500 levels, if supply constraints and infrastructure demand materialize as expected.
The Broader Lessons
Zhongcai’s silver windfall exemplifies timeless trading principles that transcend specific asset classes. Bian Ximing’s success stems from identifying crowded trades, maintaining discipline when markets grow euphoric, and executing with precision when others capitulate. His ability to profit from both gold’s rise (2022-2024) and silver’s fall (January 2026) reflects not market timing alone but understanding market structure, sentiment extremes, and the mechanics of leveraged speculation.
For institutional investors, the episode reinforces why derivatives exposure requires rigorous risk management. The 99% long liquidation rate during silver’s crash—$70.52 million wiped out in four hours according to data compiled by ChainCatcher News and HyperInsight—illustrates how one-directional positioning leaves little room for error when volatility strikes.
Retail traders, meanwhile, confront uncomfortable truths about information asymmetries. While Zhongcai operated with deep liquidity and sophisticated infrastructure, individual investors often lacked real-time data on margin adjustments and exchange positioning. The “invisible king of futures” capitalizes partly on seeing what others miss—or seeing it faster.
As markets digest January’s tumult, silver’s recovery to $90 per ounce suggests the correction hasn’t destroyed all investor appetite. Physical demand remains robust; Shanghai Gold Exchange premiums over London quotes exceeded $13 per ounce in early February, incentivizing new bullion imports. Mining supply constraints persist, with Fresnillo cutting 2026 guidance and Hecla projecting output below 2025 levels.
Yet the psychological scars will linger. January 2026 joins 1980’s Hunt Brothers collapse and 2011’s post-financial crisis peak as cautionary tales of silver’s volatility. Those betting on precious metals’ inflation-hedge properties must now contend with the reality that speculative fervor can override fundamentals for extended periods—in both directions.
Conclusion: Discipline Triumphs Over Euphoria
In an era when retail traders armed with Reddit forums and leveraged derivatives amplify market moves, Zhongcai’s $500 million silver profit stands as a reminder that disciplined capital allocation still matters. Bian Ximing’s reluctance to chase parabolic rallies, his focus on structural imbalances rather than momentum, and his willingness to position contrarily when consensus grows overwhelming—these attributes explain why his track record sparkles while so many speculators suffer.
As silver stabilizes and investors reassess precious metals allocations, the January crash offers a masterclass in market dynamics. Leverage cuts both ways. Exchange rules trump individual conviction. And occasionally, the trader watching from Gibraltar sees more clearly than the crowd queuing outside Budapest bullion shops.
For those navigating commodity markets in 2026 and beyond, Zhongcai’s success suggests a path forward: respect fundamentals, fear euphoria, and remember that in investing as in life, survival matters more than spectacular gains. The invisible king of futures has spoken—not through interviews or appearances, but through profits earned when others panicked or grew reckless. In that sense, Bian Ximing’s greatest lesson may be the one he’s lived rather than written: that true edge comes not from outsmarting the market, but from outlasting it.
Asia
BYD’s Ambitious 24% Export Growth Target for 2026: Can New Models and Global Showrooms Defy a Slowing China EV Market?
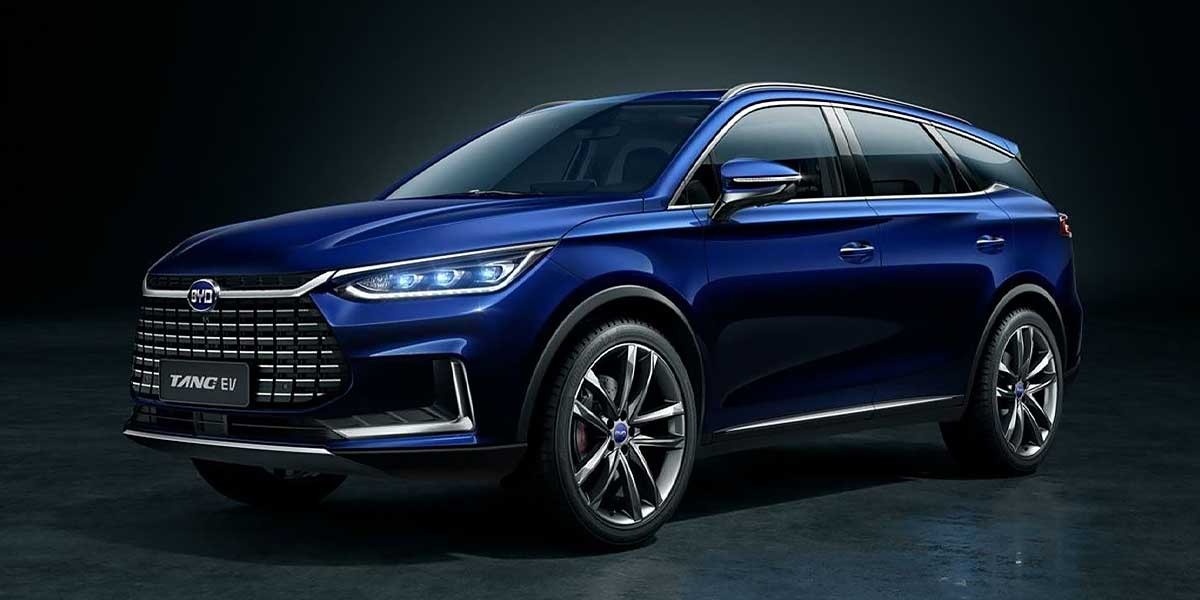
BYD’s auditorium at Shenzhen headquarters that crystallizes the strategic pivot of the world’s largest electric vehicle maker: 1.3 million. This is BYD’s target for overseas sales in 2026, a 24.3% jump from the previous year, as announced by branding chief Li Yunfei in a January media briefing. This figure is more than a goal; it is a declaration. With China’s domestic EV market showing unmistakable signs of saturation and ferocious price wars eroding margins, BYD’s relentless growth engine now depends on its ability to replicate its monumental domestic success on foreign shores. The question echoing through global automotive boardrooms is whether its expanded lineup—including the premium Denza brand—and a rapidly unfurling network of international showrooms can overcome rising geopolitical headwinds and entrenched competition.
The Meteoric Ascent: How BYD Built a Colossus
To understand the magnitude of the 2026 export target, one must first appreciate the velocity of BYD’s ascent. The company, which began as a battery manufacturer, has executed one of the most stunning industrial transformations of the 21st century. In 2025, BYD sold approximately 4.6 million New Energy Vehicles (NEVs), cementing its position as the undisputed volume leader. Crucially, within that figure lay a milestone that shifted the global order: ~2.26 million Battery Electric Vehicles (BEVs), officially surpassing Tesla’s global deliveries and seizing the BEV crown Reuters.
The foundation of this dominance is vertical integration. BYD controls its own battery supply (the acclaimed Blade Battery), semiconductors, and even mines key raw materials. This mastery over the supply chain provided a critical buffer during global disruptions and allows for aggressive cost control. However, the domestic market that fueled this rise is changing. After years of hyper-growth, supported by generous government subsidies, China’s EV adoption curve is maturing. The result is an intensely competitive landscape where over 100 brands are locked in a profit-eroding price war Bloomberg.
BYD’s 2026 Export Blueprint: From 1.05 Million to 1.3 Million
BYD’s overseas strategy is not a tentative experiment but a full-scale offensive, backed by precise tactical moves. The 2025 export base of approximately 1.04-1.05 million vehicles—representing a staggering 145-200% year-on-year surge—provides a formidable launchpad. The 2026 plan, aiming for 1.3 million units, is built on two articulated pillars: product diversification and network densification.
1. New Models and the Premium Denza Push: Li Yunfei explicitly stated the launch of “more new models in some lucrative markets,” which will include Denza-branded vehicles. Denza, BYD’s joint venture with Mercedes-Benz, represents its attack on the premium segment. Launching models like the Denza N9 SUV in Europe and other high-margin markets is a direct challenge to German OEMs and Tesla’s Model X. This move upmarket is essential for improving brand perception and profitability beyond the volume-oriented Seal and Atto 3 (known as Yuan Plus in China) Financial Times.
2. Dealer Network Expansion: The brute-force expansion of physical presence is key. BYD is moving beyond reliance on importers to establishing dedicated dealerships and partnerships with large, reputable auto retail groups in key regions. This provides localized customer service, builds brand trust, and significantly increases touchpoints for consumers. In 2025 alone, BYD expanded its European dealer network by over 40% CNBC.
The Domestic Imperative: Why Overseas Growth is Non-Negotiable
BYD’s export push is as much about necessity as ambition. The Chinese market, while still the world’s largest, is entering a new phase.
- Market Saturation in Major Cities: First-tier cities are approaching saturation points for NEV penetration, pushing growth into lower-tier cities and rural areas where consumer appetite and charging infrastructure are less developed.
- The Relentless Price War: With legacy automakers like Volkswagen and GM fighting for share and nimble startups like Nio and Xpeng launching competitive models, discounting has become endemic. This pressures margins for all players, even the cost-leading BYD The Wall Street Journal.
- Plateauing Growth Rates: After years of doubling, NEV sales growth in China is expected to slow to the 20-30% range in 2026, a dramatic deceleration from the breakneck pace of the early 2020s.
Consequently, overseas markets—with their higher average selling prices and less crowded competition—represent the most viable path for maintaining BYD’s growth trajectory and satisfying investor expectations.
The Global Chessboard: BYD vs. Tesla and the Chinese Cohort
BYD’s international expansion does not occur in a vacuum. It faces a multi-front competitive battle.
vs. Tesla: The rivalry is now global. While BYD surpassed Tesla in BEV volumes in 2025, Tesla retains significant advantages in brand cachet, software (FSD), and supercharging network density in critical markets like North America and Europe. Tesla’s response, including its own cheaper next-generation model, will test BYD’s value proposition abroad The Economist.
vs. Chinese Export Rivals: BYD is not the only Chinese automaker looking overseas. A look at 2025 export volumes reveals a cohort in hot pursuit:
- SAIC Motor (MG): The historic leader in Chinese EV exports, leveraging the MG brand’s European heritage.
- Chery: Aggressive in Russia, Latin America, and emerging markets.
- Geely (Zeekr, Polestar, Volvo): A sophisticated multi-brand approach targeting premium segments globally.
While BYD currently leads in total NEV exports, its rivals are carving out strong regional niches, making global growth a contested space Reuters.
Geopolitical Speed Bumps and Localization as the Antidote
The single greatest risk to BYD’s 2026 export target is not competition, but politics. Tariffs have become the primary tool for Western governments seeking to shield their auto industries.
- European Union: Provisional tariffs on Chinese EVs, varying by manufacturer based on cooperation with the EU’s investigation, add significant cost. BYD’s rate, while lower than some rivals, still impacts pricing.
- United States: The 100% tariff on Chinese EVs effectively locks BYD out of the world’s second-largest car market for the foreseeable future.
BYD’s counter-strategy is localization. By building vehicles where they are sold, it can circumvent tariffs, create local jobs, and soften its political image. Its global factory footprint is expanding rapidly:
- Thailand: A new plant operational in 2024, making it a hub for ASEAN right-hand-drive markets.
- Hungary: A strategically chosen factory within the EU, set to come online in 2025-2026, to supply the European market tariff-free.
- Brazil: A major complex announced, targeting Latin America and leveraging regional trade agreements.
This “build locally” strategy requires massive capital expenditure but is essential for sustainable long-term growth in protected markets Bloomberg.
Risks and the Road Ahead: Brand, Quality, and Culture
Beyond tariffs, BYD faces subtler challenges. Brand perception in mature markets remains a work in progress; shifting from being seen as a “cheap Chinese import” to a trusted, desirable marque takes time and consistent quality. While its cars score well on initial quality surveys, long-term reliability and durability data in diverse climates is still being accumulated.
Furthermore, managing a truly global workforce, supply chain, and product portfolio tailored to regional tastes (e.g., European preferences for stiffer suspension and different infotainment systems) is a complex operational leap from being a predominantly domestic champion.
Conclusion: A Calculated Gamble on a Global Stage
BYD’s 24% export growth target for 2026 is ambitious yet calculated. It is underpinned by a formidable cost structure, a rapidly diversifying product portfolio, and a pragmatic shift to local production. The slowing domestic market leaves it little choice but to pursue this path aggressively.
The coming year will be a critical test of whether its engineering prowess and operational efficiency can translate into brand strength and customer loyalty across cultures. Success is not guaranteed—geopolitical friction is increasing, and competitors are not standing still. However, BYD has repeatedly defied expectations. Its 2026 export campaign is more than a sales target; it is the next chapter in the most consequential story in the global automotive industry this decade—the determined rise of Chinese automakers from domestic leaders to dominant global players. The world’s roads are about to become the proving ground.

Diesel Prices 2026–2027: Why Cheaper Crude May Not Mean Cheap Fuel

2027 Social Security COLA: Key Details and Dates

KSE-100 Sees Major Drop Post-SBP Rate Hike

Big Tech’s AI Spending Test: Can Revenue Catch Up With Capital Expenditure?

AI Infrastructure Investment Strategies for 2026

Pakistan Freelancers Tax 2026: Payments, Documentation and Formal Growth

Strait of Hormuz Crisis: What the Latest Tanker Attacks Mean for Oil, Shipping and Global Trade

AI Customer Service in 2026: What’s Working, What’s Failing, and What to Buy

Open a Savings Account Online: How to Actually Earn 10x the National Average Rate

Global Housing Market 2026: Where Prices Rise, Where They Don’t

PSX and KSE-100 Record Highs: An Insider’s Guide to Pakistan Stocks

So Delicious Dessert Recall: Affected Products, FDA Guidelines, and Consumer Action

Pakistan’s Current Account Deficit Narrows Sharply to $98 Million in August 2026

Japan Eyes 3.5% Defense Spending: What It Means for Bonds, Stocks, and the BOJ

Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities

Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World

Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns

China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech

What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact

15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025

How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide

Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide

Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
-
 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
 Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
 Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
 Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
 AI11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
 Taxes & Compliance9 months ago
How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide
China Economy
China’s Record $1.2 Trillion Trade Surplus in 2025 Defies Trump Tariffs — And Signals a New Global Order
Beijing’s strategic pivot to Southeast Asia, Africa, and Latin America pays dividends as Chinese exporters outmaneuver US trade barriers
On a humid January morning at Shenzhen’s Yantian Port, one of the world’s busiest container terminals, the rhythmic clang of cranes loading shipping containers tells a story that Washington policymakers didn’t anticipate. Despite President Donald Trump’s aggressive tariff regime, which slashed Chinese exports to the United States by roughly 20% in 2025, the port’s traffic has surged. The destination tags reveal the plot twist: Lagos, Jakarta, São Paulo, Ho Chi Minh City—everywhere, it seems, except American shores.
This scene encapsulates China’s remarkable trade performance in 2025. The country closed the year with a record-breaking trade surplus of approximately $1.19 trillion—a 20% jump from 2024’s $992 billion—according to data released January 14, 2026, by China’s General Administration of Customs. The figures represent not just a numerical milestone but a fundamental recalibration of global trade flows, one that challenges assumptions about America’s economic leverage and heralds what some analysts are calling a “post-Atlantic” trading order.
The Numbers: A Surplus Built on Strategic Diversification
China’s 2025 trade data reveals an economy executing a carefully orchestrated pivot. Total exports climbed 5.5% to $3.77 trillion, while imports remained virtually flat at $2.58 trillion, expanding the trade imbalance to unprecedented levels. December alone saw exports surge 6.6% year-over-year—faster than any economist predicted—defying concerns about front-loading effects from 2024’s rush to beat anticipated tariffs.
The composition of this growth tells the real story. While shipments to the United States plummeted—declining in nine consecutive months and dropping 30% in December alone, for a full-year decline of approximately 20%—Chinese exporters found eager customers elsewhere. According to customs spokesperson Lv Daliang, growth rates to emerging markets “all surpassed the overall rate,” revealing Beijing’s successful execution of what trade analysts call the most significant export diversification campaign by a major economy in modern history.
Africa led the charge with a stunning 26% increase in Chinese exports, followed by ASEAN nations at 13%, Latin America at 7%, and the European Union at 8%. These aren’t marginal markets absorbing overflow; they represent a structural reorientation. In absolute terms, China’s trade with ASEAN countries alone is projected to have exceeded $1.05 trillion in 2025, cementing the bloc’s position as Beijing’s largest trading partner—surpassing both the United States and European Union.
The product mix has also evolved. Higher-value exports—semiconductors, automobiles, and ships—all recorded gains exceeding 20%, while lower-end products like toys, shoes, and clothing contracted. Auto exports alone surged 21% to more than 7 million units, driven by electric vehicles and plug-in hybrids that are reshaping global automotive supply chains.
The Tariff Jolt and Beijing’s Long Game
The Trump administration’s tariff offensive, which escalated throughout 2025 with duties approaching 60% on some Chinese goods, was designed to bring Beijing to heel. Instead, it accelerated trends that Chinese policymakers had been cultivating since the first trade war began in 2018. The difference this time was both the scale of US measures and the sophistication of China’s response.
Beijing’s playbook drew heavily from its Dual Circulation strategy, articulated in 2020 but turbocharged after Trump’s 2024 election victory signaled renewed trade hostilities. As described by the World Economic Forum, this framework emphasized reducing vulnerability to Western pressure through trade diversification, industrial upgrading, and domestic resilience—precisely the pillars that bore fruit in 2025.
“The authorities have been preparing for this moment since at least 2017,” notes Markus Herrmann Chen, founder of China Macro Group. Trade with Belt and Road Initiative participating countries reached RMB 11.6 trillion ($1.6 trillion) by 2021, according to the Atlantic Council—far surpassing trade with the EU or United States. By 2025, this diversification had reached critical mass.
The policy infrastructure supporting this shift included export financing facilities, expedited customs clearance for emerging market destinations, upgraded free trade agreements (including the newly enhanced China-ASEAN FTA finalized in May 2025), and diplomatic campaigns that paired infrastructure investments with market access. Meanwhile, a weakening yuan—reflecting domestic deflationary pressures—made Chinese goods even more price-competitive globally, with export prices declining for their third consecutive year.
Diversification in Action: Three Theaters of Expansion
Southeast Asia: The Manufacturing Nexus
Vietnam, Indonesia, Thailand, and Malaysia have become the frontline states in China’s geographic pivot. Chinese exports to ASEAN grew 13% in 2025, but the relationship runs deeper than simple trade flows. As Rhodium Group documents, Chinese manufacturing FDI into ASEAN averaged $10 billion over the past three years—nearly four times the 2014-2017 average—with Indonesia and Vietnam together attracting 56% of investment value.
This isn’t merely about circumventing tariffs through “transshipment”—though that certainly occurs and has triggered US scrutiny. Chinese firms are establishing genuine production capacity, particularly in electric vehicles, solar panels, electronics, and steel. BYD’s multi-billion-dollar EV plants in Thailand, CATL’s battery facilities across the region, and countless component manufacturers represent a reconfiguration of supply chains that will outlast any tariff regime.
The integration is symbiotic but asymmetric. ASEAN countries rely heavily on Chinese intermediate inputs—averaging one-third of their imported materials, according to East Asia Forum—meaning Chinese value-added content in “ASEAN-made” exports remains substantial. Vietnam’s exports to the US surged 30% in 2025, powered by electronics and textiles, but many incorporate Chinese components assembled by Chinese-invested factories employing Chinese supply chain management.
Yet this dependence cuts both ways. As Asia Society research warns, the flood of finished Chinese goods—particularly EVs, solar panels, and consumer electronics—is displacing local production. Indonesia’s textile sector shed 80,000 jobs in 2024, with 280,000 more at risk in 2025. Thailand has seen Japanese automakers like Subaru, Suzuki, and Nissan close factories as Chinese EVs capture market share. The challenge for ASEAN is navigating between benefiting from Chinese investment and protecting nascent industries from predatory pricing.
Africa: The Consumption Frontier
China’s 26% export surge to Africa in 2025 marks a qualitative shift in the relationship. While infrastructure projects and resource extraction have long defined China-Africa ties, 2025 saw Beijing pivot decisively toward consumer markets. Chinese exports to the continent in the first three quarters rose 28% year-over-year to approximately $122 billion, according to Bloomberg analysis, driven by construction machinery, passenger cars, steel, electronics, and solar panels (which jumped 60%).
Nigeria led African imports, accounting for 11% of the total at approximately 4.66 trillion naira, followed by South Africa (10%), Egypt (9%), and others. The CNBC investigation of social media posts and business registrations reveals thousands of Chinese entrepreneurs establishing small businesses across African cities—selling electronics, bubble tea, furniture, press-on nails—targeting Africa’s emerging middle class of 350 million consumers.
This expansion comes as profit margins narrow at home amid deflation and intense competition. “Africa benefits from cheap consumer goods,” observes Capital Economics, “but risks undermining local manufacturing and deepening trade imbalances.” Indeed, Africa’s trade deficit with China ballooned to nearly $60 billion through August 2025, perpetuating colonial-era patterns: raw materials (oil, minerals, cobalt, copper) flow to China while manufactured goods flow back.
Kenya exemplifies both opportunity and vulnerability. Chinese construction machinery and solar panels support infrastructure development, while Chinese EVs offer affordable transport options. Yet as ISS Africa notes, much of Africa’s exports to China are controlled by Chinese-owned firms operating on the continent, with earnings flowing back to foreign investors rather than stimulating local value chains. Without aggressive local content requirements and industrial policy, the $200 billion projected for China-Africa trade in 2025 may reinforce dependency rather than catalyze development.
Latin America: The EV Battleground
Latin America absorbed approximately $276 billion in Chinese exports by November 2025—up nearly 8% despite the ongoing US-China trade conflict. Brazil emerged as China’s prize market, with exports soaring over 25% to reach $30 billion in the first five months alone, according to Americas Market Intelligence. The star attraction: electric vehicles.
Brazil imported approximately 130,000 Chinese EVs in just the first five months of 2025—a tenfold increase from 2024—making it China’s largest EV export market globally. BYD is investing heavily in Brazilian production facilities, planning to manufacture 10,000 units in 2025 and 20,000 by end-2026. American Century Investments reports similar dynamics in Mexico, where Chinese auto exports rose 36%, and Argentina, where imports of Chinese goods nearly doubled amid bilateral RMB payment agreements that eased dollar shortages.
Beyond autos, Chinese exports span industrial machinery, telecommunications equipment, steel, and construction materials supporting infrastructure development. Peru’s Chancay megaport, a Chinese-funded deep-water facility designed to service ultra-large container ships, symbolizes Beijing’s long-term regional ambitions—creating logistics infrastructure that will funnel South American commodities to Asia while providing entry points for Chinese manufactured goods.
Yet geopolitical tensions simmer beneath the commerce. Mexico faces intense US pressure to impose tariffs on Chinese goods and guard against “transshipment” of China-made products bound for American markets. In December 2025, Mexico approved a sweeping overhaul of import taxes affecting 1,463 tariff lines across 17 strategic sectors, targeting China and other nations. The Trump administration has explicitly warned Mexico that failure to curb Chinese imports could trigger US tariffs on Mexican exports—a pressure campaign that reveals Washington’s anxieties about losing influence in its own hemisphere.
Domestic Drivers: Deflation as Export Engine
The paradox of China’s export boom is that it reflects economic weakness as much as strength. Behind the record surplus lies a structural malady: anemic domestic consumption and persistent deflation that has forced Chinese manufacturers to seek markets abroad rather than building demand at home.
China’s consumer prices remained flat in 2025, missing the official 2% target, while the GDP deflator—a broad price gauge—declined for ten consecutive quarters through late 2025. Factory-gate prices have been in deflationary territory since October 2022. This isn’t a statistical quirk; it reflects weak household demand, a property sector that has contracted by half since its 2021 peak, and local government fiscal crises that constrain public spending.
“No economy has recorded 5% real GDP growth while facing years of persistent deflation,” argues Logan Wright of Rhodium Group in a December 2025 analysis. He estimates China’s actual 2025 growth fell short of 3%, far below the official 5% target, with domestic demand “anemic and confined to modest household consumption expansion.”
The International Monetary Fund’s December 2025 assessment is blunt: “The prolonged property sector adjustment, spillovers to local government finances, and subdued consumer confidence have led to weak domestic demand and deflationary pressures.” IMF Managing Director Kristalina Georgieva called for “more forceful and urgent” policies to transition to consumption-led growth, warning that “reliance on exports is less viable for sustaining robust growth” given China’s massive economic size and heightened global trade tensions.
The feedback loop is pernicious. Deflation encourages households to delay purchases and increase savings (China’s household savings rate remains among the world’s highest). Weak domestic demand forces manufacturers to cut prices, triggering brutal price wars—particularly in automotive, solar, and steel—that further erode profitability and investment. Unable to earn returns domestically, companies dump products abroad at marginal cost, creating the export surge that manifests as a trade surplus.
“The swelling surplus underscores the imbalance between China’s manufacturing strength and stubbornly weak domestic consumption,” observes Business Standard. It’s a symptom, not a sign of health—akin to Germany’s persistent surpluses during its “sick man of Europe” phase or Japan’s export dependence during lost decades of deflation.
Global Ripples: Winners, Losers, and Backlash
China’s export offensive creates ripple effects across the global economy, producing both opportunities and tensions that will shape trade policy for years.
Emerging market pressures: While developing nations benefit from affordable Chinese capital goods, consumer electronics, and infrastructure inputs, they face mounting risks. Local manufacturers struggle against subsidized competition. Capital Economics warns that “governments in Nigeria, South Africa, and Kenya may seek to defend respective industries,” but most commodity-dependent African nations “are likely to prioritize trade ties with China over industrialization ambitions.” The trade-off between cheap imports and industrial development presents a Faustian bargain.
Currency effects and financial flows: China’s deflationary pressures have driven real exchange rate depreciation, making exports even more competitive. The current account surplus reached 3.7% of GDP in Q1 2025, but this was offset by significant capital outflows as Chinese investors sought returns abroad and hedged against domestic uncertainties. The World Bank’s December 2025 update notes that “larger net capital outflows outweighed the current account surplus,” reflecting private-sector concerns about China’s economic trajectory.
Protectionist backlash: The flood of Chinese goods is triggering defensive measures globally. The European Union faces growing political pressure to counter what officials describe as unfair competition from state-subsidized Chinese manufacturers, particularly in EVs, solar panels, and steel. Preliminary EU tariffs on Chinese EVs reached as high as 45%, while solar panel duties from Southeast Asian countries (themselves hosting Chinese production) range from 21% to 271%. Brazil, Turkey, and India have imposed automotive tariffs. Even Russia—China’s largest auto export market in 2023-2024—recently enacted non-tariff barriers to protect domestic production.
US strategic concerns: Washington’s anxieties extend beyond economics. The Trump administration’s “transshipment” provisions, which threaten 40% tariffs on goods deemed to have been illegally rerouted through third countries, aim squarely at Chinese supply chain strategies in ASEAN and Mexico. S&P Global analysis warns that strict rules-of-origin enforcement could “adversely affect export competitiveness” of Malaysia, Singapore, Thailand, and Vietnam—countries with low domestic value content but high Chinese integration.
The geopolitical subtext is unmistakable. As Americas Quarterly notes, China’s infrastructure investments and manufacturing presence in Latin America represent “a direct challenge to US dominance in the region.” Chinese space facilities in Argentina, ports in Peru, and 5G networks across the hemisphere trigger national security debates in Washington, revealing that trade battles mask deeper great-power competition.
What Comes Next: Risks and Rebalancing
The sustainability of China’s export-driven model faces mounting challenges that will test Beijing’s economic management in 2026 and beyond.
Overcapacity and market saturation: China’s manufacturers expanded production capacity dramatically during the pandemic, anticipating continued growth. As domestic demand faltered, this capacity became stranded, forcing companies to export at unsustainably low prices. The risk, as Rhodium Group observes, is that “overcapacity flooding” will provoke coordinated international responses—tariffs, anti-dumping duties, investment restrictions—that close off markets faster than Beijing can diversify.
Lynn Song, chief economist for Greater China at ING Groep, warns China faces “some pushback” as its higher-end products become globally competitive. The more successfully Chinese firms move up the value chain—competing in EVs, semiconductors, renewable energy—the more likely they are to trigger defensive industrial policies from advanced economies protecting strategic sectors.
Geopolitical fragmentation: The rules-based trading system that facilitated China’s rise is fracturing. As emerging markets become battlegrounds between Chinese commercial interests and Western political pressure, countries face increasingly binary choices. The US is weaponizing market access, conditioning trade relationships on partners’ willingness to limit Chinese participation. Mexico’s tariff reforms exemplify this squeeze—economic logic suggests embracing Chinese investment, but geopolitical realities demand demonstrating alignment with Washington.
Domestic rebalancing imperatives: Every major international institution—the IMF, World Bank, OECD—agrees that China must transition to consumption-driven growth. Yet 2025 demonstrated how difficult this transformation is. Retail sales growth barely exceeded 1% by year-end, despite trade-in subsidies and consumption vouchers. The property crisis shows no signs of resolution, local government debt problems worsen, and deflationary psychology becomes more entrenched with each passing quarter.
The IMF’s December 2025 assessment projects China’s growth will moderate to 4.5% in 2026 (down from 5% in 2025) as “it would take time for domestic sources of growth to kick in.” Sonali Jain-Chandra, the IMF’s China Mission Chief, argues that “macro policies need to focus forcefully on boosting domestic demand” to “reflate the economy, lift inflation, and lead to real exchange rate appreciation”—precisely the medicine Beijing has been reluctant to administer.
The 2026 outlook: Natixis economist Gary Ng forecasts Chinese exports will grow about 3% in 2026, down from 5.5% in 2025, but with slow import growth, he expects the trade surplus to remain above $1 trillion. This would represent a third consecutive year of record surpluses—unprecedented for an economy of China’s scale and development level.
The comparison to historical precedents is instructive. Germany ran persistent current account surpluses approaching 8% of GDP in the 2010s, triggering criticism but ultimately reflecting structural savings-investment imbalances. Japan’s export dominance in the 1980s provoked “voluntary” export restraints and contributed to asset bubbles when yen appreciation finally arrived. China’s $1.2 trillion surplus in 2025 represented roughly 6-7% of GDP—a figure that would be unsustainable indefinitely without either forced adjustment through currency appreciation or external pressure through coordinated tariffs.
Conclusion: A Pyrrhic Victory?
China’s record $1.2 trillion trade surplus in 2025 demonstrates the resilience and adaptability of the world’s manufacturing superpower. Against expectations, Chinese exporters not only survived the Trump administration’s tariff assault but thrived, finding eager customers from Lagos to Jakarta to São Paulo. The successful execution of trade diversification—years in planning, accelerated by necessity—has reduced China’s vulnerability to any single market and cemented commercial relationships across the Global South.
Yet this triumph carries hidden costs and uncertain longevity. The surplus reflects not vibrant economic health but the malaise of a economy unable to generate sufficient domestic demand to absorb its own productive capacity. Deflation, property crisis, and weak consumer confidence reveal structural imbalances that export growth merely postpones addressing rather than resolving. Every major international economic institution warns that export-led growth is reaching its natural limits for an economy of China’s scale.
Geopolitically, China’s export offensive is hardening Western resolve to reduce dependencies and rebuild domestic industrial capacity—the very “decoupling” Beijing sought to avoid. The more successful Chinese manufacturers become at penetrating global markets, the more protectionist the response grows. We are witnessing not the end of US-China trade conflict but its globalization, as secondary markets become contested terrain and supply chains fragment along geopolitical lines.
For global policymakers, 2025’s trade data poses a fundamental question: Can the international economy accommodate a manufacturing superpower running trillion-dollar surpluses year after year? History suggests not without significant adjustment—through currency appreciation, domestic rebalancing, or external pressure. The lesson of 2025 is that Chinese firms are extraordinarily capable of adapting to barriers and finding new markets. The lesson of 2026 may be that even the most successful export diversification cannot indefinitely substitute for robust domestic demand.
As containers continue loading at Shenzhen’s ports, bound for an ever-widening array of destinations, the numbers tell a story of tactical success masking strategic vulnerability. China has won the battle against Trump’s tariffs. The war for sustainable economic growth, however, requires victories on the home front that remain frustratingly elusive.
China’s economy in 2026 is a study in contradiction. In its largest cities — Shanghai, Beijing, Guangzhou, Shenzhen — new-home prices have risen for three consecutive months, driven by targeted policy support that is beginning to show traction. Across the remaining hundreds of cities, prices are still falling at a pace that is accelerating, not slowing.
National property investment fell 16.2% year-over-year in the first five months of 2026 — a staggering contraction in a sector that once accounted for roughly a quarter of Chinese GDP. At the same time, China’s technology sector is attracting record capital flows, its export machine is running at full throttle despite global trade tensions, and the People’s Bank of China (PBOC) is quietly implementing some of the most significant monetary architecture reforms in a generation.
China is, in effect, running two economies simultaneously. Understanding which one dominates the other will determine the trajectory of global markets for the next several years.
The Property Sector: A Structural Wound, Not a Cyclical Dip
China’s real estate crisis is entering its fifth year. What began with the 2021 Evergrande collapse has evolved into a sustained structural contraction that is fundamentally reshaping the economic role of property in China’s growth model.
National home prices declined at a faster pace in May 2026 than in April, a sign that market conditions are deteriorating rather than stabilising at the aggregate level. The OECD inventory of unsold homes across China’s lower-tier cities remains enormous — a structural supply overhang that cannot be resolved by demand-side stimulus alone.
The policy response has been asymmetric by design. The central government’s support measures are concentrated in Tier 1 and select Tier 2 cities, where local governments have more fiscal capacity to implement purchase subsidies, down-payment reductions, and mortgage rate cuts. In these markets, the policy appears to be working: new-home prices in China’s first-tier cities rose for the third consecutive month in May.
But first-tier cities account for a small fraction of China’s total housing stock. The vast majority of property — and the vast majority of household wealth — is concentrated in smaller cities where policy support is less effective and price declines are continuing.
The macro consequence is a negative wealth effect that is suppressing consumer confidence and retail spending precisely at the moment China needs domestic demand to compensate for a structurally lower export environment.
The PBOC’s Quiet Revolution
While the property sector weighs on growth, the People’s Bank of China has been implementing a series of significant monetary policy reforms. PBOC Governor Pan Gongsheng announced measures in June 2026 that include:
- Increased use of overnight reverse repo operations, a technical adjustment that improves the PBOC’s ability to manage short-term liquidity conditions with precision
- Narrowing the short-term interest rate corridor, reducing volatility in interbank lending rates and improving monetary policy transmission
- Steps to support the offshore use of the renminbi, accelerating the internationalisation of the Chinese currency as part of China’s longer-term strategy to reduce dependency on the US dollar in global trade and finance
These announcements are significant, but should not be misread as a broad-based monetary stimulus package. The PBOC is reforming its operational framework and improving financial market infrastructure — not firing an economic bazooka. The distinction matters for investors who might expect a China stimulus surge analogous to 2009 or 2015.
For investors, the PBOC’s focus on financial market development and liquidity management signals that policymakers are prioritising long-term stability over short-term growth stimulus. This implies a more gradual recovery trajectory than markets have sometimes assumed.
China’s Export Machine: A Source of Strength and Tension
Against the backdrop of the property slump, China’s export sector is performing exceptionally well. China’s trade surplus has expanded significantly in 2026, driven by:
- Industrial overcapacity in sectors including steel, solar panels, electric vehicles, chemicals, and lithium-ion batteries
- A weaker renminbi that has improved price competitiveness for Chinese exporters in global markets
- Continued strong demand for Chinese manufactured goods from Southeast Asia, Latin America, and Africa — markets that have deepened trade ties with China as US-China trade friction has redirected some Western procurement
China’s strong export growth has sparked significant international pushback. Policymakers across the European Union, the United States, and major emerging markets have expressed concerns about industrial overcapacity and the impact of low-cost Chinese exports on domestic manufacturing industries. The EU has implemented additional tariffs on Chinese electric vehicles, and US tariffs on a broad range of Chinese goods remain elevated following the Trump administration’s tariff regime.
The structural tension: China needs export growth to compensate for weak domestic demand, but its export success is generating the geopolitical friction that could ultimately constrain market access.
China’s AI Pivot: From Property Developer to Tech Powerhouse
The most significant transformation in China’s economic structure in 2026 is not occurring in housing — it is occurring in technology. China’s leadership has made a deliberate and well-resourced pivot toward artificial intelligence, semiconductors, and advanced manufacturing as the new engines of economic growth.
Chinese technology companies including Huawei, Baidu, Alibaba, and ByteDance are investing at scale in AI model development, AI chip design, and AI-integrated enterprise applications. The Chinese government’s industrial policy support for these sectors — through subsidies, preferential financing, and regulatory facilitation — is mobilising capital at a pace that rivals the hyperscaler buildout in the United States.
The strategic motivation is clear: reduce dependency on US semiconductor technology (particularly following US export controls on advanced chips), build sovereign AI capability across defence, governance, and commercial applications, and position Chinese technology companies as global AI leaders in markets outside the Western sphere.
This pivot is creating investment opportunities in Chinese technology equities — though geopolitical risk, regulatory uncertainty, and the US export control regime create complex risk factors that must be weighed carefully by international investors.
The Global Market Implications
China’s two-speed economy creates distinct implications for different asset classes and geographic markets:
Commodities: The property sector contraction is the dominant factor for commodity demand. Steel, copper, cement, and glass — all deeply tied to construction activity — face sustained headwinds from Chinese property weakness. Iron ore prices reflect this dynamic. In contrast, Chinese demand for technology-related commodities (lithium, cobalt, rare earths) remains robust as the EV and battery supply chain continues to scale.
Asian equities: The MSCI Emerging Markets index has significant China weighting, and China’s two-speed dynamics are creating divergence between technology-oriented Chinese equities (performing well) and property/financial sector stocks (underperforming). Country selection and sector allocation matter enormously in the current Chinese equity environment.
Currency markets: The PBOC’s renminbi internationalisation measures represent a long-duration effort to reduce dollar dependence. In the near term, currency management remains a key PBOC tool — managed depreciation to support exporters, with intervention to prevent disorderly moves that could trigger capital outflows.
European and US corporates: Companies with significant China exposure face a bifurcated operating environment — strong demand in technology-related end markets, weak demand in consumer and construction-related segments. Luxury goods, industrials, and materials companies are disproportionately affected by the property sector contraction.
The Policy Outlook: What Comes Next
The Chinese government faces a genuinely difficult policy dilemma. Aggressive fiscal or monetary stimulus risks reigniting the debt dynamics that made the property crisis inevitable in the first place. Insufficient support risks a deeper consumer confidence collapse that could turn a structural slowdown into a sharper cyclical downturn.
The current policy approach — targeted support for Tier 1 property markets, incremental PBOC reforms, and aggressive industrial policy investment in technology sectors — represents a careful balancing act. It is not the big bang stimulus that some investors have anticipated, but it is also not the hands-off approach that would allow a disorderly collapse.
The most likely trajectory: China grows at 4.0%–4.5% in 2026, below its historical average but ahead of the IMF’s revised global growth forecast of 3.1%. The property sector continues to weigh on domestic demand, while exports and technology investment provide partial offsets. The renminbi remains managed, and the PBOC avoids large-scale interest rate cuts that would widen the US-China rate differential and accelerate capital outflows.
The Bottom Line
China’s economy in 2026 is not in crisis, but it is in transition — and the transition is proving slower and more painful than the optimists predicted. The property sector wound is structural, not cyclical. The technology pivot is real but will take years to fully offset the economic weight that property once carried.
For global investors, China remains the world’s second-largest economy and a critical driver of commodity, trade, and technology markets. Ignoring it is not an option. But the analytical frameworks from the 2010s — property-led, infrastructure-driven, credit-fuelled growth — are no longer the right lens through which to assess Chinese economic dynamics in 2026.
The new China story is being written in data centres, EV factories, and AI labs — not in unfinished apartment towers.
FAQs
Q: What is happening with China’s economy in 2026?
A: China is running a two-speed economy. The property sector is contracting sharply — investment fell 16.2% year-over-year in early 2026 — while technology investment, AI spending, and exports are growing. The PBOC is implementing monetary reforms without large-scale stimulus.
Q: Is China’s property market recovering in 2026?
A: Partially and unevenly. New home prices in Tier 1 cities rose for three consecutive months through May 2026, suggesting policy support is gaining traction in the largest markets. Nationally, however, prices declined at a faster pace in May than April, and the recovery remains uneven across regions.
Q: What is China’s GDP growth forecast for 2026?
A: Most forecasters project China’s GDP growth at approximately 4.0%–4.5% in 2026 — below historical averages but above the IMF’s global average of 3.1%. The property sector contraction is the primary drag, partially offset by technology investment and export growth.
Q: How is China’s AI investment affecting global markets?
A: China’s AI and technology pivot is creating strong demand for technology-related commodities (lithium, rare earths), boosting Chinese technology equities, and intensifying competition with US and European AI companies — particularly in markets outside the Western sphere.
When silver prices cratered by a historic 27% on January 30, 2026—wiping out $150 billion in market value within hours—most traders scrambled to stanch the bleeding. Yet one firm turned catastrophe into windfall. Zhongcai Futures, the proprietary trading house controlled by reclusive Chinese entrepreneur Bian Ximing, banked over $500 million by betting against the very rally that entranced global speculators, according to reports from the Financial Times and market observers.
The profit haul marks another stunning victory for the 61-year-old plastics magnate turned commodities oracle, whose contrarian instincts have repeatedly outmaneuvered Wall Street’s conventional wisdom. After pocketing $1.5 billion from prescient gold futures trades between 2022 and 2024, Bian’s Shanghai-based brokerage executed short positions on silver just as the white metal approached its dizzying peak above $121 per ounce in late January—a record that would prove ephemeral.
The Silver Supercycle That Wasn’t
Silver’s ascent in late 2025 and early 2026 resembled nothing witnessed since the Hunt Brothers’ infamous squeeze four decades prior. Fueled by a confluence of factors—Chinese retail speculation, artificial intelligence’s voracious appetite for the metal’s thermal properties, and mounting concerns over currency debasement—prices rocketed from approximately $32 per ounce in early 2025 to an intraday high near $121 by late January 2026, representing a staggering 276% surge.
The narrative captivating markets was compelling: silver’s unrivaled electrical and thermal conductivity had become indispensable for next-generation AI chip manufacturing. Data center construction exploded as Large Language Models demanded increasingly sophisticated cooling systems, with silver-sintered thermal pastes emerging as the industry standard. Industrial demand appeared insatiable.
Yet beneath the euphoria lurked structural fragilities. As Bloomberg chronicled, speculative fever gripped Shanghai trading floors, where individual investors and equity funds venturing into commodities drove prices divorced from supply-demand fundamentals. Trend-following commodity trading advisers amplified the momentum, creating what analysts later termed a “speculative bubble” rather than a durable industrial squeeze.
By mid-January, the iShares Silver Trust (SLV) recorded unprecedented call option volumes exceeding those of the Nasdaq 100 ETF—a harbinger of the volatility to come. When silver futures surged past $110 per ounce, the CME Group implemented emergency measures, transitioning to percentage-based margin requirements that hiked maintenance margins to 15% for standard positions. The Shanghai Futures Exchange followed suit with multiple rounds of restrictions throughout January.
These administrative interventions would prove decisive. As reported across financial media, the margin hikes forced leveraged speculators who had controlled 5,000-ounce contracts with minimal collateral into a “margin trap,” triggering cascading liquidations that accelerated the selloff.
Zhongcai’s Contrarian Gambit
While retail investors queued for hours outside European bullion dealers and Chinese traders posted thousand-percent gains on social media, Bian Ximing’s team pursued a different calculus. Operating from Gibraltar—where Bian conducts business largely via video calls, maintaining his characteristic distance from Shanghai’s trading floors—Zhongcai Futures established short positions on the Shanghai Futures Exchange as silver approached its zenith.
The timing proved exquisite. On January 30, silver commenced its historic plunge around 10:30 AM Eastern Time, declining to $119 before President Trump’s announcement of Kevin Warsh as Federal Reserve chair nominee at 1:45 PM—a development widely cited as the crash catalyst, though the selloff had already eliminated 27% of silver’s value by that point. By session’s end, spot silver settled near $84 per ounce, representing a $37 per ounce drop in under 20 hours.
The mechanics behind Zhongcai’s profits illuminate Bian’s investment philosophy. Rather than chasing parabolic moves, he focuses on identifying structural imbalances and positioning for mean reversion. His sporadic blog posts—parsed religiously by Chinese traders seeking to emulate his hedge fund-style approach—emphasize “letting go of ego,” choosing targets based on trends, and maintaining discipline on costs. “Investment is essentially a game of survival capability,” Bian wrote in a January reflection, weeks before silver’s collapse.
Market observers note that Zhongcai’s short positions likely concentrated on Shanghai contracts rather than COMEX, providing natural hedges as Chinese markets remained closed during Lunar New Year holidays that shielded domestic traders from the worst intraday volatility when global prices briefly tumbled. The firm’s $500 million gain reflects not merely directional conviction but sophisticated execution across timing, venue selection, and risk management.
Anatomy of the Rout: Why Silver Crashed
The January 30 selloff represented multiple failures converging simultaneously. First, the paper silver market—ETFs and futures trading many multiples of physical metal volume—had disconnected dangerously from underlying supply. The 28% single-day drop in SLV, its worst session since inception, exposed how financialized commodity instruments can gap violently when speculation reaches fever pitch.
Second, exchange-mandated margin increases forced deleveraging precisely when positions were most extended. With silver at $120, a standard 5,000-ounce contract carried $600,000 in notional exposure; CME’s 15% maintenance requirement meant traders suddenly needed $90,000 versus previous minimums around $25,000. Those unable to meet calls faced automatic liquidation, creating self-reinforcing downward pressure.
Third, high-frequency trading dynamics amplified the cascade. Chinese authorities’ early-2026 moves to remove servers from exchange data centers and halt subscriptions in certain commodity fund products—including the UBS SDIC Silver Futures Fund—mechanically reduced marginal demand just as volatility peaked. When algorithms detected price deterioration, automated selling intensified the rout.
Current silver prices hovering around $90 per ounce as of February 4, 2026, reflect partial recovery from the lows but remain dramatically below late January peaks. The metal has stabilized approximately 176% above year-ago levels, though technical analysts identify the $75-$80 range as critical support—the consolidation zone before silver’s final parabolic surge.
Bian Ximing: The Invisible King of Futures
Born in 1963 in Zhuji, Zhejiang Province, during China’s tumultuous Cultural Revolution, Bian Ximing’s trajectory from vocational school graduate to billionaire commodities trader embodies calculated risk-taking married to macroeconomic foresight. After founding a high-end plastic tubes factory in 1995, he diversified into real estate, finance, and media, acquiring the brokerage that became Zhongcai Futures in 2003.
His reputation crystallized through his 2022-2024 gold play. Anticipating global efforts to reduce dollar reliance amid inflation fears, Bian established long positions at gold’s mid-2022 lows and scaled holdings through 2023, ultimately exiting near bullion’s 2024 peaks with an estimated $1.5 billion profit. The success earned him comparisons to Warren Buffett for his patient, fundamentals-driven approach—a rarity among China’s more speculative trading culture.
Yet Bian’s latest copper bet demonstrates his agility. As of May 2025 reports, Zhongcai held the largest net long copper position on the Shanghai Futures Exchange—nearly 90,000 tons worth approximately $1 billion—wagering on the metal’s centrality to electrification and China’s high-tech industrial transition. That position has generated roughly $200 million in profits to date, per Bloomberg calculations.
The silver short, however, marks a tactical pivot. While maintaining copper longs, Zhongcai recognized silver’s speculative excess and positioned accordingly—illustrating Bian’s capacity to hold seemingly contradictory views on related assets when fundamentals diverge. His lieutenants occasionally post “reflections” on the company site, offering glimpses into a trading operation that blends Western institutional discipline with shrewd navigation of China’s distinct market structure.
Market Implications: What Comes Next for Precious Metals
The silver crash holds sobering lessons for commodity markets increasingly dominated by momentum strategies and retail speculation. First, even genuine industrial demand stories—silver’s role in AI infrastructure is legitimate—can be overwhelmed by speculative excess. When paper markets far exceed physical volumes, financialization creates vulnerabilities to sharp corrections.
Second, regulatory interventions matter. Exchange margin adjustments, while prudent for systemic stability, can trigger violent moves when implemented amid extended positioning. Traders operating with maximum leverage learned painfully that exchanges prioritize clearinghouse solvency over individual P&L.
Third, the episode underscores China’s growing influence on global commodity prices. Chinese retail and institutional flows drove silver’s rally and contributed to its collapse, with domestic regulatory actions—HFT crackdowns, fund redemption halts—rippling across international markets. As geopolitical tensions persist, understanding China’s market structure becomes essential for commodity investors worldwide.
Looking ahead, analysts divide on silver’s trajectory. Citigroup analysts maintain $150 targets, citing structural supply deficits and AI-driven demand as justifying a new $65-$70 floor even after the correction. Bears counter that January’s crash revealed demand isn’t as inelastic as bulls assumed; at $100-plus per ounce, industrial substitution and demand destruction become economic imperatives.
Gold faces similar crosscurrents, having plunged 12% on January 30 to below $5,000 per ounce after touching $5,602 earlier that week. While central bank purchases and geopolitical risk support longer-term bullion strength, the correction demonstrates that even traditional safe havens aren’t immune to sentiment reversals when positioning grows extreme.
For copper, Bian’s continued conviction through recent trade-war volatility signals confidence in China’s economic resilience and secular electrification trends. Major players like Mercuria forecast $12,000-$13,000 per ton, well above current $9,500 levels, if supply constraints and infrastructure demand materialize as expected.
The Broader Lessons
Zhongcai’s silver windfall exemplifies timeless trading principles that transcend specific asset classes. Bian Ximing’s success stems from identifying crowded trades, maintaining discipline when markets grow euphoric, and executing with precision when others capitulate. His ability to profit from both gold’s rise (2022-2024) and silver’s fall (January 2026) reflects not market timing alone but understanding market structure, sentiment extremes, and the mechanics of leveraged speculation.
For institutional investors, the episode reinforces why derivatives exposure requires rigorous risk management. The 99% long liquidation rate during silver’s crash—$70.52 million wiped out in four hours according to data compiled by ChainCatcher News and HyperInsight—illustrates how one-directional positioning leaves little room for error when volatility strikes.
Retail traders, meanwhile, confront uncomfortable truths about information asymmetries. While Zhongcai operated with deep liquidity and sophisticated infrastructure, individual investors often lacked real-time data on margin adjustments and exchange positioning. The “invisible king of futures” capitalizes partly on seeing what others miss—or seeing it faster.
As markets digest January’s tumult, silver’s recovery to $90 per ounce suggests the correction hasn’t destroyed all investor appetite. Physical demand remains robust; Shanghai Gold Exchange premiums over London quotes exceeded $13 per ounce in early February, incentivizing new bullion imports. Mining supply constraints persist, with Fresnillo cutting 2026 guidance and Hecla projecting output below 2025 levels.
Yet the psychological scars will linger. January 2026 joins 1980’s Hunt Brothers collapse and 2011’s post-financial crisis peak as cautionary tales of silver’s volatility. Those betting on precious metals’ inflation-hedge properties must now contend with the reality that speculative fervor can override fundamentals for extended periods—in both directions.
Conclusion: Discipline Triumphs Over Euphoria
In an era when retail traders armed with Reddit forums and leveraged derivatives amplify market moves, Zhongcai’s $500 million silver profit stands as a reminder that disciplined capital allocation still matters. Bian Ximing’s reluctance to chase parabolic rallies, his focus on structural imbalances rather than momentum, and his willingness to position contrarily when consensus grows overwhelming—these attributes explain why his track record sparkles while so many speculators suffer.
As silver stabilizes and investors reassess precious metals allocations, the January crash offers a masterclass in market dynamics. Leverage cuts both ways. Exchange rules trump individual conviction. And occasionally, the trader watching from Gibraltar sees more clearly than the crowd queuing outside Budapest bullion shops.
For those navigating commodity markets in 2026 and beyond, Zhongcai’s success suggests a path forward: respect fundamentals, fear euphoria, and remember that in investing as in life, survival matters more than spectacular gains. The invisible king of futures has spoken—not through interviews or appearances, but through profits earned when others panicked or grew reckless. In that sense, Bian Ximing’s greatest lesson may be the one he’s lived rather than written: that true edge comes not from outsmarting the market, but from outlasting it.
Asia
BYD’s Ambitious 24% Export Growth Target for 2026: Can New Models and Global Showrooms Defy a Slowing China EV Market?
BYD’s auditorium at Shenzhen headquarters that crystallizes the strategic pivot of the world’s largest electric vehicle maker: 1.3 million. This is BYD’s target for overseas sales in 2026, a 24.3% jump from the previous year, as announced by branding chief Li Yunfei in a January media briefing. This figure is more than a goal; it is a declaration. With China’s domestic EV market showing unmistakable signs of saturation and ferocious price wars eroding margins, BYD’s relentless growth engine now depends on its ability to replicate its monumental domestic success on foreign shores. The question echoing through global automotive boardrooms is whether its expanded lineup—including the premium Denza brand—and a rapidly unfurling network of international showrooms can overcome rising geopolitical headwinds and entrenched competition.
The Meteoric Ascent: How BYD Built a Colossus
To understand the magnitude of the 2026 export target, one must first appreciate the velocity of BYD’s ascent. The company, which began as a battery manufacturer, has executed one of the most stunning industrial transformations of the 21st century. In 2025, BYD sold approximately 4.6 million New Energy Vehicles (NEVs), cementing its position as the undisputed volume leader. Crucially, within that figure lay a milestone that shifted the global order: ~2.26 million Battery Electric Vehicles (BEVs), officially surpassing Tesla’s global deliveries and seizing the BEV crown Reuters.
The foundation of this dominance is vertical integration. BYD controls its own battery supply (the acclaimed Blade Battery), semiconductors, and even mines key raw materials. This mastery over the supply chain provided a critical buffer during global disruptions and allows for aggressive cost control. However, the domestic market that fueled this rise is changing. After years of hyper-growth, supported by generous government subsidies, China’s EV adoption curve is maturing. The result is an intensely competitive landscape where over 100 brands are locked in a profit-eroding price war Bloomberg.
BYD’s 2026 Export Blueprint: From 1.05 Million to 1.3 Million
BYD’s overseas strategy is not a tentative experiment but a full-scale offensive, backed by precise tactical moves. The 2025 export base of approximately 1.04-1.05 million vehicles—representing a staggering 145-200% year-on-year surge—provides a formidable launchpad. The 2026 plan, aiming for 1.3 million units, is built on two articulated pillars: product diversification and network densification.
1. New Models and the Premium Denza Push: Li Yunfei explicitly stated the launch of “more new models in some lucrative markets,” which will include Denza-branded vehicles. Denza, BYD’s joint venture with Mercedes-Benz, represents its attack on the premium segment. Launching models like the Denza N9 SUV in Europe and other high-margin markets is a direct challenge to German OEMs and Tesla’s Model X. This move upmarket is essential for improving brand perception and profitability beyond the volume-oriented Seal and Atto 3 (known as Yuan Plus in China) Financial Times.
2. Dealer Network Expansion: The brute-force expansion of physical presence is key. BYD is moving beyond reliance on importers to establishing dedicated dealerships and partnerships with large, reputable auto retail groups in key regions. This provides localized customer service, builds brand trust, and significantly increases touchpoints for consumers. In 2025 alone, BYD expanded its European dealer network by over 40% CNBC.
The Domestic Imperative: Why Overseas Growth is Non-Negotiable
BYD’s export push is as much about necessity as ambition. The Chinese market, while still the world’s largest, is entering a new phase.
- Market Saturation in Major Cities: First-tier cities are approaching saturation points for NEV penetration, pushing growth into lower-tier cities and rural areas where consumer appetite and charging infrastructure are less developed.
- The Relentless Price War: With legacy automakers like Volkswagen and GM fighting for share and nimble startups like Nio and Xpeng launching competitive models, discounting has become endemic. This pressures margins for all players, even the cost-leading BYD The Wall Street Journal.
- Plateauing Growth Rates: After years of doubling, NEV sales growth in China is expected to slow to the 20-30% range in 2026, a dramatic deceleration from the breakneck pace of the early 2020s.
Consequently, overseas markets—with their higher average selling prices and less crowded competition—represent the most viable path for maintaining BYD’s growth trajectory and satisfying investor expectations.
The Global Chessboard: BYD vs. Tesla and the Chinese Cohort
BYD’s international expansion does not occur in a vacuum. It faces a multi-front competitive battle.
vs. Tesla: The rivalry is now global. While BYD surpassed Tesla in BEV volumes in 2025, Tesla retains significant advantages in brand cachet, software (FSD), and supercharging network density in critical markets like North America and Europe. Tesla’s response, including its own cheaper next-generation model, will test BYD’s value proposition abroad The Economist.
vs. Chinese Export Rivals: BYD is not the only Chinese automaker looking overseas. A look at 2025 export volumes reveals a cohort in hot pursuit:
- SAIC Motor (MG): The historic leader in Chinese EV exports, leveraging the MG brand’s European heritage.
- Chery: Aggressive in Russia, Latin America, and emerging markets.
- Geely (Zeekr, Polestar, Volvo): A sophisticated multi-brand approach targeting premium segments globally.
While BYD currently leads in total NEV exports, its rivals are carving out strong regional niches, making global growth a contested space Reuters.
Geopolitical Speed Bumps and Localization as the Antidote
The single greatest risk to BYD’s 2026 export target is not competition, but politics. Tariffs have become the primary tool for Western governments seeking to shield their auto industries.
- European Union: Provisional tariffs on Chinese EVs, varying by manufacturer based on cooperation with the EU’s investigation, add significant cost. BYD’s rate, while lower than some rivals, still impacts pricing.
- United States: The 100% tariff on Chinese EVs effectively locks BYD out of the world’s second-largest car market for the foreseeable future.
BYD’s counter-strategy is localization. By building vehicles where they are sold, it can circumvent tariffs, create local jobs, and soften its political image. Its global factory footprint is expanding rapidly:
- Thailand: A new plant operational in 2024, making it a hub for ASEAN right-hand-drive markets.
- Hungary: A strategically chosen factory within the EU, set to come online in 2025-2026, to supply the European market tariff-free.
- Brazil: A major complex announced, targeting Latin America and leveraging regional trade agreements.
This “build locally” strategy requires massive capital expenditure but is essential for sustainable long-term growth in protected markets Bloomberg.
Risks and the Road Ahead: Brand, Quality, and Culture
Beyond tariffs, BYD faces subtler challenges. Brand perception in mature markets remains a work in progress; shifting from being seen as a “cheap Chinese import” to a trusted, desirable marque takes time and consistent quality. While its cars score well on initial quality surveys, long-term reliability and durability data in diverse climates is still being accumulated.
Furthermore, managing a truly global workforce, supply chain, and product portfolio tailored to regional tastes (e.g., European preferences for stiffer suspension and different infotainment systems) is a complex operational leap from being a predominantly domestic champion.
Conclusion: A Calculated Gamble on a Global Stage
BYD’s 24% export growth target for 2026 is ambitious yet calculated. It is underpinned by a formidable cost structure, a rapidly diversifying product portfolio, and a pragmatic shift to local production. The slowing domestic market leaves it little choice but to pursue this path aggressively.
The coming year will be a critical test of whether its engineering prowess and operational efficiency can translate into brand strength and customer loyalty across cultures. Success is not guaranteed—geopolitical friction is increasing, and competitors are not standing still. However, BYD has repeatedly defied expectations. Its 2026 export campaign is more than a sales target; it is the next chapter in the most consequential story in the global automotive industry this decade—the determined rise of Chinese automakers from domestic leaders to dominant global players. The world’s roads are about to become the proving ground.
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
AI11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
Taxes & Compliance9 months ago
How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide
Leave a Reply