
Investing 101
Gaming Giant’s Bold Gamble: Why Investors are Devouring Risky EA Debt Amid Geopolitical Crosscurrents

Investors are aggressively snapping up debt for Electronic Arts’ historic $55bn take-private, signaling resilient credit markets despite geopolitical tensions and AI disruption. Explore the EA LBO’s financial engineering, cost savings, and the appetite for risky video game financing in 2026.
Introduction: The Unyielding Allure of High-Yield
The world of high finance rarely pauses for breath, even as geopolitical headwinds gather and technological disruption reshapes industries. Yet, the recent $55 billion take-private of video game titan Electronic Arts (EA) has delivered a masterclass in market resilience, demonstrating an almost insatiable investor appetite for leveraged debt—even when tied to a complex, globally-infused transaction. Led by Saudi Arabia’s Public Investment Fund (PIF), Silver Lake, and Affinity Partners, this landmark deal, poised to redefine the gaming M&A landscape, has seen its $18-20 billion debt package met with overwhelming demand, proving that the pursuit of yield often eclipses lingering doubts.
This isn’t merely another private equity mega-deal; it’s a bellwether for global credit markets in early 2026. JPMorgan-led bond deals, designed to finance one of the largest leveraged buyouts in history, have drawn over $25 billion in orders, far surpassing their target size. This aggressive investor embrace of what many consider risky debt, particularly given the backdrop of Middle East tensions and concerns over AI’s impact on software, underscores a fascinating dichotomy: a cautious macroeconomic outlook juxtaposed with an audacious hunt for returns in stable, cash-generative assets. The question isn’t just how this was financed, but why investors dove in with such conviction, and what it signals for the year ahead.
The Anatomy of a Mega-Buyout: EA’s Financial Engineering
At an enterprise value of approximately $55 billion, the Electronic Arts take-private deal stands as the largest leveraged buyout on record, eclipsing the 2007 TXU Energy privatization. The financing structure is a finely tuned orchestration of equity and debt, designed to maximize returns for the acquiring consortium while appealing to a broad spectrum of debt investors.
Equity & Debt Breakdown
The EA $55bn LBO is funded through a combination of substantial equity and a significant debt tranche:
- Equity Component: Approximately $36 billion, largely comprising cash contributions from the consortium partners, including the rollover of PIF’s existing 9.9% stake in EA. PIF is set to own a substantial majority, approximately 93.4%, with Silver Lake holding 5.5% and Affinity Partners 1.1%.
- Debt Package: A substantial $18-20 billion debt package, fully committed by a JPMorgan-led syndicate of banks. This makes it the largest LBO debt financing post-Global Financial Crisis.
Unpacking the Debt Tranches: Demand & Pricing
The sheer scale of demand for this EA acquisition financing has been striking. The initial $18 billion debt offering, which included both secured and unsecured tranches, quickly swelled to over $25 billion in investor orders. This oversubscription highlights a strong market appetite for gaming-backed paper.
Key components of the debt include:
- Leveraged Loans: A cross-border loan deal totaling $5.75 billion launched on March 16, 2026, comprising a $4 billion U.S. dollar loan and a €1.531 billion ($1.75 billion) euro tranche.
- Pricing: Term Loan Bs (TLBs) were guided at 350-375 basis points over SOFR/Euribor, with a 0% floor and a 98.5 Original Issue Discount (OID). This discounted pricing suggests lenders were baking in some risk, yet the demand remained robust.
- Secured & Unsecured Bonds: The financing also features an upsized $3.25 billion term loan A, an additional $6.5 billion of other dollar and euro secured debt, and $2.5 billion of unsecured debt. While specific high-yield bond pricing hasn’t been detailed, market intelligence suggests secured debt at approximately 6.25-7.25% and unsecured north of 8.75%, reflective of the leverage profile.
The Deleveraging Path: Justifying a 6x+ Debt/EBITDA
Moody’s projects that EA’s gross debt will increase twelve-fold from $1.5 billion, pushing pro forma leverage (total debt to EBITDA) to around eight times at closing. Such high leverage ratios typically raise red flags, but the consortium’s pitch centers on EA’s robust cash flows and significant projected cost savings.
Three Pillars Justifying the Leverage
- Stable Cash Flows from Core Franchises: EA boasts an enviable portfolio of consistently profitable franchises, including FIFA (now EA Sports FC), Madden NFL, Apex Legends, and The Sims. These titles generate predictable, recurring revenue streams, particularly through live service models and annual updates, which underpin the company’s financial stability—a critical factor for debt investors.
- Strategic Cost Savings & Operational Efficiencies: The new owners have outlined an aggressive plan for $700 million in projected annual cost savings. This includes:
- R&D Optimization: $263 million from reclassifying R&D expenses for major titles like Battlefield 6 and Skate as one-time costs, now that they are live and generating revenue.
- Portfolio Review: $100 million from a strategic review of the game portfolio.
- AI Tool Integration: $100 million from leveraging AI tools for development and operations.
- Organizational Streamlining: $170 million from broader organizational efficiencies.
- Public Company Cost Removal: $30 million saved by no longer incurring costs associated with being a public entity.
These add-backs significantly bolster adjusted EBITDA figures, making the debt package appear more manageable to prospective lenders. Moody’s expects leverage to decrease to five times by 2029.
- Untapped Growth Potential in Private Ownership: Freed from quarterly earnings pressure, EA’s management can pursue longer-term strategic initiatives and R&D without the immediate scrutiny of public markets. This is particularly appealing for a company operating in an industry prone to rapid innovation and large, multi-year development cycles. The consortium’s diverse networks across gaming, entertainment, and sports are expected to create opportunities to “blend physical and digital experiences, enhance fan engagement, and drive growth on a global stage”.
Geopolitical Currents and the Appetite for Risky Debt
The influx of capital into the Electronic Arts bond deals is particularly noteworthy given the complex geopolitical backdrop of early 2026. Global markets are navigating sustained tensions in the Middle East, the specter of trade tariffs, and the disruptive force of artificial intelligence. Yet, these factors have not deterred investors from snapping up debt to finance Electronic Arts’ $55bn take-private.
The Saudi PIF Factor: Geopolitical Implications
The prominent role of Saudi Arabia’s Public Investment Fund (PIF) as the lead equity investor introduces a significant geopolitical dimension. The PIF, managing over $925 billion in assets, views this acquisition as a strategic move to establish Saudi Arabia as a global hub for games and sports, aligning with its “Vision 2030” diversification efforts. PIF’s deep pockets and long-term investment horizon offer stability often attractive to private equity deals.
However, the involvement of a sovereign wealth fund, particularly one with ties to Jared Kushner’s Affinity Partners, has not been without scrutiny. Concerns about national security risks, foreign access to consumer data, and control over American technology (including AI) have been voiced by organizations like the Communications Workers of America (CWA), who urged federal regulators to scrutinize the deal. Despite these geopolitical and regulatory considerations, the debt market demonstrated a remarkable willingness to participate. This indicates that the perceived financial stability and growth prospects of EA outweighed concerns tied to the source of equity capital.
AI Disruption and Market Confidence
The gaming industry, like many sectors, faces potential disruption from AI. Yet, EA itself projects $100 million in cost savings from AI tools, signaling a strategic embrace rather than fear of the technology. This forward-looking approach to AI, coupled with the inherent stability of established gaming franchises, likely contributed to investor confidence. In a volatile environment, proven entertainment IP acts as a relatively safe harbor.
The successful placement of this jumbo financing also suggests that while some sectors (like software) have seen “broader risk-off sentiment” due to AI uncertainty, the market distinguishes between general software and robust, content-driven interactive entertainment.
Broader Implications for Gaming M&A and Private Equity
The EA LBO is more than an isolated transaction; it’s a powerful signal for the broader M&A landscape and the future of private equity.
A Return to Mega-LBOs?
After a period where massive leveraged buyouts fell out of favor post-Global Financial Crisis, the EA deal marks a definitive comeback. It “waves the green flag on sponsors resuming mega-deal transactions,” indicating that easing borrowing costs and renewed boardroom confidence are aligning to facilitate large-cap M&A. The success of this deal, especially the oversubscription of its debt tranches, could embolden other private equity firms to pursue similar-sized targets in industries with reliable cash flows. This is crucial for private-equity debt appetite in 2026.
Creative Independence Post-Delisting
While private ownership offers freedom from public market pressures, it also introduces questions about creative independence. Historically, private equity has been associated with aggressive cost-cutting and a focus on short-term profits. For a creative industry like gaming, this can be a double-edged sword. While the stated goal is to “accelerate innovation and growth”, some within EA have expressed concern about potential workforce reductions and increased monetization post-acquisition. The challenge for the new owners will be to balance financial optimization with the nurturing of creative talent and IP development crucial for long-term success.
What it Means for 2027: Scenarios and Ripple Effects
As the EA $55bn take-private moves towards its expected close in Q1 FY27 (June 2026), its ripple effects will be closely watched by analysts and investors alike.
- Post-Deal EA Strategy: Under private ownership, expect EA to double down on its most successful franchises and potentially explore new growth vectors less scrutinized by quarterly reports. Strategic investments in areas like mobile gaming, esports, and potentially new IP development could accelerate. The projected cost savings will likely be reinvested to fuel growth or rapidly deleverage.
- Valuation Multiples: The deal itself sets a new benchmark for valuations in the gaming sector, particularly for companies with strong IP and predictable revenue streams. This could influence future M&A activities involving peers like Activision Blizzard (though now part of Microsoft) or Take-Two Interactive, raising their perceived floor valuations.
- Credit Market Confidence: The overwhelming investor demand for EA’s debt signals a powerful confidence in the leveraged finance markets, particularly for well-understood, resilient businesses. If EA successfully executes its deleveraging and growth strategy post-buyout, it will further validate the market’s willingness to finance large, complex LBOs, even amidst global uncertainty. This could pave the way for more “risky debt” deals tied to stable, high-quality assets.
- Geopolitical Influence in Tech: The PIF’s leading role solidifies the trend of sovereign wealth funds actively participating in global technology and entertainment sectors. This influence will continue to shape discussions around regulatory oversight, national interests, and the evolving landscape of global capital flows.
The investors snapping up debt to finance Electronic Arts’ $55bn take-private aren’t just betting on a video game company; they’re wagering on the enduring power of stable cash flows, strategic cost management, and a robust credit market willing to absorb risk for attractive yields. In a world grappling with uncertainty, the virtual battlefields of EA’s franchises offer a surprisingly solid ground for real-world financial gains.


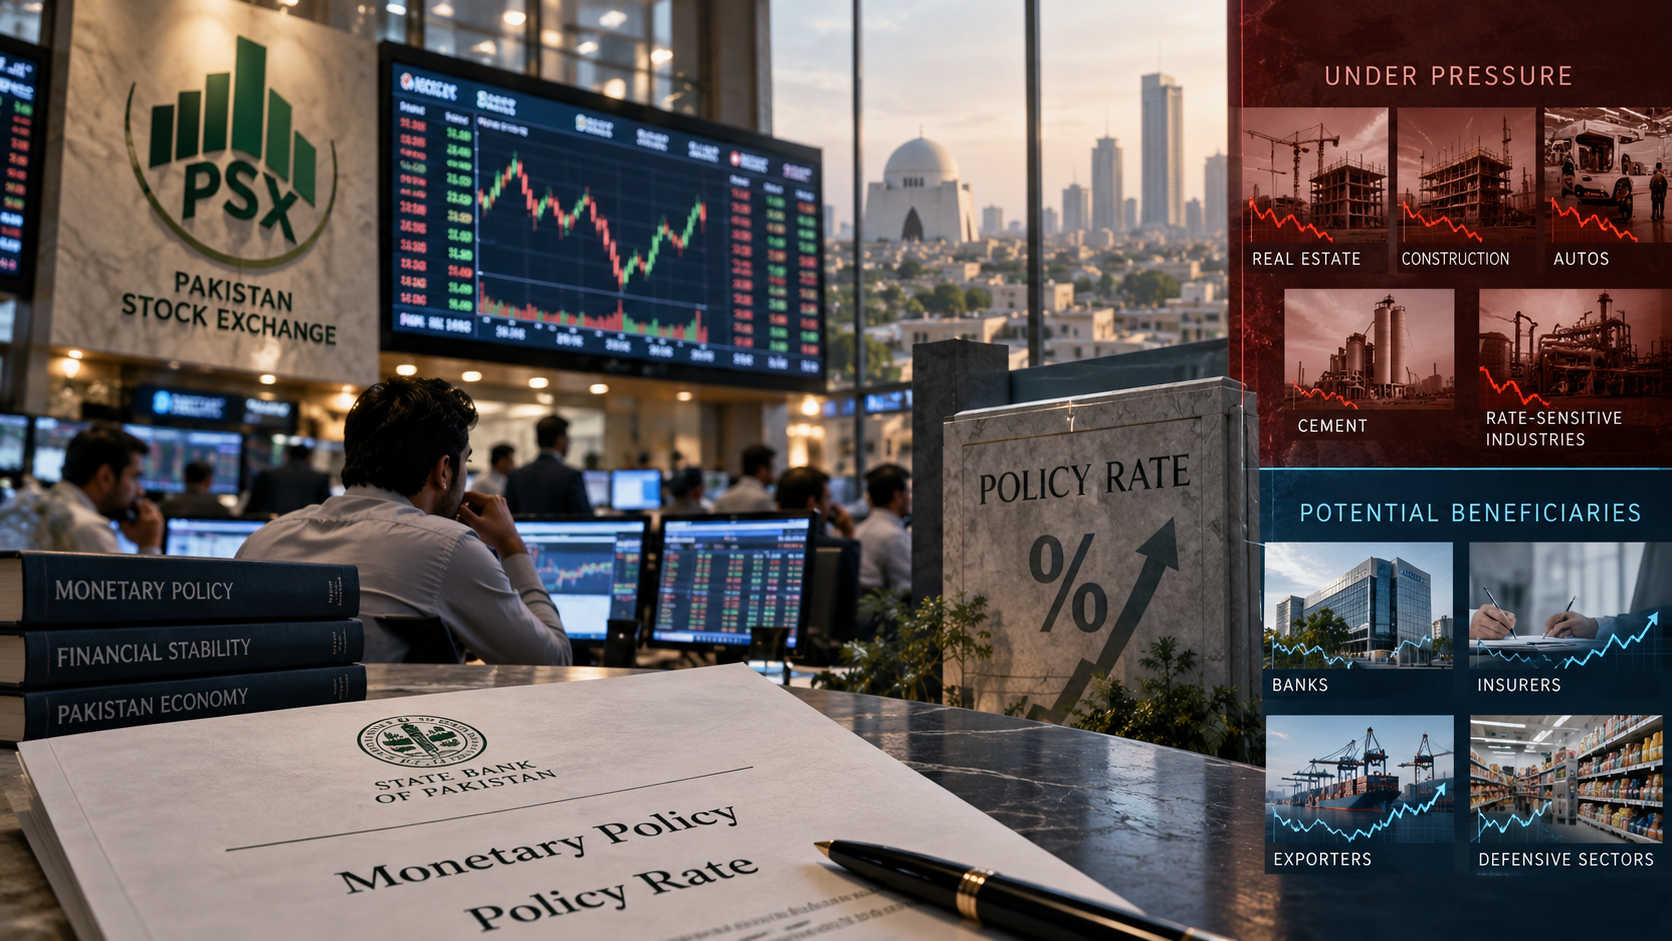
The KSE-100 was weak in the days around the SBP’s 26 October decision. Business Recorder reported the index down more than 800 points in the opening minutes of Monday, at about 161,542, and Tribune had it near 161,660 by midday, an intraday range of roughly 161,250 to 162,488. The Friday before, the index had lost more than 1,300 points as fighting between Saudi Arabia and the Houthis intensified and oil rose. Arif Habib’s head of research, Sana Tawfik, attributed the selling to two things: global weakness on higher oil and caution ahead of the rate decision.
The sectors named in reports were broad: automobile assemblers, cement, commercial banks, oil and gas explorers, oil marketing companies, power generation and refineries. Index heavyweights such as HUBCO, OGDC, MARI, PPL, HBL, MEBL and NBP traded lower at the opening.
The SBP then raised the policy rate by 50 bps to 12%, the first rise since April’s 100 bps move. The post-decision close was not retrieved; check it before publishing.
Why Sectors React Differently
Cement and autos (leveraged, demand-sensitive). Higher borrowing costs raise financing expenses for companies and can dampen private credit and investment. After April’s hike, analysts reported in Tribune that cyclicals such as cement would carry the weight of higher rates.
Commercial banks (mixed). The same April analysis suggested banks could see relative support over the medium term, as higher rates typically widen margins on assets. But banks also sold off in recent sessions, reflecting broader risk-off sentiment and sensitivity to government borrowing costs, so the benefit is not automatic.
Oil and gas explorers and oil marketers (oil-linked). These trade on the oil price and on circular-debt and pricing-policy questions as much as on rates. With Brent near $115, the oil story can outweigh the rate story.
Power producers and refineries. Sensitive to financing costs, energy-pricing decisions and the IMF’s push for timely tariff adjustments.
Fertiliser. Reported among the sectors with selling pressure after April’s hike; gas pricing and input costs matter alongside rates.
What the Hike Means for Valuations
Higher policy rates raise the return investors can earn on risk-free assets, which pushes down the price they will pay for equities. With inflation at 10.26% in September and a policy rate of 12%, the real return on fixed income is modestly positive. That competes with equities for capital, particularly after a strong multi-year run in the index.
Scenarios for the Next Few Weeks
- Oil retreats on a Qatari deal: inflation fears ease, and the market could recover some of the loss. The reply from Iran is due by the end of the week.
- Stalemate: headline-driven trading with sector rotation based on oil sensitivity.
- Escalation or another hike on 14 December: pressure on cyclicals and leveraged names.
These are scenarios, not forecasts.
What Investors Should Check
- Company debt levels and interest coverage (leveraged names are most exposed).
- Exposure to oil prices and government pricing policy.
- Dividend yield versus T-bill and deposit rates.
- Upcoming earnings season commentary on financing costs.
The PSX sold off ahead of a hike that was widely expected. What matters now is whether oil and the Iran talks ease or worsen the inflation outlook, because that, not Monday’s 50 bps, will decide the 14 December MPC and the market’s direction.
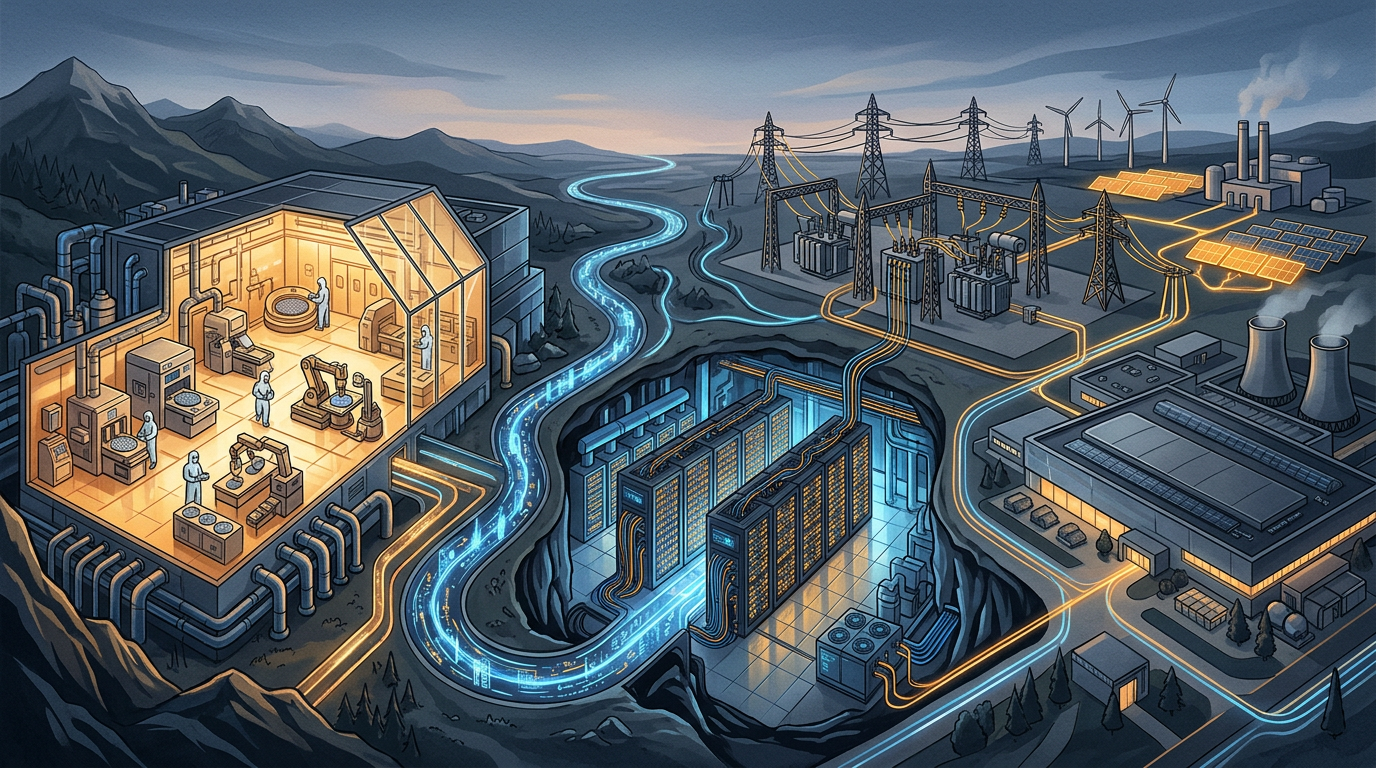
Investing in AI infrastructure—data centers, chips, and power—is particularly critical in 2026. As global economic growth diverges, capital has become far more sensitive to borrowing costs, forcing investors to look past compelling narratives and focus on realistic valuations. Rather than forecasting guaranteed returns, this guide examines key research methodologies and risk factors. According to the IMF’s October 2026 outlook, global growth is projected at 3.1% with inflation at 4.7%, even as its financial stability assessment cautions that underlying market vulnerabilities remain despite apparent resilience.
Key takeaways
- Match each investment decision to its time horizon, currency and ability to withstand losses.
- Separate observable earnings or contractual cash flows from optimistic forecasts.
- Compare diversification, fees, taxes, liquidity and regulatory restrictions before committing capital.
- Track primary institutional evidence and update assumptions when conditions change.
- Readers in Pakistan should consider rupee exposure and availability of regulated investment channels.
Why this matters now
The central question behind AI infrastructure investing 2026 is not merely what may happen next. It is which economic mechanisms could change cash flow, purchasing power or risk. The Bank for International Settlements’ 2026 review describes an economy supported by technological investment but constrained by geopolitical and fiscal pressures. A robust financial plan must therefore survive both a favourable and an adverse scenario.
Follow the investment chain, not just the headline
AI infrastructure spending flows through chips, advanced packaging, servers, networking, cooling, power equipment, real estate and utilities. Revenue can arrive at different times: hardware producers may book orders long before a data-centre tenant earns adequate cash flow from AI services. The BIS identifies AI investment as a support for recent global activity, but capital intensity can create financial fragility. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Semiconductors: strong demand does not erase cycles
Leading-edge manufacturing is capital intensive and technically complex. Constraints in memory, packaging or fabrication can create pricing power, while capacity expansions can later produce oversupply. Compare long-term contracts, customer concentration, inventory and returns on invested capital. A rising revenue line is insufficient if shareholders continually finance new assets.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Data centres and the cost of electricity
AI computing requires secure access to electricity, transmission connections, cooling water where relevant, and backup capacity. The International Energy Agency’s Energy and AI assessment documents the central role of electricity planning. Before evaluating an operator, examine energy contracts, utilization rates, construction delays and whether customers can meet long-term commitments. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Financing and correlated downside
The IMF warns that leveraged AI investments and concentrated exposures could magnify a valuation correction. Capital providers must distinguish contracted cash receipts from optimistic future sales estimates. Watch for circular financing, where investors and customers are economically dependent on each other’s ability to keep spending. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Pakistan’s realistic entry points
Pakistan is unlikely to replicate an advanced-chip fabrication cluster quickly. More plausible routes include enterprise software, cybersecurity, specialised engineering, managed services and targeted power or fibre investments where the economics support them. Any local investment thesis needs reliable energy, regulatory clarity, payment rails and skills rather than the assumption that every AI project is profitable. See the primary institutional research.
For practical analysis, separate the baseline, the upside case and the downside case. Document the specific development that would change your assessment. Assess timing: a promising long-term theme may still be inappropriate for cash needed within twelve months.
Comparison and decision framework
| Question | Stronger evidence | Warning sign |
|---|---|---|
| What drives returns? | Audited cash flows, clear contract or transparent index | Undefined or projected returns |
| What can go wrong? | Explicit scenario and downside analysis | Claims of guaranteed gains |
| Is it affordable to hold? | Low transparent fees and adequate liquidity | Leverage, costly spreads or lockups |
| Is access legitimate? | Appropriate licensing and clear legal rights | Unverified brokers or custody |
| Is the exposure diversified? | Multiple independent sources of return | One company, sector or currency |
What it means for Pakistani savers and investors
A Pakistani reader faces both international investment risk and local purchasing-power risk. For example, a foreign asset can rise in US-dollar terms while the rupee conversion and transaction costs alter the realized local outcome. The opposite can also occur. Record the starting exchange rate, applicable taxes, custody charges and capital-transfer restrictions, and confirm current requirements with the State Bank of Pakistan and the relevant securities regulator. Overseas access should not be assumed universally available.
An emergency reserve, expensive consumer debt and near-term family obligations deserve attention before any speculative allocation. A portfolio that cannot meet a sudden cash requirement may force sales at the worst moment. The objective is not to remove risk—impossible in markets—but to choose risks that fit the investor’s actual liabilities.
Risks, limitations and uncertainty
Institutional forecasts are conditional and can change after policy decisions, commodity shocks, conflict escalation or unexpectedly weak earnings. Historic correlations are not binding promises about future asset performance. The analysis does not provide live stock prices, current investment product quotes, real-time exchange rates or individualized tax advice. Prices, regulations and product eligibility should be checked on the transaction date.
Frequently asked questions
Is this a guaranteed investment opportunity?
No. Every financial asset or strategy involves uncertainty. The existence of a popular investment theme is not evidence that an individual security is fairly priced.
What should beginners examine first?
Understand the product, the financial loss you could tolerate, fees and liquidity. Verify the provider and decide whether the money may be needed soon.
How do interest rates affect the analysis?
They influence financing costs, discount rates, exchange rates and demand. The effect differs by sector, maturity and business balance sheet.
Can Pakistani residents invest in foreign markets?
Access depends on current foreign-exchange, banking, brokerage, securities and tax rules, and on the investor’s individual circumstances. Check current regulations and regulated providers rather than assuming access.
How often should this analysis be refreshed?
Review institutional economic releases monthly and re-evaluate immediately after material earnings, regulatory or policy changes. Avoid reacting mechanically to every daily market movement.
Is diversification enough to prevent losses?
No. Diversification may reduce company-specific risk but cannot eliminate broad market, currency, inflation or systemic risks.
Conclusion
Sound financial decisions begin with verifiable evidence, reasonable valuation, awareness of uncertainty and a plan that survives adverse outcomes. Readers should compare multiple independent sources and avoid letting a compelling headline substitute for due diligence.
Barclays reported second-quarter income of £8.3 billion, up £1.2 billion from a year earlier, and upgraded its full-year 2026 income target even as operating expenses climbed 7% year-on-year — a mixed but ultimately reassuring signal for UK banking-sector health as the country navigates elevated gilt yields and a new premiership.
Income Growth Outpaces a Rise in Costs
Barclays reported second-quarter operating expenses of £4.5 billion, up 7% year-on-year, which the bank attributed to business growth, inflation, and increased investment spending, according to CNBC’s markets coverage. Despite the cost increase, income rose to £8.3 billion, and adjusted earnings per share beat Wall Street consensus, prompting shares to initially react positively before falling more than 7% amid broader market volatility on the results day.
Group Chief Executive C.S. Venkatakrishnan struck a confident tone on the outlook, saying the bank was upgrading its 2026 Group income target to approximately £31.5 billion and remained committed to delivering all financial and distribution targets through 2028, according to the same CNBC report.
Why the Results Matter Beyond Barclays
The results land at a delicate moment for UK financial markets more broadly. Ten-year gilt yields have been trading near 5% amid uncertainty over new Prime Minister Andy Burnham’s fiscal programme, while 30-year yields — sensitive to long-term fiscal credibility — have hovered near multi-year highs. A major UK bank posting income growth and raising its full-year guidance amid that backdrop offers a data point suggesting the underlying corporate and consumer credit environment remains healthier than the gilt market’s elevated risk pricing might suggest on its own.
Context: A Resilient Consumer Backdrop
Barclays’ results also arrive alongside broader UK data that has surprised to the upside. UK retail sales rose 1% in June against expectations for a 0.3% decline, while consumer confidence climbed to a six-month high in July, supported by warmer weather and a spending lift tied to the football World Cup — trends that plausibly support the credit and transaction-fee income underpinning Barclays’ income beat. Annual consumer price inflation, meanwhile, slowed to a 15-month low of 2.6% in June, giving the Bank of England room to hold interest rates steady at its policy meeting this week.
The Cost Pressure Story Isn’t Unique to Barclays
The 7% rise in Barclays’ operating expenses reflects a broader pattern across UK banking: inflation-driven wage costs, continued investment in technology and compliance infrastructure, and the general cost of doing business in a higher-rate environment. How rival UK lenders navigate the same pressures in their own upcoming results will be a key signal of whether Barclays’ income upgrade reflects bank-specific execution strength or a sector-wide tailwind from resilient consumer activity.
What to Watch
Barclays’ upgraded £31.5 billion income target sets a clear benchmark against which the rest of 2026 results will be measured, while the sustainability of the current cost growth rate — set against a Bank of England policy backdrop still calibrated around inflation risk — will determine whether margin expansion continues into 2027. Investors will also be watching how the bank’s guidance holds up if gilt-market volatility around the new government’s fiscal plans intensifies.

Diesel Prices 2026–2027: Why Cheaper Crude May Not Mean Cheap Fuel

2027 Social Security COLA: Key Details and Dates

KSE-100 Sees Major Drop Post-SBP Rate Hike

Big Tech’s AI Spending Test: Can Revenue Catch Up With Capital Expenditure?

AI Infrastructure Investment Strategies for 2026

Pakistan Freelancers Tax 2026: Payments, Documentation and Formal Growth

Strait of Hormuz Crisis: What the Latest Tanker Attacks Mean for Oil, Shipping and Global Trade

AI Customer Service in 2026: What’s Working, What’s Failing, and What to Buy

Open a Savings Account Online: How to Actually Earn 10x the National Average Rate

Global Housing Market 2026: Where Prices Rise, Where They Don’t

PSX and KSE-100 Record Highs: An Insider’s Guide to Pakistan Stocks

So Delicious Dessert Recall: Affected Products, FDA Guidelines, and Consumer Action

Pakistan’s Current Account Deficit Narrows Sharply to $98 Million in August 2026

Japan Eyes 3.5% Defense Spending: What It Means for Bonds, Stocks, and the BOJ

Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities

Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World

Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns

China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech

What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact

15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide

Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025

Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide

Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation
-
 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
 Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
 Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
 Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
 AI11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
 Taxes & Compliance9 months ago
How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide