Analysis
Capital and Scarcity: The Mechanics Behind Ireland’s 18-Year Mortgage Peak

On a cold Tuesday morning in central Dublin, the queue outside a new residential development in Clongriffin didn’t consist of speculative investors or overseas institutional funds. Instead, it was filled with young professionals clutching pristine folders of bank statements, employment certificates, and salary clearances. This scene reflects a broader macroeconomic reality now sweeping across the state. Decades after the spectacular collapse of the Celtic Tiger, a new property milestone has arrived, though its structural drivers are fundamentally different from the loose credit environment of 2006.
The latest data reveals an unexpected trend. According to the quarterly analysis published by the Banking and Payments Federation Ireland, mortgage drawdowns for citizens entering the property market for the first time have reached their highest volume since the absolute peak of the mid-2000s property boom.
The picture is more complicated than a simple story of a booming economy. This lending surge occurs alongside a persistent housing shortage, high building material costs, and ECB interest rates that have squeezed borrowing capacity across the continent. Yet, the domestic appetite for residential debt remains strong. Buyers are stretching their financial limits to escape a hyper-inflationary rental market, changing the dynamics of the state’s retail banking sector.
The Core Development
The scale of modern credit expansion becomes clear when looking at the hard metrics of domestic loan issuance. To understand the current trajectory of the first-time buyer mortgage Ireland landscape, one must analyze the raw volume of capital flowing from retail lenders to consumers. In the 12 months leading up to October 24, 2025, licensed credit institutions in Ireland approved a total of 30,503 individual loan applications specifically earmarked for new market entrants. This isn’t just a marginal year-on-year increase. It represents a structural shift that pushed total drawdown values within this single demographic segment to an aggregate of $8.2 billion.
Data compiled by the Central Bank of Ireland indicates that first-time buyers now account for over 60% of all residential mortgage activity by value, effectively crowding out buy-to-let investors and second-time movers. The average loan size for an individual purchaser in Dublin has climbed to $345,000, an all-time record that reflects the steady rise in urban property values.
+-------------------------------------------------------------+
|     IRISH RESIDENTIAL MORTGAGE MARKET SHARE (BY VALUE)      |
+-------------------------------+-----------------------------+
| Market Segment                | Percentage Share            |
+-------------------------------+-----------------------------+
| First-Time Buyers             | 61.5%                       |
| Second-Time / Mover Buyers    | 24.0%                       |
| Residential Buy-to-Let        |  3.5%                       |
| Re-mortgage / Top-up          | 11.0%                       |
+-------------------------------+-----------------------------+
This high level of activity is happening despite a significant reduction in the number of active banks in the country. Following the departure of Ulster Bank and KBC Bank from the domestic market, the remaining three retail institutions—Allied Irish Banks, Bank of Ireland, and Permanent TSB—now manage a highly concentrated lending market.
This corporate concentration has not dampened consumer demand. Instead, the intense competition for market share among these remaining lenders has led to targeted product offerings for buyers who qualify for state assistance. The state’s current economic position, characterized by low unemployment and strong corporate tax receipts from multinational technology hubs, continues to support high consumer demand.
Wages in the professional services, engineering, and technology sectors have risen by an annualized 5.4% over the past year. This wage growth provides a steady stream of qualified applicants who can meet strict institutional lending requirements. Consequently, mortgage approval rates Dublin and surrounding commuter counties like Meath, Kildare, and Wicklow have stayed resilient, even as wider European credit growth slows down.
What is Driving the Surge in Irish First-Time Buyer Mortgages?
Featured Snippet Target: The surge in the first-time buyer mortgage Ireland market is driven by severe rental cost inflation, strong wage growth in corporate sectors, and state interventions like the Help-to-Buy scheme and the First Home Scheme. These factors allow buyers to bypass traditional deposit shortfalls and secure properties despite rising prices.
Policy Intervention and Market Mechanics
The current state of Irish housing market trends cannot be evaluated without considering state programs that alter normal market forces. The current credit expansion is partly driven by two specific policy tools implemented by the Department of Housing: the Help-to-Buy tax rebate scheme and the First Home Scheme equity loan system. These interventions were designed to address the deposit gap for middle-income workers, but they have also supported higher price floors across new housing developments.
       [State Equity Support: First Home Scheme]
                         │
                         ▼
  [Developer Top-Up] ──► [First-Time Buyer] ◄── [Commercial Bank Loan]
                         ▲
                         │
         [Tax Rebate: Help-to-Buy Scheme]
The Help-to-Buy initiative allows buyers to claim back up to $33,000 in income tax paid over the preceding four years to use directly as a property deposit. Meanwhile, the First Home Scheme operates as a shared-equity system, where the state takes up to a 30% stake in a new-build property to bridge the gap between the buyer’s maximum bank loan and the total purchase price. On paper, these initiatives solve the immediate liquidity problem that keeps young professionals trapped in high-rent tenancies.
In practice, however, they provide state-backed capital that matches the Central Bank of Ireland lending rules, which currently cap traditional borrowing at 4.0 times an applicant’s gross annual income. For example, a couple earning a combined salary of $95,000 can borrow a maximum of $380,000 under current macroprudential limits. By layering the tax rebate and the equity loan on top of this base, their total purchasing capacity can clear $480,000.
This dynamic helps explain why prices for new-build homes have risen faster than prices for older, second-hand properties. It also shows that the current high level of lending is closely tied to ongoing government fiscal support.
Downstream Consequences and Second-Order Effects
This long-term accumulation of mortgage debt has significant implications for Ireland’s broader economic stability and demographic trends. As young buyers dedicate a large share of their disposable income to servicing long-term debt, their broader spending patterns are shifting. Economist Dr. Conor O’Toole, writing in an assessment for the Economic and Social Research Institute, noted that households with high debt-to-income ratios are more exposed to external economic shocks, such as global downturns that could impact the country’s multi-national export sector.
Still, the immediate concern is the growing gap within the domestic property landscape. Because state equity programs apply almost exclusively to brand-new houses, first-time buyers are concentrated in specific geographic corridors. This has caused localized price spikes in suburban developments outside Dublin, while older urban properties face different market conditions.
+-------------------------------------------------------------+
|          NEW VS. SECOND-HAND HOUSING PRICE TRAJECTORY       |
+-------------------------------+-----------------------------+
| Property Category             | Annual Price Acceleration   |
+-------------------------------+-----------------------------+
| New-Build Residential Units   | +9.2%                       |
| Second-Hand Urban Apartments  | +3.1%                       |
| Commuter Belt Family Homes    | +7.8%                       |
+-------------------------------+-----------------------------+
The corporate sector is also adjusting to these conditions. Large institutional investors, who previously bought entire apartment complexes to rent out, are scaling back their purchases due to higher global interest rates. This retreat has allowed individual purchasers using affordable housing schemes Ireland to buy units in developments that would have previously been sold to international funds.
What follows, however, is a clear squeeze on supply. Every house bought by a first-time buyer removes a unit from the available supply for a long period, which keeps rental availability near historic lows. The national property registry shows that the turnover rate for residential properties sits at just 2.3% of total housing stock annually, which is well below the European average of 4.5%.
Challenging the Momentum
Is this high level of mortgage activity sustainable, or does it signal growing risks in the market? Many market analysts point to the strict credit assessments required under current lending rules as proof that the market is safe from a 2008-style collapse. Today’s borrowers must undergo rigorous stress testing against potential interest rate increases, and banks maintain much higher capital reserves than they did two decades ago.
The picture is more complicated when we consider structural supply deficits. Some independent analysts argue that current credit volumes are artificially inflated by a lack of alternative options.
               [Structural Supply Gap Overview]

  45,000 ───────────────────────────────── Estimated Annual Demand

  32,000 ═════════════════════════════ actual 2025 Completions

  13,000 ───────────────────────────── Net Annual Deficit
With single-bedroom apartments in Dublin regularly renting for over $2,400 per month, purchasing a home with a monthly mortgage payment of $1,700 can look like a rational financial choice, even at peak property valuations. This means demand may be driven more by high rental costs than by long-term confidence in asset values.
If the country’s multinational employment sector faces a downturn, many households could find themselves exposed. A household that bought a property at the top of the market using maximum state equity support has a limited financial buffer if property values drop or household income falls.
A Complex Equilibrium
The current high level of first-time buyer activity reflects a unique combination of strong domestic employment, targeted state support, and a persistent imbalance between housing supply and demand. This trend is distinct from the speculative, credit-driven bubble of the mid-2000s. Today’s market is shaped by working professionals using structured state programs to secure housing in a high-cost environment.
The central challenge for policymakers is clear. Government programs have successfully helped thousands of buyers enter the property market, but they have also supported high prices in a supply-constrained environment. Until overall housing construction matches structural demand, these record lending volumes will likely reflect the high cost of entry rather than an easy path to homeownership.
The Irish property market remains a complex environment where access to credit is a vital, yet expensive, asset.


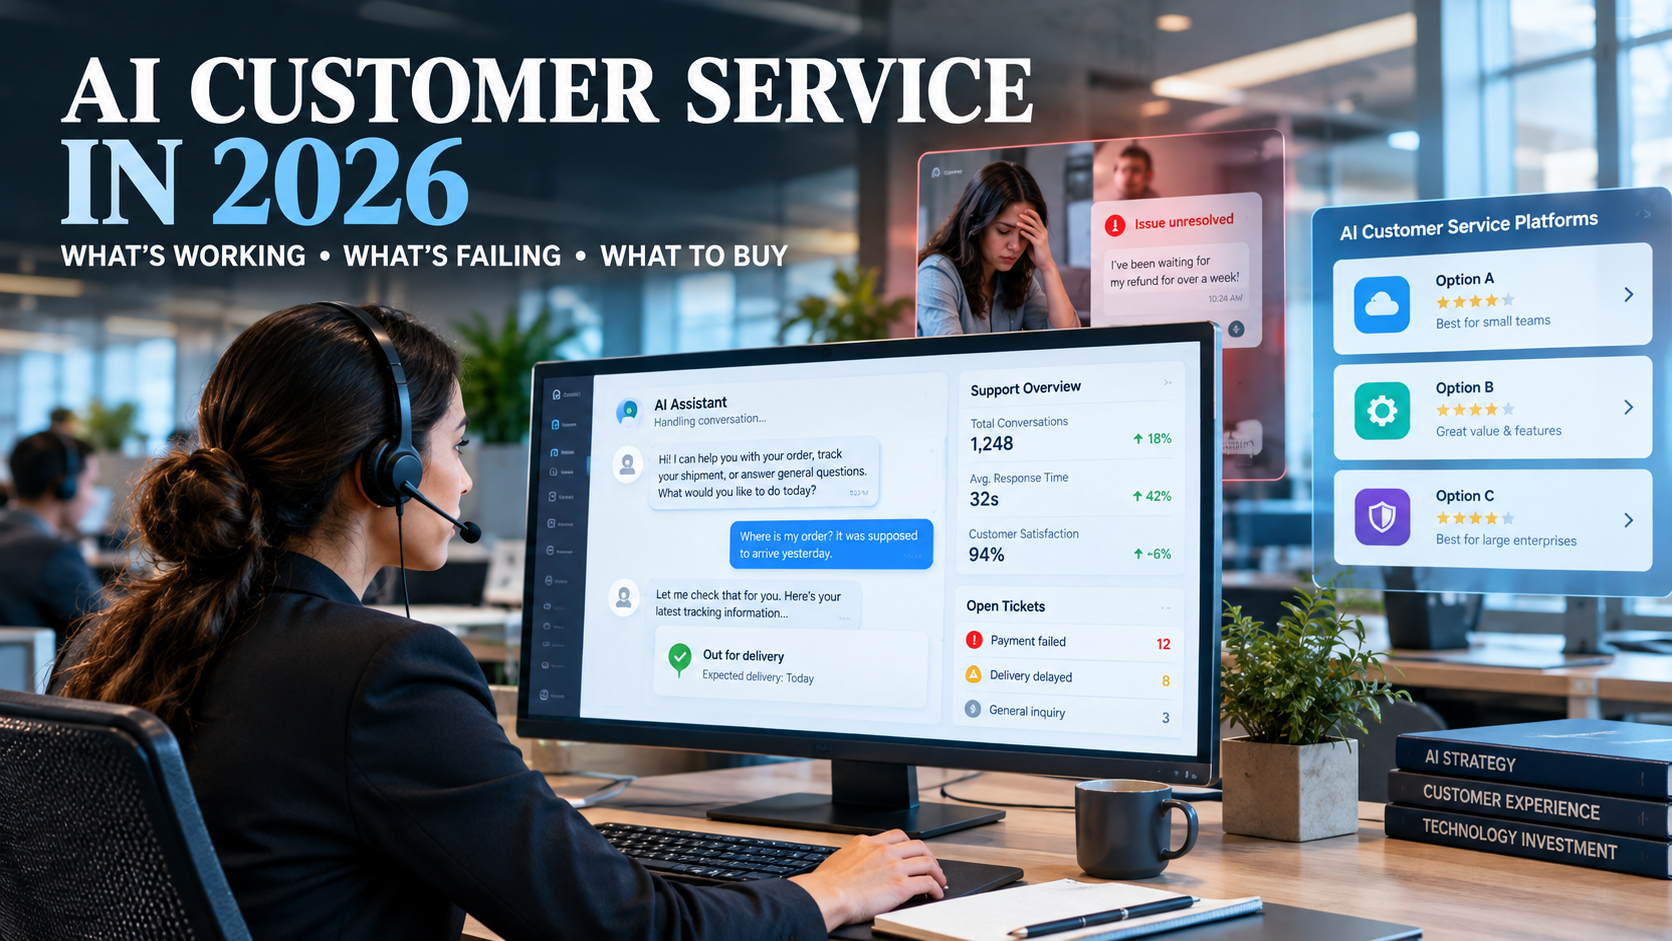
Almost every support team is now using AI. Far fewer customers say it solves their problem. That gap is the real story of AI customer service in 2026, and it decides which deployments pay off.
Key Takeaways
- Adoption doubled fast: Salesforce’s May 2026 survey of 3,075 service professionals found AI agent adoption rose from 39% to 66% in a year. getmacha
- Results lag: Only 24% of consumers said their last AI service interaction was fully resolved by AI alone, per an Ada and NewtonX study. getmacha
- Value shows up quickly: 70% of organizations deploying agents saw measurable value within 60 days. agilebrandguide
- Data is the blocker: 72% of service operations professionals call data readiness a major obstacle. agilebrandguide
- Forecast: Gartner expects agentic AI to autonomously resolve 80% of common customer service issues by 2029. raftlabs
What “AI Customer Service” Means Now
The first wave was scripted chatbots. The current wave is agentic AI: systems that interpret open-ended intent, read live customer data and resolve issues across connected systems without following a script. cygnet
The difference is action. A chatbot answers “where’s my order?” An agent checks the order system, issues the refund and updates the CRM.
The Adoption Numbers
| Metric | Figure | Source |
|---|---|---|
| Service orgs using AI agents | 66% (up from 39%) | Salesforce, May 2026 |
| Orgs using at least one form of AI | 85% | Salesforce |
| Teams at mature AI deployment | 10% | Intercom, Jan 2026 |
| Consumers fully resolved by AI alone | 24% | Ada/NewtonX, Mar 2026 |
| Agent use across customer-facing and internal work | 77% | Salesforce |
One caution applies to the headline adoption figures: Salesforce sells AI agents for service, so it has a commercial reason to publish momentum numbers. The Salesforce data is useful, but read it as a vendor’s view. Salesforce’s own service product page promotes the AI Agents Edition report, if you want to see how it frames the findings. getmacha
The Trust Gap
The most important number in this market isn’t adoption. It’s the 24% full-resolution rate. Companies are deploying AI faster than customers are being helped by it.
One compilation of 2026 statistics adds that 64% of customers wish companies would stop using AI in customer service, according to a Lorikeet survey. That’s a single-vendor figure, so use it as a directional signal rather than a settled fact. It still matches what most people have experienced: the bot that can’t escalate, the loop that never reaches a human. coworker
Where AI service typically fails:
- No escalation path: The customer can’t reach a person.
- Stale or fragmented data: The agent can’t see order history or account status.
- Overreach: The agent attempts complex or emotional cases it shouldn’t.
- Hidden AI: Customers feel tricked when they don’t know it’s a bot.
Where It Works
AI customer service performs best on narrow, high-volume, low-emotion requests: order status, password resets, returns and refunds, appointment changes and billing questions. 95% of service professionals say they trust AI for simple requests. Trust drops sharply as complexity rises. agilebrandguide
The ROI Question
Return figures vary widely. One 2026 compilation puts average ROI at $3.50 for every $1 spent, with leading organizations reaching 8x. Treat those as ceilings, not promises. The same compilation also notes 62% of service leaders worry about unpredictable AI costs. Usage-based pricing can erase savings if volume spikes. ringlyringly
A practical ROI model needs four inputs:
- Containment rate: Share of contacts fully resolved without a human
- Cost per contact: Human-handled versus AI-handled
- Quality impact: CSAT and repeat-contact rate, not just deflection
- Total AI cost: Licenses, usage fees, integration and ongoing tuning
Deflection that frustrates customers is a hidden cost. If containment rises while CSAT falls, you’re borrowing against retention.
Platform Landscape
Enterprise buyers commonly compare these platforms: Salesforce Agentforce, IBM watsonx Assistant, Microsoft Copilot Studio, Cognigy and Kore.ai. Each has strengths, so match the platform to your stack: cygnet
| If you already run… | Consider first |
|---|---|
| Salesforce CRM | Agentforce |
| Microsoft 365 and Dynamics | Copilot Studio |
| Heavy voice and contact-center volume | Cognigy |
| Multi-function (support, IT, HR) automation | Kore.ai |
| Regulated or hybrid environments | IBM watsonx Assistant |
This table is a starting framework, not a ranking. Integration depth with your CRM and ticketing systems usually matters more than headline features.
What the Workforce Impact Looks Like
Estimates of job impact are speculative and vary by source. One forecast says Gartner predicts organizations will replace 20% to 30% of service agents with generative AI by 2026. What’s more certain is that roles change: simpler tickets disappear, and humans handle harder, more emotional cases. That requires different training and often different pay structures. raftlabs
A Buyer’s Checklist
Before signing a contract, answer these:
- Data readiness: Is customer data clean, unified and accessible to the agent?
- Escalation design: Can customers reach a human in one step?
- Transparency: Do customers know they’re talking to AI?
- Governance: Who audits agent decisions and refunds?
- Metrics: Are you tracking resolution and CSAT, not only deflection?
- Pricing: What happens to cost when volume doubles?
What’s Next
Salesforce’s research frames the next phase around governance and workforce roles, recommending clear roles for AI architects and data specialists, plus transparent interactions with clear escalation to humans. That advice is sensible regardless of vendor. agilebrandguide
The Bottom Line
AI customer service works when it’s narrow, well-fed with data and honest about its limits. It fails when companies treat it as a headcount-cutting shortcut. With adoption now past 60%, competitive advantage will come less from having AI and more from deploying it without losing customer trust. Start with simple, high-volume requests, measure resolution rather than deflection, and keep a human exit visible.
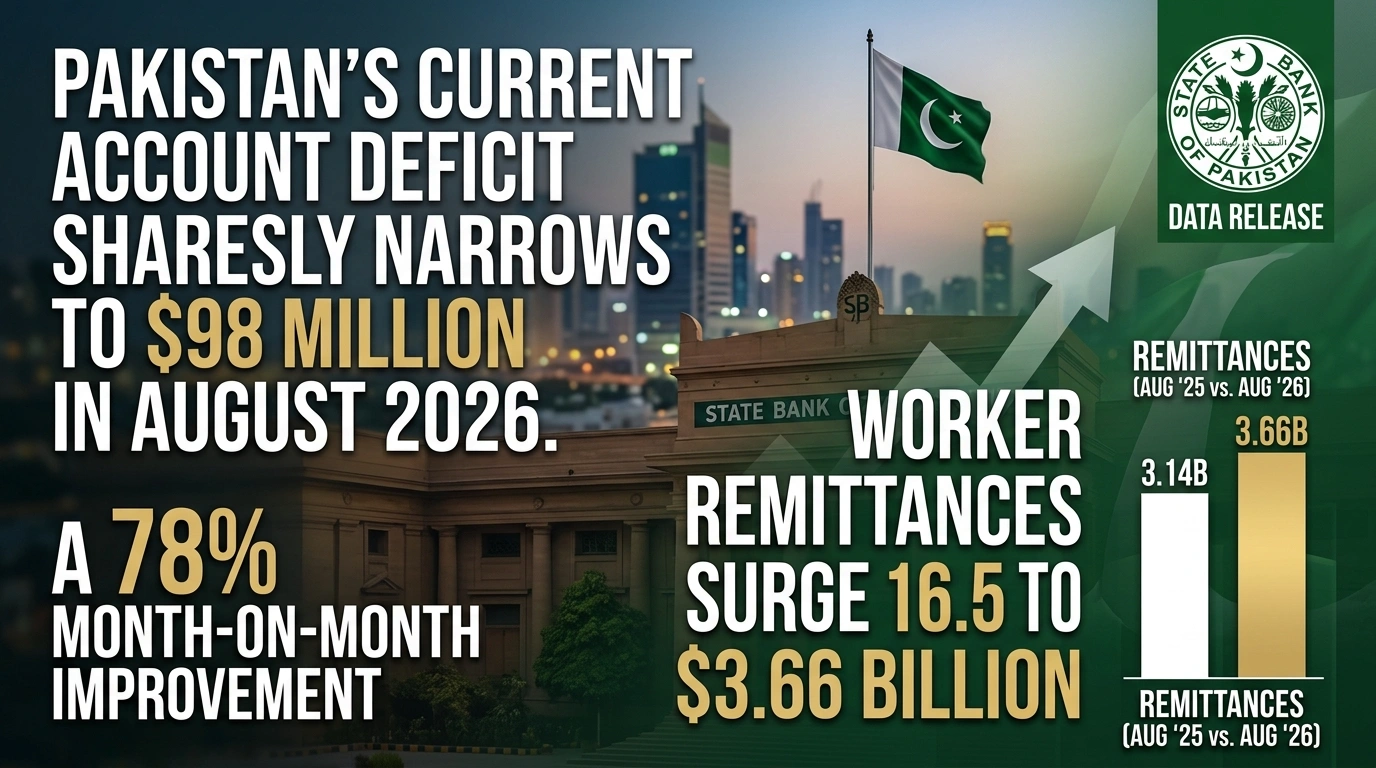
Karachi — Pakistan’s external balance demonstrated significant resilience as the monthly Current Account Deficit (CAD) contracted sharply to $98 million in August 2026, down 78% month-on-month from $445 million recorded in July 2026. Official data released by the State Bank of Pakistan (SBP) highlights that strong worker remittance inflows and steady export growth offset a surging import bill, providing crucial relief to the nation’s balance of payments.
Compared to the same period last year, the monthly shortfall narrowed by 69.7.3% from the $324 million deficit registered in August 2025. Cumulatively, during the first two months of the current fiscal year (2MFY27), Pakistan’s current account deficit stood at $543 million, marking a 36.3% reduction compared to the $853 million deficit incurred in 2MFY26, according to official economic indicators compiled by Dawn News Financial Analysis.
Key Drivers Behind August 2026 External Account Performance
1. Robust Remittance Inflows as the Core Anchor
Overseas Pakistani workers remitted $3.656 billion during August 2026, registering a 16.5% year-on-year (YoY) increase compared to $3.14 billion in August 2025 and a 0.7% month-on-month growth over July’s $3.63 billion.
- Saudi Arabia: Remained the largest contributor, accounting for $873.5 million (+19% YoY).
- United Arab Emirates (UAE): Inflows rose to $749.8 million (+17% YoY).
- United Kingdom & EU: Remittances from the UK totaled $563.7 million (+22% YoY), while European Union corridors dispatched $496 million (+7% MoM).
- United States: Inflows reached $308.9 million (+16% YoY).
Cumulative remittance inflows for 2MFY27 reached $7.29 billion, representing a 14.7% YoY increase from $6.36 billion recorded during the same period in FY26, as reported by Express Tribune Business.
2. Trade Balance and Import-Export Dynamics
- Exports of Goods & Services: Reached $3.33 billion in August 2026, reflecting a 5.0% YoY rise compared to $3.17 billion in August 2025.
- Imports of Goods & Services: Expanded to $6.64 billion, an increase of 8.0% YoY from $6.15 billion in August 2025, driven largely by essential industrial raw materials and energy imports required to support ongoing economic revival.
Macroeconomic Comparison Matrix: Current Account Breakdown
The table below illustrates the shift across key trade and primary income metrics for Pakistan’s balance of payments, as monitored by Trading Economics – Pakistan Balance of Payments:
| Economic Metric | August 2026 | July 2026 | August 2025 | 2MFY27 Cumulative | 2MFY26 Cumulative | YoY Shift (%) |
| Current Account Balance | -$98M | -$445M | -$324M | -$543M | -$853M | -36.3% |
| Worker Remittances | $3.656B | $3.630B | $3.140B | $7.286B | $6.353B | +14.7% |
| Total Exports (Goods & Services) | $3.330B | $3.180B | $3.170B | $6.510B | $6.120B | +6.37% |
| Total Imports (Goods & Services) | $6.640B | $6.520B | $6.150B | $13.160B | $12.380B | +6.30% |
| Foreign Exchange Reserves (Excl. CRR) | $17.280B | $16.900B | $14.520B | $17.280B | $14.520B | +19.0% |
| Net Foreign Direct Investment (FDI) | $315.9M | $185.2M | $175.1M | $501.1M | $342.0M | +46.5% |
Exchange Rate Competitiveness & FDI Momentum
REER and NEER Movements
Alongside the current account update, SBP data revealed that Pakistan’s Real Effective Exchange Rate (REER) index recorded a minor increase of 0.02% MoM, reaching 107.92 in August 2026 compared to 107.89 in July 2026.
Meanwhile, the Nominal Effective Exchange Rate (NEER) index depreciated by 0.79% MoM to 38.02 in August from 38.32 in July. While a REER above 100 indicates mild export price pressure, analysts cited by Reuters Global Markets note that exchange rate stability has helped maintain import predictability without severely penalizing key manufacturing sectors.
Surge in Foreign Direct Investment
Net Foreign Direct Investment (FDI) inflows saw a sharp increase, totaling $315.9 million in August 2026—an 80.4% YoY expansion compared to $175.1 million in August 2025. Key capital inflows targeted energy, telecommunications, and infrastructure projects, underscoring rising investor confidence supported by ongoing fiscal discipline and structural economic reforms monitored by Bloomberg Markets.
Macroeconomic Implications & Policy Outlook
- Foreign Reserve Buffer Expansion: Total SBP-held foreign exchange reserves (excluding CRR/SCRR) expanded to $17.28 billion, an increase of 19% YoY. This build-up strengthens Pakistan’s external liquidity buffer, providing over 2.6 months of import cover.
- Impact on Monetary Policy: The narrowing CAD and stable exchange rate dynamics offer the State Bank of Pakistan headroom to maintain a measured monetary easing cycle, encouraging domestic capital formation without reigniting demand-pull inflation.
- IMF Program Benchmark Compliance: Lower current account vulnerabilities position Pakistan favorably for ongoing review under international financial assistance programs, ensuring sustained access to multilateral funding channels.
Key Takeaways
- Japan is considering nearly doubling its midterm defense spending target to 3.5% of GDP — up from current levels of roughly 1.9% — under pressure from the Trump administration to match commitments made by NATO members and South Korea.
- A 3.5% target would amount to roughly ¥24 trillion annually, based on current GDP forecasts, more than double today’s spending level; a lower 3.0% target is also reportedly under consideration.
- Japanese 10-year government bond yields have already climbed to their highest levels since 1996, reflecting investor concern about how Japan — which carries the world’s highest debt-to-GDP ratio among advanced economies at nearly 240% — would finance the increase.
- Defense contractor stocks on the Tokyo Stock Exchange have risen in anticipation of the spending shift, even as broader market strategists warn the announcement could “send a shockwave through financial markets” concerned about PM Sanae Takaichi’s overall fiscal trajectory.
- A new five-year defense spending plan is expected by the end of 2026, meaning markets will be watching for confirmation of the final target — 3.0% or 3.5% — in the coming months.
Japan’s defense budget has broken its own record for 14 consecutive years, but the shift now under consideration in Tokyo represents something categorically different: a near-doubling of the country’s spending target, driven not by regional threat assessments alone but by direct pressure from Washington. For global economy watchers, the implications reach well beyond defense contractors into Japanese government bond markets, the yen, and the Bank of Japan’s already delicate policy path.
The New Target Under Consideration
According to people familiar with the matter, Japan’s government — under Prime Minister Sanae Takaichi — is weighing a new midterm defense spending target of 3.5% of GDP, aligning with commitments already made by NATO members and, more strikingly, by South Korea, which has pledged to reach that level over 10 years. Japanese defense officials have reportedly already signaled willingness to sharply increase spending in meetings with their US counterparts, though a lower 3.0% target remains an alternative under discussion.
To put the scale of this shift in context: until 2022, Japan maintained an informal spending ceiling around just 1% of GDP — a figure rooted in the country’s post-war pacifist constitutional framework. Takaichi has already accelerated Japan toward the more modest 2% target two years ahead of schedule, reaching nearly that level in the fiscal year ended March 2026. A jump to 3.5% would represent roughly ¥24 trillion in annual spending based on current GDP projections — more than double the current outlay, and a figure that dwarfs the roughly ¥9-10 trillion currently being requested for the next fiscal year’s defense budget alone.
Why Now: US Pressure and the NATO Benchmark
The push traces directly to the Trump administration’s broader effort to have allies shoulder more of their own defense costs and reduce reliance on the American military umbrella. The 3.5%-of-GDP figure has effectively become a global benchmark for US allies since NATO members adopted it, with Japan’s neighbors South Korea and Taiwan reportedly making similar pledges. For Tokyo specifically, the pressure carries added urgency given ongoing regional security concerns and the broader reassessment of US alliance commitments happening globally in 2026.
Notably, even Takaichi’s more modest current-year progress — nearing 2% of GDP two years ahead of schedule — already drew praise in Washington, but analysts at the Center for Strategic and International Studies have noted this success is likely to raise expectations for even further increases in Japan’s next defense buildup program, expected to be finalized by the end of 2026.
The Fiscal Math Problem
Japan’s fiscal starting position makes this proposal considerably more fraught than a simple budget-line adjustment. The country already carries the world’s highest debt-to-GDP ratio among advanced economies, at nearly 240% — meaning any large new spending commitment raises immediate questions about financing, whether through new bond issuance, tax increases, or some combination. Takaichi has publicly pledged to pursue a “responsible, proactive fiscal policy,” but bond markets are already signaling skepticism: Japanese 10-year government bond yields have climbed to their highest levels since 1996, reflecting growing investor concern about debt sustainability even before any formal 3.5% commitment is finalized.
Bond Market and Equity Reaction
The market response so far has bifurcated in a telling way. On one hand, major Japanese defense companies have risen on the Tokyo Stock Exchange as investors price in the prospect of substantially higher government contracts. On the other, the broader bond market reaction has been notably more cautious — rising JGB yields reflect concern that large new debt issuance to fund the buildup could strain Japan’s already stretched fiscal position, with potential knock-on effects for borrowing costs across the economy.
Spending Target Comparison
| Scenario | Target (% of GDP) | Est. Annual Spending | Status |
|---|---|---|---|
| Pre-2022 informal ceiling | ~1.0% | N/A | Historical baseline |
| Current target (achieved early) | ~2.0% | ~¥9-10 trillion | Reached FY2026, 2 years ahead of schedule |
| Under consideration (lower option) | 3.0% | N/A | Reportedly discussed |
| Under consideration (NATO-aligned option) | 3.5% | ~¥24 trillion | Reportedly discussed; matches South Korea’s 10-year pledge |
Why This Matters for the BOJ and Global Markets
A defense-spending shift of this magnitude complicates an already difficult picture for the Bank of Japan, which has been gradually moving away from decades of ultra-loose monetary policy even as it monitors the same Middle East-driven inflation pressures affecting central banks globally. Rising JGB yields tied to defense-spending concerns could interact with — and potentially amplify — the BOJ’s separate rate-hike considerations tied to domestic inflation, creating a more complex policy balancing act than either factor would present alone.
There’s also a broader global bond-market angle: some strategists have pointed to Japan’s rising rates as a factor behind a potential unwinding of the long-popular yen carry trade, in which investors borrow cheaply in Japan to invest in higher-yielding assets elsewhere. As Japanese yields climb — whether from defense spending, BOJ policy, or both — that trade becomes progressively less attractive, a dynamic some analysts have linked to recent volatility in global government bond markets more broadly, including the US Treasury market’s own yield surge this same week.
Frequently Asked Questions
Why is Japan considering raising defense spending to 3.5% of GDP?
The shift is driven primarily by pressure from the Trump administration for US allies to spend more on their own defense, aligning with commitments already made by NATO members and Japan’s neighbor South Korea, which pledged to reach 3.5% of GDP over 10 years.
How would Japan pay for a defense spending increase to 3.5% of GDP?
This remains unresolved and is a major market concern — Japan already carries the world’s highest debt-to-GDP ratio among advanced economies at nearly 240%, and rising Japanese government bond yields suggest investors are pricing in financing concerns ahead of any formal commitment.
When will Japan finalize its new defense spending target?
A new five-year defense spending plan is expected to be released by the end of 2026, which should clarify whether Japan settles on the 3.0% or 3.5% of GDP target currently under consideration.

Pakistan Freelancers Tax 2026: Payments, Documentation and Formal Growth

Strait of Hormuz Crisis: What the Latest Tanker Attacks Mean for Oil, Shipping and Global Trade

AI Customer Service in 2026: What’s Working, What’s Failing, and What to Buy

Open a Savings Account Online: How to Actually Earn 10x the National Average Rate

Global Housing Market 2026: Where Prices Rise, Where They Don’t

PSX and KSE-100 Record Highs: An Insider’s Guide to Pakistan Stocks

So Delicious Dessert Recall: Affected Products, FDA Guidelines, and Consumer Action

Pakistan’s Current Account Deficit Narrows Sharply to $98 Million in August 2026

Japan Eyes 3.5% Defense Spending: What It Means for Bonds, Stocks, and the BOJ

PSX & KSE Forecast 2026: Navigating the Latest IMF Reports & World Bank Metrics

Trump Administration’s Crypto Policy: Deregulation and the Future of Digital Assets

Monetary Policy and the Policy Rate

Gold, Silver & Bitcoin Prices Q4 2026: Wealth Management Strategies

Business Insurance for Digital Exports: Protecting Your Company in the AI Era

Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities

Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World

Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns

China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech

What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact

15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

Pakistan’s Stock Market Renaissance: How 2025’s Hottest Investment Opportunity Is Democratizing Wealth—A Complete Beginner’s Guide
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis

How to Become an Active Taxpayer on Pakistan’s FBR Active Taxpayer List (ATL) in 2026: A Step-by-Step Guide

Pakistan’s Economic Outlook 2025: Between Stabilization and the Shadow of Stagnation

Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-
 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-
 Analysis9 months ago
Debunking IMF Program Myths: Reconfiguring Engagement for True National Ownership in a Volatile World
-
 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-
 Asia10 months ago
China’s 50% Domestic Equipment Rule: The Semiconductor Mandate Reshaping Global Tech
-
 Global Economy10 months ago
What the U.S. Attack on Venezuela Could Mean for Oil and Canadian Crude Exports: The Economic Impact
-
 AI10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-
 Exports10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025